Tag: Payment Gateway

  • Designing a Crypto Checkout Flow: The 2026 Merchant Integration Guide

    Designing a Crypto Checkout Flow: The 2026 Merchant Integration Guide

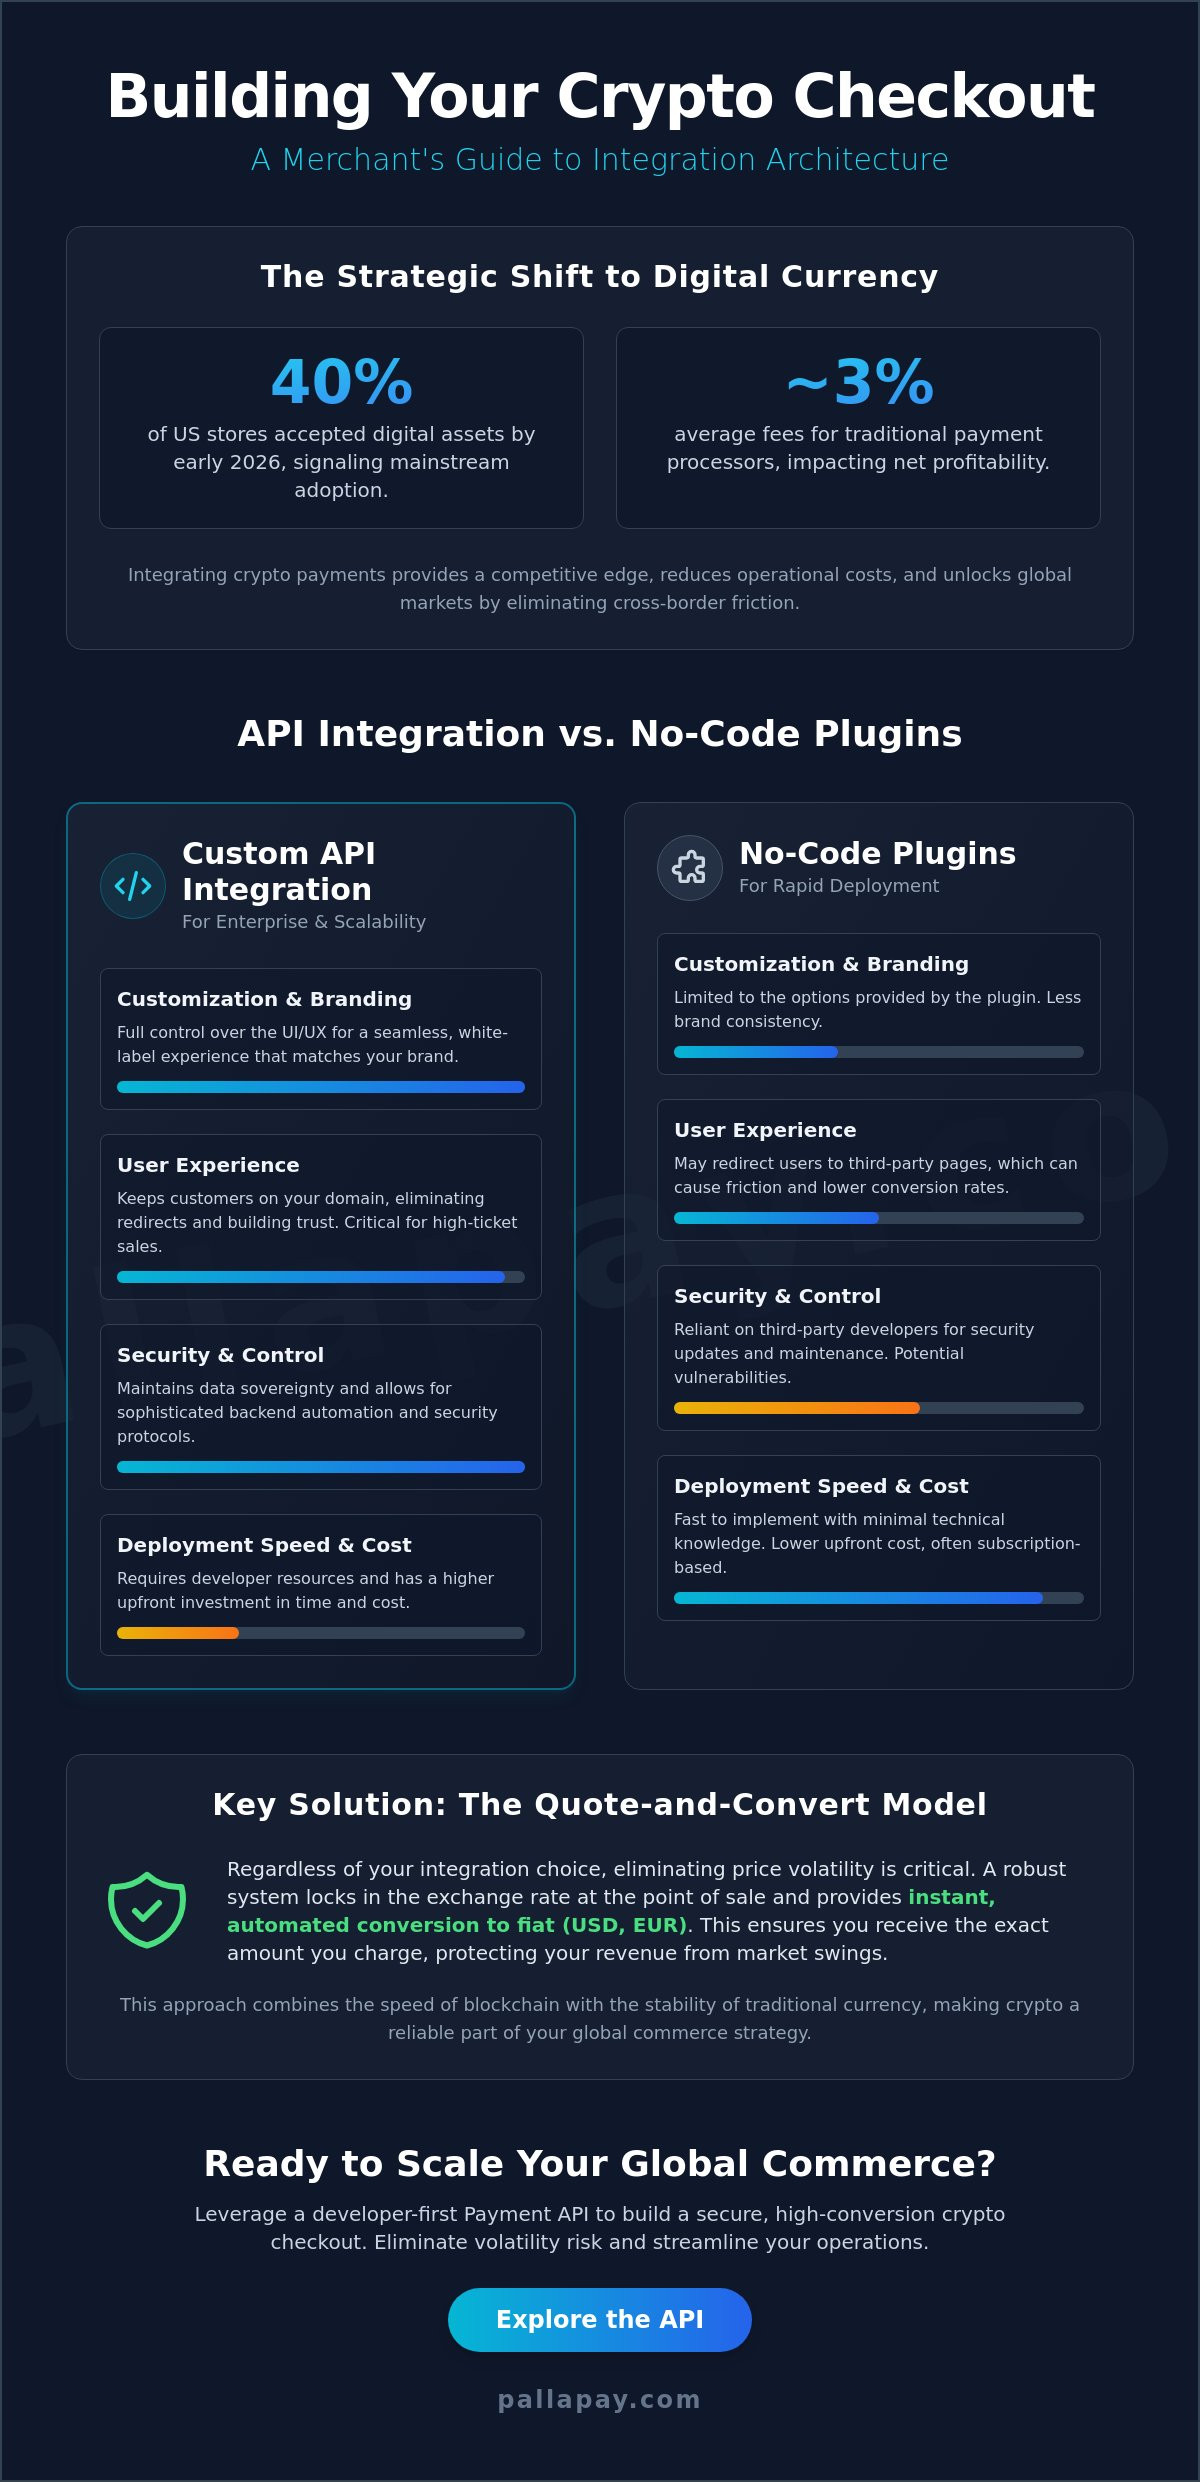
    With 40% of stores in the US now accepting digital assets according to market research from early 2026, the competitive landscape has shifted toward merchants who can offer the most efficient payment experience. You likely recognize that while customers demand flexibility, the technical hurdles of designing a crypto checkout flow often lead to revenue loss through friction or price volatility. It’s frustrating to watch a transaction stall because of slow confirmation times or complex wallet connections. We understand that your priority is a system that feels as reliable as a traditional credit card processor but operates with the speed of the blockchain.

    This guide provides the technical and strategic framework to build a secure, high-converting checkout that eliminates price risk through instant fiat conversion. You’ll learn how to implement a quote-and-convert model that locks in rates, ensuring you receive the exact USD or EUR amount regardless of market swings. We’ll also cover how to integrate an API for crypto payments that simplifies accounting and maintains compliance with the 2025 GENIUS Act and FATF Travel Rule requirements. By the end of this article, you’ll have a clear roadmap for turning crypto into a standard, effortless part of your global commerce operations.

    Key Takeaways

    • Understand the shift toward mainstream crypto adoption and how to capture global demand from tech-savvy demographics and unbanked populations.
    • Master the core principles of designing a crypto checkout flow to reduce friction using QR codes, automated network selection, and WalletConnect integrations.
    • Evaluate the technical trade-offs between bespoke API integrations and streamlined no-code plugins for major CMS platforms like Shopify and Magento.
    • Eliminate volatility risk by implementing automated fiat settlement that locks in exchange rates at the point of sale for instant conversion.
    • Scale your operations by connecting online gateways with physical crypto POS machines and high-volume OTC settlement services for a unified commerce experience.

    The Strategic Shift: Why Your Website Needs a Crypto Checkout in 2026

    The landscape of global commerce has fundamentally altered as digital assets move from speculative holdings to functional currency. Merchants now view understanding digital currencies as a core competency for maintaining a competitive edge in a digital-first economy. When you are designing a crypto checkout flow, you are effectively installing a high-speed liquidity bridge that bypasses the friction of legacy financial systems. This shift is driven by a consumer base that increasingly values the privacy, security, and autonomy inherent in blockchain-based transactions.

    Operational costs remain a primary driver for this transition. Traditional payment processors often levy merchant fees that average 3%, which significantly impacts the net profitability of high-volume businesses. In contrast, optimized crypto gateways offer a much leaner cost structure, allowing organizations to retain a larger portion of their revenue. Industry data from early 2026 indicates that nearly 90% of sellers have received direct requests for crypto options, signaling that consumer preference has reached a critical tipping point for mainstream adoption.

    Global Market Reach and the New Consumer

    Integrating crypto payments allows e-commerce brands to engage with a global audience without the traditional barriers of cross-border banking. This includes high-net-worth individuals who prefer spending their digital assets directly to maintain financial fluidity. By offering these options, you provide a frictionless experience for international customers who would otherwise face high currency exchange fees or transaction declines. It is a strategic expansion into a borderless market that operates beyond the limitations of traditional geography.

    Operational Efficiency: Speed and Security

    The speed of blockchain finality offers a distinct advantage over the multi-day settlement cycles of traditional banking. Once a transaction is confirmed on the ledger, the funds are secure and the risk of chargeback fraud is effectively eliminated. This is particularly critical for high-ticket retail where fraudulent disputes can cause significant financial disruption. Designing a crypto checkout flow also provides a reliable contingency against traditional processor outages, ensuring your storefront remains operational at all times. It is a professional bridge to a more resilient financial future.

    Choosing Your Integration Architecture: API vs. No-Code Plugins

    Decisions regarding technical architecture determine the long-term scalability of your digital storefront. When you’re designing a crypto checkout flow, the primary conflict often lies between the speed of deployment and the depth of customization. Small to mid-sized retailers frequently opt for ready-made solutions to minimize upfront development costs. Conversely, enterprise-level organizations require bespoke integrations to maintain brand consistency and data sovereignty. This choice dictates how your business will handle future volume increases and network upgrades.

    E-commerce Plugins for Rapid Deployment

    CMS plugins for platforms like WordPress, Shopify, and Magento provide a streamlined path to market. These third-party scripts handle the heavy lifting of wallet connectivity and transaction monitoring. However, security remains a paramount concern. It’s essential to ensure your checkout environment is isolated from core customer data to prevent cross-site scripting vulnerabilities. While plugins offer ease of use, they require regular maintenance to remain compatible with evolving blockchain network updates. If a plugin fails to update alongside a major wallet provider, your conversion rates will suffer.

    Custom API Integration for Enterprise Scalability

    For businesses that demand full control over the user journey, a developer-first approach is the definitive choice. Leveraging a Payment API allows you to build a white-label checkout that keeps the customer entirely on your domain. This eliminates the psychological friction caused by redirecting users to external payment pages. You can design every pixel of the interface to align with your brand’s aesthetic, which is a critical factor for building trust in the high-ticket retail sector.

    Custom integrations also allow for sophisticated backend automation through webhooks. These tools provide real-time order status updates, enabling your system to trigger automated fulfillment the moment a transaction reaches the required number of network confirmations. This level of technical maturity ensures that your operations scale without increasing manual overhead. If you’re ready to build a tailored solution, exploring the API for Crypto Payments can provide the robust infrastructure needed for high-volume commerce.

    Hosted payment pages represent a practical middle ground for many growing businesses. They offer a no-code approach where the service provider manages the entire UI, significantly reducing your internal technical and regulatory burden. This is an excellent choice for rapid market entry or for testing crypto demand within a specific product line before committing to a full-scale custom build. Ultimately, the right architecture depends on your internal developer resources and your long-term vision for the customer experience. Selecting the right path early prevents costly migrations later.

    Designing a High-Conversion Crypto Checkout Flow (UX/UI Principles)

    Designing a crypto checkout flow requires a departure from the static input fields of traditional finance toward an interactive, real-time handshake between digital environments. The primary goal is to minimize cognitive load while ensuring absolute precision. By integrating a ‘WalletConnect’ button alongside a high-resolution QR code, you provide a seamless transition for both mobile and desktop users. This dual-path approach facilitates an immediate connection that feels as intuitive as a standard digital wallet payment. It works because it respects the user’s existing habits.

    Transparency is the bedrock of conversion. Your interface must display real-time exchange rates with a clear price-lock countdown, typically lasting 15 to 20 minutes. This prevents the anxiety associated with market volatility during the transaction window. For mobile users, a one-tap payment experience is essential. By deep-linking directly to a secure crypto wallet, you remove the need for manual copying and pasting, which is often where user errors occur. Efficiency in design leads directly to efficiency in settlement.

    Handling Wallet Connectivity and User Errors

    Effective checkout design prioritizes error prevention through smart address validation and clear network labeling. If a user attempts to send Bitcoin to an Ethereum address, the system should flag the incompatibility immediately. Best practices include using dynamic QR codes that embed both the destination address and the exact payment amount to prevent manual entry mistakes. You should also provide brief explanations of network costs to ensure users include enough for the transaction to confirm. These small details reduce support tickets and protect your revenue.

    Optimizing for Trust and Transparency

    Because blockchain transactions aren’t always instantaneous, maintaining a feedback loop is vital for customer retention. A live status bar showing confirmation progress, such as ‘1 of 3 confirmations received,’ keeps the user engaged and reduces the urge to refresh the page. Once the transaction is finalized, an automated email receipt should follow. This receipt must contain the transaction hash for the customer’s records. This level of technical detail provides peace of mind and establishes your brand as a professional entity. Finally, ensure your refund policy is explicitly stated. Clarify how returns are calculated in fiat terms to avoid disputes over price fluctuations. Clear communication builds long-term loyalty.
    Designing a Crypto Checkout Flow: The 2026 Merchant Integration Guide

    Institutional reliability in the digital asset space depends on two critical factors: price stability and regulatory adherence. When you are designing a crypto checkout flow, the primary objective is to convert digital volatility into predictable fiat revenue. This process ensures that the amount your customer pays in Bitcoin or USDT matches the exact value you receive in your business account. By removing the need for merchants to hold volatile assets, the system functions as a professional bridge between innovative payment rails and traditional financial reporting.

    Regulatory clarity has reached a new peak following the 2025 GENIUS Act, which brought payment stablecoins under the Bank Secrecy Act (BSA). As of 2026, 85 out of 117 jurisdictions have implemented the FATF Travel Rule, requiring the sharing of sender and recipient information for transactions. Utilizing a provider with MSB registration in the USA and Canada ensures your operations remain compliant with these evolving standards. This infrastructure provides the “regulatory peace of mind” required for enterprise-level commerce.

    Fiat Settlement: Protecting Your Profit Margins

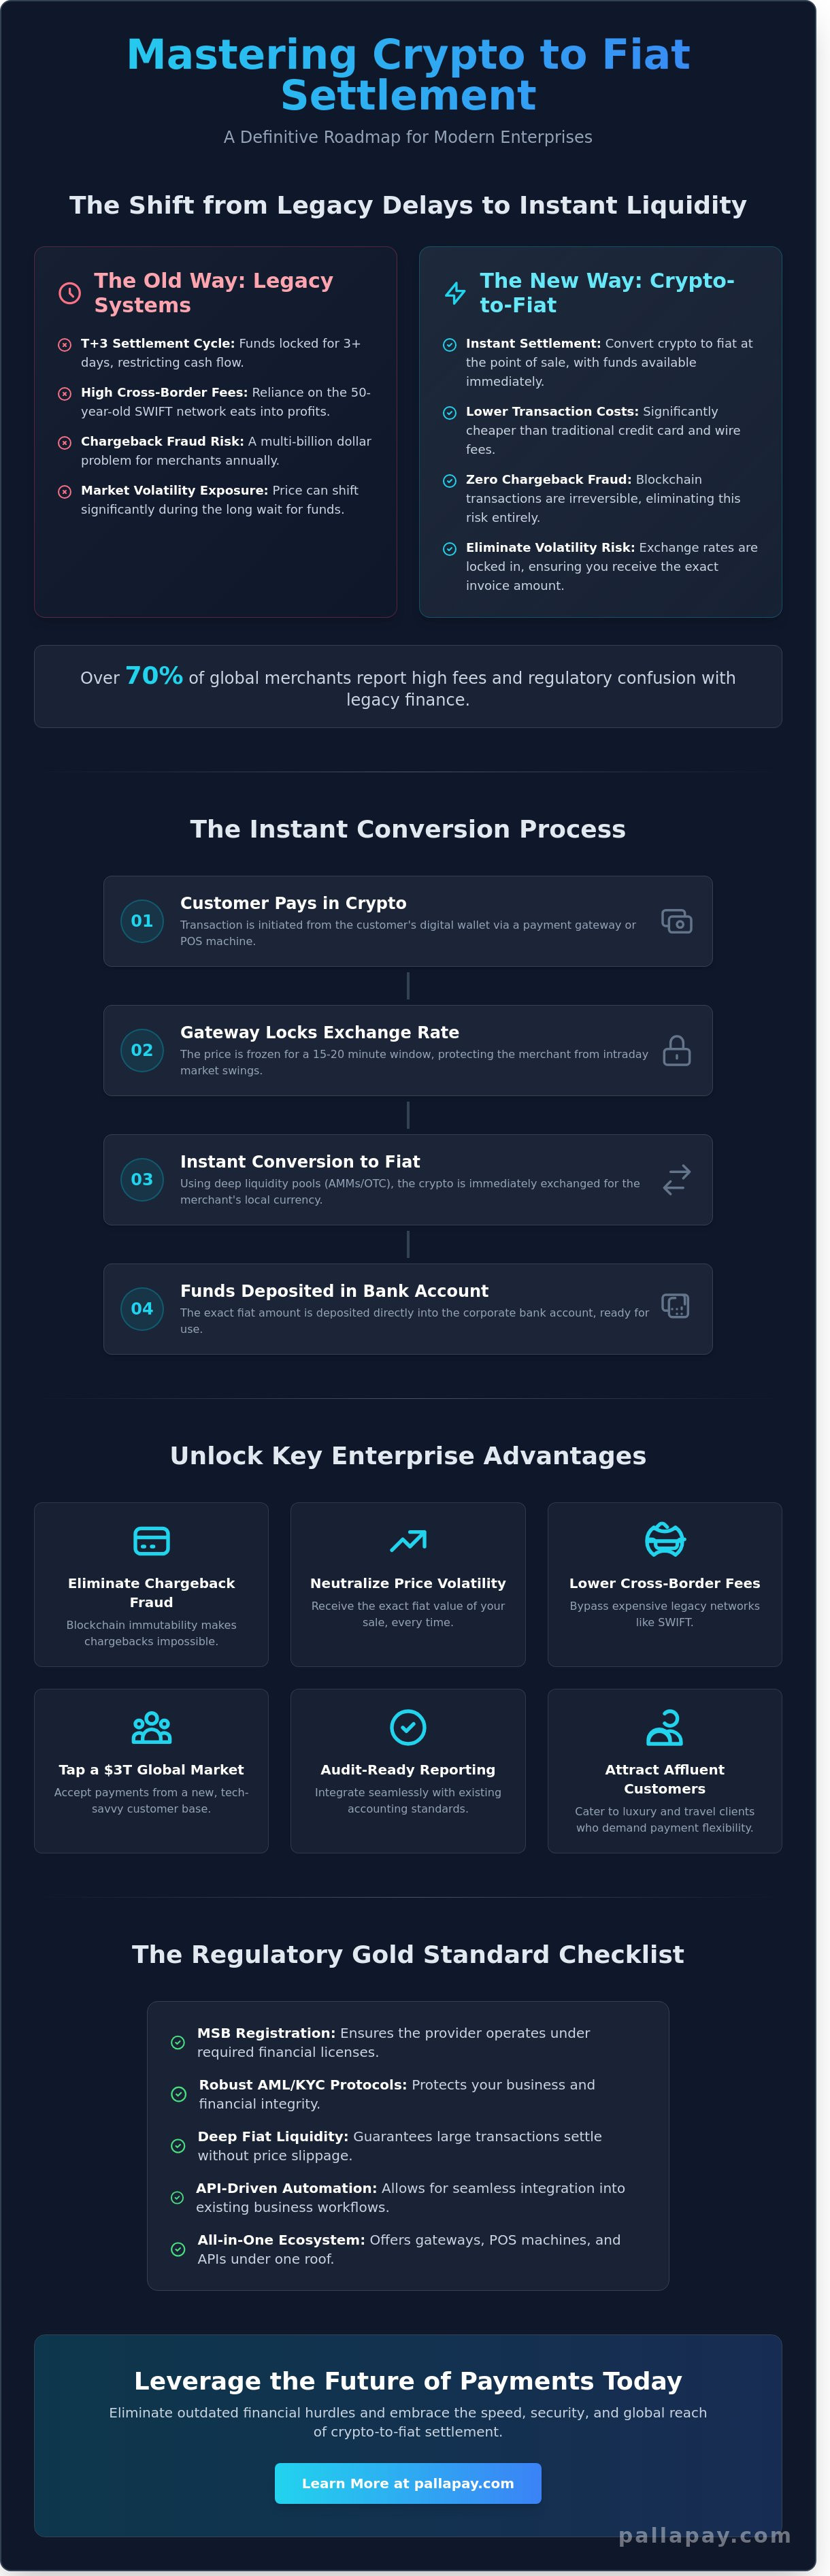
    Automated fiat settlement is the technological answer to market volatility. The system locks in the exchange rate at the moment of sale, ensuring that a market crash during the transaction confirmation window does not erode your margins. Merchants can choose between threshold-based payouts or scheduled daily and weekly settlements. This flexibility allows for precise cash flow management across multiple currency accounts, including USD, EUR, and GBP. If you need to cover international operational costs, using a crypto off-ramp enables you to move funds directly to your corporate bank account with minimal friction.

    Accounting and Reporting for Digital Revenue

    Modern commerce requires unified reporting that syncs effortlessly with existing ERP systems. Your checkout flow should generate tax-compliant reports that treat crypto sales with the same rigor as credit card transactions. This includes capturing the transaction hash and the fiat value at the time of execution. Handling refunds is a common operational hurdle; the standard practice is to refund the original fiat value rather than the crypto amount. This protects your business from paying back more than was originally received if the asset’s price has increased. High-volume accounts must also maintain strict KYC and AML protocols to satisfy global banking partners. If you are ready to stabilize your digital revenue, you can convert crypto to fiat instantly through our automated settlement engine.

    Scaling with the Pallapay Ecosystem: Beyond the Website

    While designing a crypto checkout flow is the definitive first step toward digital transformation, true operational efficiency comes from integrating these digital rails into a broader, unified ecosystem. A siloed web checkout limits your growth potential by creating data fragmentation between different sales channels. Scalable businesses require a comprehensive architecture that connects online revenue with physical retail operations and corporate spending. This holistic approach ensures that your digital assets are not just a payment option, but a core component of your global financial strategy.

    Unified Commerce: Connecting Web and Retail

    Modern merchants shouldn’t have to manage separate reporting systems for their website and their retail store. By connecting your online gateway with physical Crypto POS machines, you synchronize sales data across all touchpoints in real-time. This centralized approach ensures that inventory levels and revenue tracking remain accurate; it doesn’t matter whether the customer pays via a mobile browser or at a physical counter. You provide a consistent brand experience that builds trust with your global audience while simplifying your internal accounting processes. This level of synchronization is the technological answer to the complexity of omnichannel commerce.

    Advanced Liquidity and Corporate Spending

    High-volume merchants often face liquidity challenges when they need to convert large digital asset holdings into fiat for operational needs. Utilizing an OTC crypto exchange provides the deep liquidity required for enterprise-level settlements without impacting market prices. This infrastructure is essential for businesses that use digital assets for B2B settlements or employee payroll. The journey from your first API call to a fiat withdrawal is designed to be a streamlined, professional progression:

    • Integration: Implement the API for crypto payments to start accepting digital assets on your domain.
    • Settlement: Configure automated fiat settlement to lock in exchange rates and eliminate volatility.
    • Consolidation: View unified revenue data from both web gateways and physical POS terminals.
    • Utilization: Withdraw funds to your corporate bank account or use the Pallapay Mastercard for immediate corporate spending.

    Technical complexity shouldn’t be a barrier to global expansion. Professional merchants in over 180 countries have access to dedicated technical assistance to ensure their systems remain operational. By designing a crypto checkout flow that sits at the center of a wider ecosystem, you bridge the gap between disruptive innovation and institutional reliability. This isn’t just about accepting a new form of payment; it’s about adopting a forward-thinking strategic partner that handles complex background processes so you can focus on growth.

    Future-Proofing Your Global Commerce Strategy

    Adopting digital asset payments is no longer a speculative choice; it’s a strategic necessity for merchants seeking to capture a global, tech-savvy market. By prioritizing a friction-free user experience and implementing automated fiat settlement, you eliminate the traditional barriers of price volatility and technical complexity. Designing a crypto checkout flow is the essential first step in building this professional bridge between innovative financial technology and institutional reliability. You’ve seen how a unified architecture ensures that your online data remains synchronized with your physical retail operations, creating a truly omnichannel business model.

    Pallapay provides the robust infrastructure needed to facilitate this evolution. As a regulated MSB in the USA and Canada, we offer the security and compliance required for large-scale operations. Our ecosystem supports global settlements in over 180 countries and includes a Red Dot Award-winning POS system for your physical storefronts. This comprehensive approach allows you to focus on your core business while we handle the background mechanics of secure, real-time conversions. Integrate the Pallapay Payment API today to secure your place in the inevitable global evolution of commerce. Your business is ready for the next level of financial efficiency.

    Frequently Asked Questions

    How long does it take to integrate crypto payments on a website?

    Integration time varies from minutes to days based on your specific technical approach. No-code plugins offer immediate activation for standard e-commerce stores; however, designing a crypto checkout flow with a custom API provides the scalability required for enterprise operations. This flexibility allows you to choose the implementation speed that matches your current resource availability. Most merchants find they can go live with basic functionality in under an hour.

    Do I need to hold cryptocurrency on my balance sheet to accept it?

    You don’t need to hold cryptocurrency on your balance sheet to accept it as a payment method. Most professional gateways offer automated fiat settlement that converts digital assets into USD, EUR, or other local currencies immediately at the point of sale. This approach eliminates balance sheet volatility and simplifies your tax reporting by treating the transaction like a standard fiat sale. It’s an efficient way to modernize your payment stack.

    What are the transaction fees for crypto payments compared to credit cards?

    Crypto transaction fees are typically lower than the 3% average associated with traditional credit card processing. By reducing the reliance on legacy banking intermediaries and complex settlement networks, digital payments provide a more cost-effective alternative for global commerce. This reduction in overhead helps merchants preserve their profit margins on every international sale. Lower fees mean your business retains more revenue without sacrificing the speed of transaction confirmation.

    Is it safe to accept Bitcoin and USDT on an e-commerce store?

    Accepting Bitcoin and USDT is safe when using a gateway that prioritizes institutional-grade security and regulatory compliance. The permanent nature of blockchain records removes the threat of chargeback fraud; this is a significant advantage over traditional credit card systems. Designing a crypto checkout flow through a regulated provider ensures your business stays aligned with the latest global financial standards. It provides a secure environment for both your store and your customers.

    Can I automatically convert crypto payments to USD or EUR?

    You can automatically convert digital payments to major fiat currencies like USD, EUR, or GBP using an instant settlement feature. This tool locks in the exchange rate the moment the customer completes the transaction at your checkout. It ensures you receive the exact fiat amount regardless of any subsequent market fluctuations or price swings. This functionality provides the stability needed to manage a predictable and reliable business cash flow.

    How do I handle customer refunds for crypto transactions?

    Refunds are typically processed based on the original fiat value of the transaction rather than the specific amount of crypto sent. This practice protects your business from asset price increases that might occur after the purchase was finalized. Most professional gateways provide a dedicated merchant dashboard to manage these payouts efficiently and transparently. Clear communication with your customers about this policy helps maintain trust and prevents disputes during the return process.

    Which cryptocurrencies should my business accept in 2026?

    Your business should prioritize high-liquidity assets like Bitcoin, Ethereum, and stablecoins such as USDT in 2026. Stablecoins are particularly effective for everyday commerce because they mirror the value of traditional fiat currencies and minimize price risk. Offering a mix of these assets ensures you reach the widest possible demographic of digital wallet holders globally. This variety allows your customers to choose the asset that best fits their personal financial preferences.

    Do I need a special bank account to receive fiat settlements from crypto sales?

    You don’t need a special bank account to receive fiat settlements from your crypto sales. Standard business bank accounts are fully compatible with the fiat transfers initiated by your payment gateway provider. The gateway acts as the professional bridge; it converts the crypto and sends the resulting fiat via standard bank transfer rails. This ensures that your digital revenue integrates seamlessly with your existing financial infrastructure without requiring new banking relationships.

    Disclaimer

    The information provided on this website and blog is for general informational and educational purposes only and does not constitute financial, investment, legal, tax, or other professional advice.
    Cryptocurrency and digital asset services may be subject to regulatory restrictions in certain jurisdictions. Users are solely responsible for ensuring compliance with applicable local laws and regulations before using any products or services mentioned on this website.
    PallaPay does not guarantee the accuracy, completeness, or timeliness of any information published and accepts no liability for any loss or damages arising from reliance on the content. Any opinions expressed are those of the respective authors and may change without notice.
    Certain services, features, or products referenced may be provided through third-party partners, licensed entities, or affiliated service providers subject to separate terms and regulatory approvals. Availability of services may vary by country or region.
    This website may contain references to digital assets, virtual currencies, or blockchain-related services that are not available to residents of certain jurisdictions, including where prohibited by law. Nothing on this website constitutes an offer, solicitation, or recommendation to buy or sell any financial instrument or virtual asset.
  • How to Choose a Crypto Payment Processor: A 2026 Stakeholder Guide

    How to Choose a Crypto Payment Processor: A 2026 Stakeholder Guide

    With crypto transactions now accounting for up to 26% of total revenue at merchants that have adopted the technology, the decision to integrate digital assets is no longer a speculative experiment. It is a strategic necessity for global commerce. However, for most organizations, the primary hurdle isn’t interest; it’s the challenge of knowing how to choose a crypto payment processor that satisfies legal, financial, and technical stakeholders. You likely feel the pressure to innovate while facing internal resistance regarding price volatility and the evolving regulatory landscape of 2026.

    This guide empowers you to master a strategic framework for selecting a partner that offers institutional-grade security and seamless utility. We’ll provide a defensible business case to help you secure executive buy-in and a vetting checklist to ensure your chosen provider handles complex background processes with absolute reliability. By the end of this article, you’ll have a clear roadmap for launching a low-risk pilot program that bridges the gap between disruptive technology and established financial practices. We will move quickly from high-level value propositions to the functional evidence required for a successful transition.

    Key Takeaways

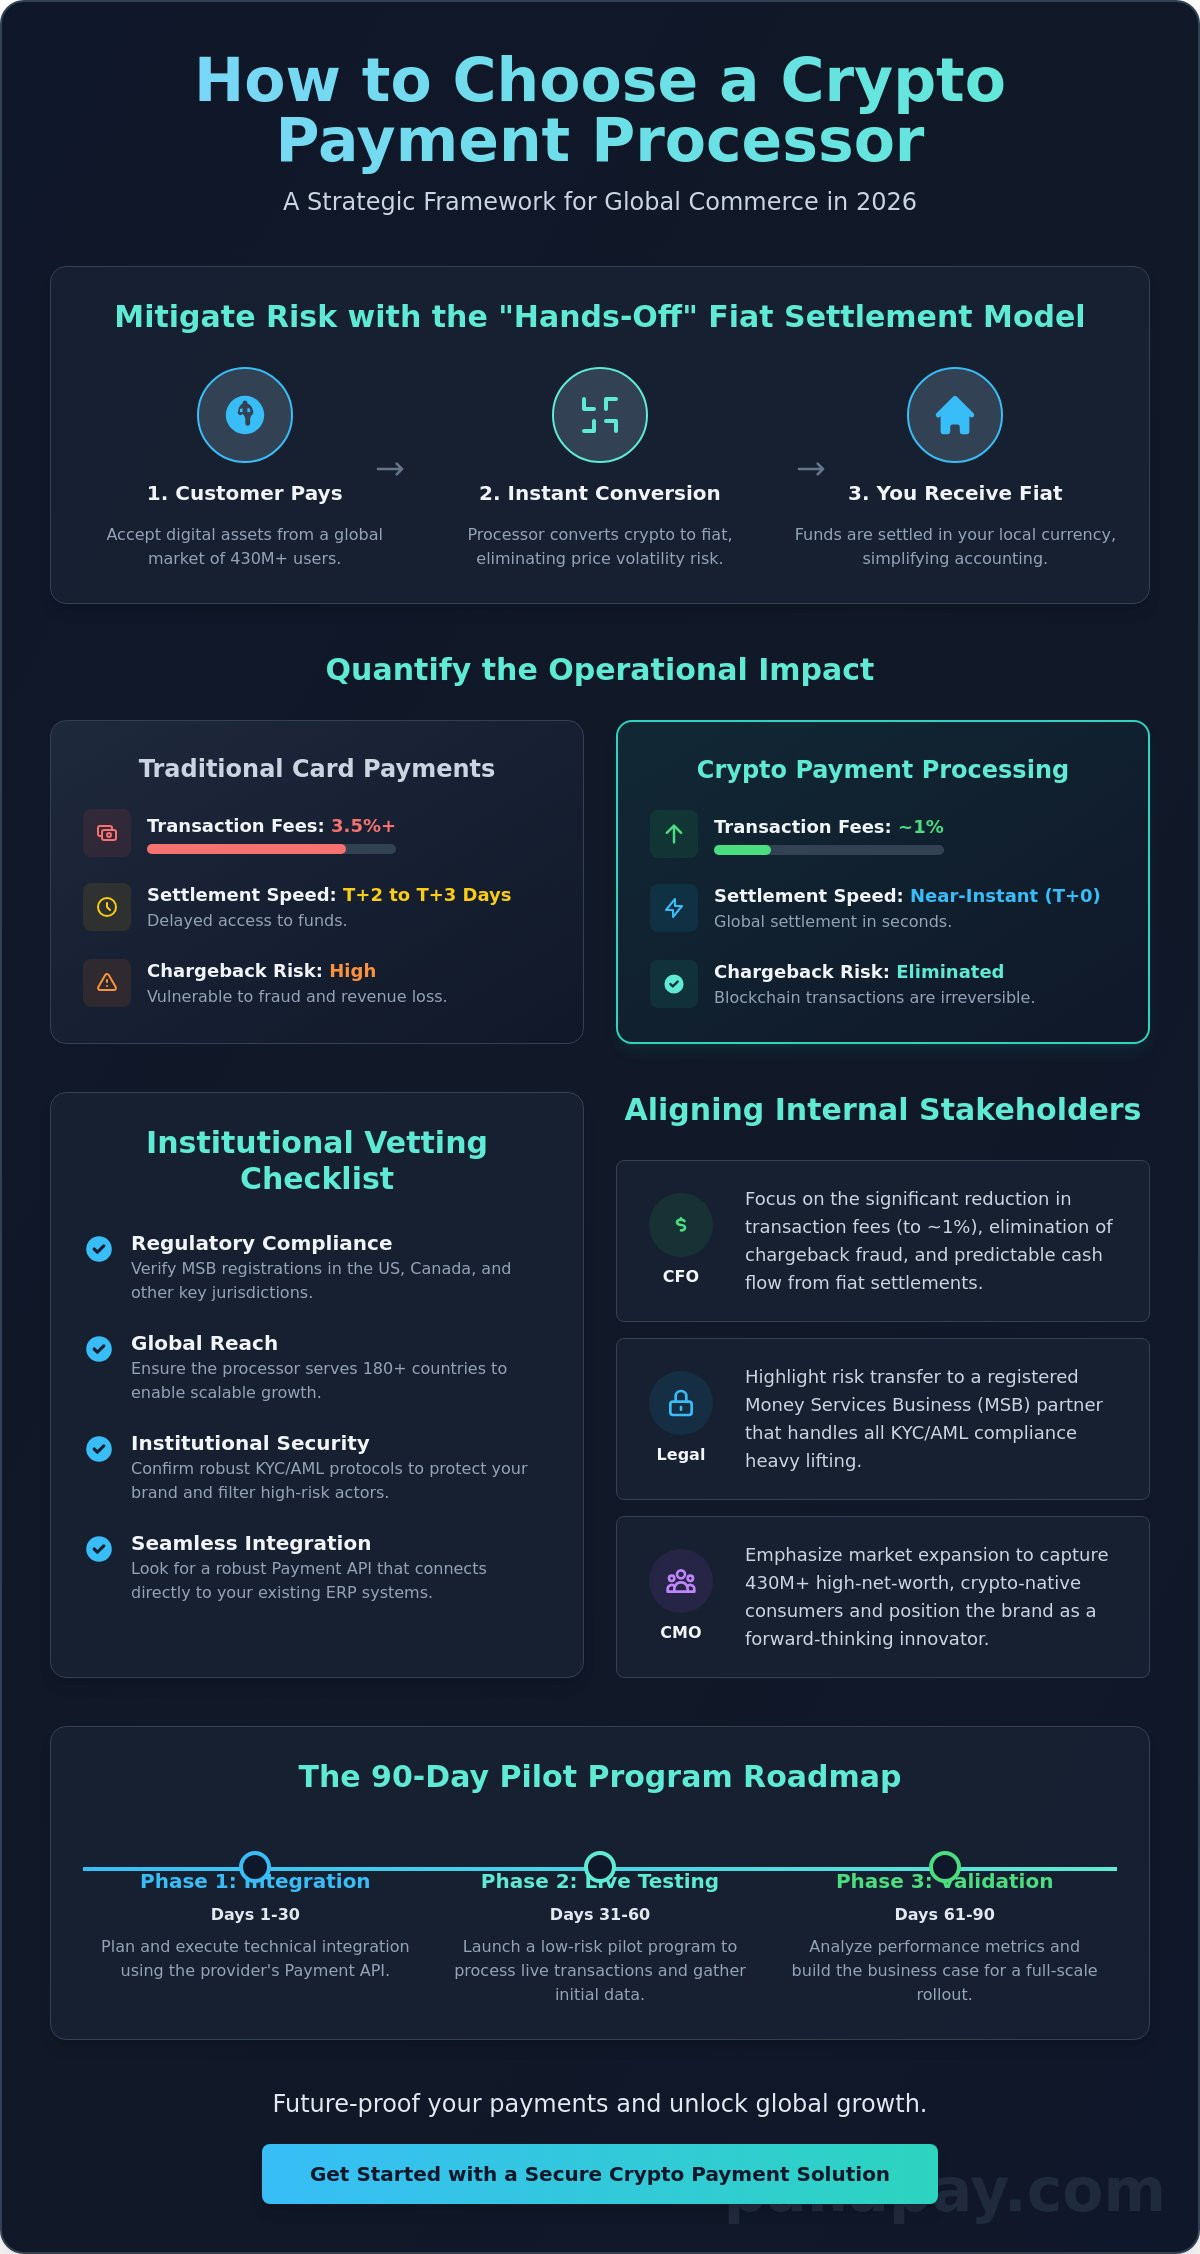
    • Identify how to align internal decision-makers by presenting the “hands-off” settlement model that eliminates price volatility risks for the organization.
    • Master the criteria for how to choose a crypto payment processor by verifying institutional-grade security and MSB registrations across major global jurisdictions.
    • Quantify the operational impact of switching to digital asset processing, including a significant reduction in transaction fees and achieving near-instant T+0 global settlement.
    • Streamline your technical transition using a robust Payment API that integrates directly with existing ERP systems for a frictionless operational flow.
    • Design a structured 90-day pilot program to validate performance metrics and transition from theoretical planning to live, low-risk commercial reality.

    Defining the Strategic Need: Stakeholder Mapping and the “Hands-Off” Model

    By 2026, digital assets have transitioned from speculative investments into a critical layer of the global financial infrastructure. For an enterprise, the decision to integrate these assets isn’t about joining a trend; it’s about optimizing the settlement layer of the business. Understanding how to choose a crypto payment processor requires a shift in perspective. You aren’t just looking for a technical plug-in. You’re selecting a strategic partner that functions as a modern payment service provider, bridging the gap between blockchain innovation and institutional requirements.

    The most successful implementations in 2026 utilize the “Hands-Off” model. This approach allows your business to capture the benefits of decentralized finance without the volatility risks. You accept digital assets from global customers, but your internal treasury never touches the tokens. Instead, the processor facilitates an immediate conversion, ensuring your books remain denominated in traditional currency. This eliminates the need for complex digital asset accounting while still accessing a global market of over 430 million crypto users. It’s a professional bridge that connects established practices with modern advancements.

    The Role of Fiat Settlement in Risk Mitigation

    Institutional stability relies on predictable cash flow. A robust fiat settlement system acts as the essential bridge between blockchain speed and banking stability. This approach simplifies tax reporting because every transaction has a clear fiat value at the moment of sale. It fits perfectly into standard accounting workflows, removing the hurdle of fluctuating balance sheets that often stalls executive approval. By receiving local currency directly, you maintain financial reliability while offering your customers the cutting-edge utility they expect.

    Tailoring the Message for Each Stakeholder

    Securing internal buy-in requires speaking the language of each department. The CFO needs to see how crypto reduces cross-border friction. Traditional international card fees often exceed 3.5%, but crypto processing typically sits near 1%. Additionally, the elimination of chargeback fraud provides a direct boost to the bottom line. Mastering how to choose a crypto payment processor means identifying a partner that satisfies these diverse departmental needs simultaneously.

    Your Legal team will focus on risk transfer. They want a partner that is a registered Money Services Business (MSB) to handle the heavy lifting of compliance. Meanwhile, the CMO will be interested in market expansion. Accepting crypto allows the brand to capture high-net-worth, crypto-native consumers who prioritize privacy and speed. By framing the choice as a multi-departmental win, you transform a technical request into a strategic business case that drives long-term growth.

    Vetting Compliance and Security: The Institutional Checklist

    Institutional trust is built on a foundation of rigorous regulatory adherence and technical resilience. When evaluating how to choose a crypto payment processor, the first point of verification must be the provider’s legal standing in key financial markets. A reputable partner should hold Money Services Business (MSB) registrations in major jurisdictions, specifically the United States and Canada. These registrations signify that the entity operates under the supervision of federal financial intelligence units, providing a necessary layer of accountability for your legal department.

    A global footprint is equally vital for modern commerce. A processor capable of serving 180+ countries ensures that your business can scale without encountering regional payment silos. This expansive reach must be paired with institutional-grade KYC (Know Your Customer) and AML (Anti-Money Laundering) protocols. These systems don’t just satisfy regulators; they protect your brand by filtering out high-risk actors before they interact with your ecosystem. Blockchain transparency actually enhances these efforts, as it allows for real-time tracking of asset provenance in ways traditional banking cannot match.

    Regulatory Compliance as a Corporate Shield

    Operating within a regulated framework transforms compliance from a hurdle into a competitive advantage. A processor that manages the complexities of global financial laws effectively offloads the regulatory burden from your internal teams. By partnering with a registered MSB, you ensure that every transaction adheres to the latest global standards. Blockchain transparency facilitates a new era of accountability where immutable ledgers provide definitive proof of funds and transaction history for auditing purposes.

    Institutional Security Standards

    Technical resilience is the second pillar of the vetting process. You should look for providers that prioritize advanced crypto security measures such as multi-signature authorization and cold storage for asset protection. Unlike traditional payment systems that rely on vulnerable centralized databases, blockchain utilizes cryptographic immutability to secure transaction data. Implementing a reliable Crypto Payment Gateway allows you to automate these security checks seamlessly. To assess a provider’s technical strength, use this essential checklist:

    • Proven Longevity: Does the provider have a documented history in the fintech sector dating back to at least 2018?
    • Infrastructure: Are assets kept in air-gapped cold storage rather than hot wallets?
    • Redundancy: Does the system feature multi-signature protocols to prevent single points of failure?
    • Global Reach: Can the provider facilitate transactions and settlements across 180+ countries?

    Choosing a partner with a long-standing reputation in the industry ensures that your transition to digital payments is secure and sustainable. Assessing these factors carefully is the definitive way to understand how to choose a crypto payment processor that will serve as a reliable strategic facilitator for your organization’s growth.

    Quantifying the Value Proposition: Fees, Speed, and Global Reach

    Selecting a partner isn’t just a technical hurdle; it’s a fiscal optimization strategy. When you evaluate how to choose a crypto payment processor, the most immediate metric is the impact on your bottom line. Traditional international credit card transactions often carry fees exceeding 3.5% once cross-border surcharges and currency conversion costs are tallied. In contrast, crypto processing fees typically hover around 1%. For high-ticket ecommerce operations, this 2.5% delta translates directly into preserved margins and increased competitive agility.

    The total cost of ownership (TCO) extends beyond the transaction fee. A sophisticated partner eliminates the hidden costs of traditional finance, such as setup delays and recurring maintenance charges for legacy hardware. By adopting an integrated digital infrastructure, you replace fragmented payment silos with a unified flow. This efficiency is a core component of the “Hands-Off” model discussed earlier, where the complexity of the background process is handled entirely by the provider, leaving you with clean, predictable fiat results.

    The Financial Impact of Instant Settlement

    Institutional liquidity depends on the velocity of capital. While traditional systems rely on the multi-day SWIFT cycle, crypto enables a “T+0” reality. This means funds are available for operational use almost immediately after a transaction is confirmed. Immediate fund availability provides a significant working capital advantage, allowing businesses to reinvest capital faster than ever before. To protect against market fluctuations, a professional processor facilitates instant conversion to stable currencies like USD or EUR, ensuring that the value captured at the point of sale is the exact value that hits your account.

    Payment Method Settlement Cycle Standard Fees
    International Credit Cards 2 to 7 Business Days 3.5% or higher
    Bank Wires (SWIFT) 1 to 5 Business Days Variable + Flat Fees
    Crypto Payment Processor Instant (T+0) Approximately 1%

    Unlocking New Global Markets

    Global commerce is shifting toward regions where digital assets are a primary payment method. For retail stores, accepting crypto is a powerful tool to attract international travelers who prefer the security and ease of digital wallets over carrying physical currency. This reduction in friction is equally transformative for cross-border B2B transactions. Knowing how to choose a crypto payment processor that prioritizes speed and global reach allows your business to bypass the bottlenecks of traditional banking, positioning you as a forward-thinking strategic partner in the inevitable global evolution of finance.

    How to Choose a Crypto Payment Processor: A 2026 Stakeholder Guide

    The Implementation Roadmap: Integration and Operational Flow

    Transitioning from a strategic framework to operational reality requires a structured, multi-phase approach. Knowing how to choose a crypto payment processor isn’t just about the initial sign-up; it’s about evaluating how the technology will live within your current ecosystem. A successful rollout prioritizes technical compatibility and internal readiness to ensure that digital asset acceptance becomes a standard, effortless business operation. By following a logical progression, you can mitigate technical risks while maximizing the efficiency of your new payment layer.

    • Step 1: Selection of a Technical Partner. Focus on providers offering a robust Payment API that supports high-volume throughput and secure endpoints.
    • Step 2: Technical Integration. Connect the processor to your existing ERP or shopping cart systems to automate the flow of transaction data.
    • Step 3: Internal Team Training. Educate finance and accounting departments on using the merchant dashboard for real-time reporting and reconciliation.
    • Step 4: Infrastructure Deployment. For brick-and-mortar locations, deploy a physical Crypto POS Machine to facilitate in-person digital asset payments.
    • Step 5: Pilot Launch. Initiate a controlled 90-day pilot program to gather performance data and refine operational workflows before a full-scale launch.

    Seamless API and POS Integration

    Modern crypto payment gateways are designed for plug-and-play efficiency, allowing for a “hands-off” implementation with minimal IT overhead. This streamlined architecture ensures that your technical team can focus on growth rather than troubleshooting complex background processes. When evaluating partners, prioritize those that offer comprehensive documentation and reliable technical support to maintain constant uptime for your global operations. A professional bridge between legacy systems and blockchain technology should feel frictionless and secure from the first transaction.

    Reporting and Reconciliation

    Institutional reliability is maintained through clear visibility into every transaction. A critical component of how to choose a crypto payment processor is assessing the reporting capabilities that bridge blockchain data with traditional ledgers. Advanced merchant dashboards simplify the tracking of digital asset sales by providing a unified view of your global revenue. These systems facilitate the automated generation of tax-ready reports, denominated in your preferred fiat currency, which aligns perfectly with standard accounting practices. This centralized interface allows management to oversee multiple store locations or ecommerce channels simultaneously, ensuring total operational control. To begin your integration, explore our API for crypto payments and see how it can accelerate your progress.

    Proposing the Pilot: Moving from Theory to Operational Reality

    The final stage in mastering how to choose a crypto payment processor involves transitioning from theoretical research to a controlled operational environment. A structured 90-day pilot program is the most effective way to minimize perceived organizational risk while gathering primary data. This timeframe allows your finance team to complete three full monthly reconciliation cycles, providing a clear window into the efficiency of the “Hands-Off” settlement model. By limiting the initial scope to a specific ecommerce channel or a select group of retail locations, you can validate the technology without overextending internal resources.

    A pilot program is more than a technical test; it is a strategic R&D investment in the future of your global financial infrastructure. It provides the empirical evidence needed to satisfy the last remaining concerns of your stakeholders. If the results align with your projections, you have a documented roadmap for a full-scale rollout. If adjustments are required, the modular nature of modern APIs allows you to refine the integration or revert to legacy systems without disrupting your core business operations. This reversibility is a key component of institutional-grade risk management.

    Setting Realistic KPIs for Stakeholders

    Success in the early stages should be measured through operational efficiency and error reduction rather than just raw transaction volume. You should track the exact fee savings achieved by bypassing traditional card networks, alongside the reduction in chargeback-related administrative costs. Quantitative metrics are vital, but qualitative feedback is equally important. Gathering insights from your first crypto-native customers can reveal a significant “first-mover” brand advantage in your sector. This data demonstrates to the CMO and CFO that the business is successfully capturing a high-growth, high-net-worth demographic that prioritizes speed and security.

    The Final Pitch: Why 2026 is the Inflection Point

    The global payments market is no longer waiting for crypto to mature; the infrastructure is already institutional-grade. In 2026, the greatest risk is no longer the volatility of the asset, but the competitive risk of being the last to adopt a more efficient settlement layer. Businesses that fail to integrate digital assets face higher overhead and slower capital velocity than their forward-thinking peers. The bridge approach we have outlined is sophisticated, regulated, and specifically designed to mitigate traditional risks. It is the definitive path for connecting established practices with the inevitable global evolution of commerce.

    The most successful implementations are those built on a foundation of expert guidance and reliable technology. You don’t have to build this business case alone. To ensure your pilot program is optimized for both security and growth, consult with a Pallapay specialist to build your custom business case and take the first step toward a more efficient financial future.

    Securing Your Position in the Future of Global Commerce

    The decision to integrate digital assets marks a transition from traditional limitations to global scalability. By aligning your stakeholders through a risk-mitigated “Hands-Off” model and vetting partners against strict institutional standards, you ensure that innovation serves your bottom line. The roadmap we’ve established moves beyond technical integration to focus on long-term financial stability and market expansion. Mastering how to choose a crypto payment processor is the definitive step in transforming your payment infrastructure into a competitive advantage for 2026 and beyond.

    As an institutional partner since 2018, we provide the stability and reach required for enterprise-level growth. Our ecosystem is MSB registered in the USA and Canada, supporting a global presence across 180+ countries. You’re now ready to move forward with the confidence that your background processes are handled by a proven industry leader. Explore Institutional Fiat Settlement Solutions to begin your transition today. Your organization is well-positioned to lead the next evolution of commerce.

    Frequently Asked Questions

    How do I explain crypto price volatility to my CFO?

    Explain that price volatility is entirely avoided by using a processor that facilitates instant conversion to fiat. The merchant receives the exact local currency value of the sale at the moment of the transaction. This ensures that your internal treasury never interacts with fluctuating asset prices. It’s a strategic utility that provides the speed of blockchain with the stability of the traditional banking system.

    Is it legal for a regulated business to accept cryptocurrency payments?

    Accepting digital assets is entirely legal for regulated businesses that partner with licensed Money Services Businesses. These processors manage the complex regulatory requirements, including KYC and AML protocols, on your behalf. You should verify that your provider holds valid registrations in jurisdictions like the United States or Canada. This partnership ensures your operations remain compliant with global financial standards while expanding your reach.

    Do we need to hold cryptocurrency on our company balance sheet?

    You don’t need to hold any cryptocurrency on your balance sheet if you opt for a fiat-settlement model. The processor handles the digital asset on the backend and settles the transaction in your preferred currency, such as USD or EUR. This keeps your accounting processes standard and familiar, allowing for seamless use alongside specialized tools like AIA G702 G703 software for construction billing. It’s an efficient way to capture new revenue without changing your fundamental corporate treasury policies.

    How long does the technical integration of a crypto gateway typically take?

    Most technical integrations for crypto gateways are completed within a few business days using modern, plug-and-play APIs. The process is designed to be efficient, requiring minimal intervention from your IT department. Learning how to choose a crypto payment processor with comprehensive documentation is the best way to ensure a fast rollout. This allows your business to move quickly from a strategic decision to live operations.

    What are the main security risks for corporate stakeholders to consider?

    The most critical risks involve the security of the gateway and the reliability of the settlement partner. Stakeholders should prioritize providers that utilize multi-signature authorization and air-gapped cold storage for all assets. Because blockchain transactions are final and immutable, they eliminate the risk of chargeback fraud that plagues traditional credit cards. A vetted partner with a long history in fintech provides the necessary institutional-grade protection.

    How do crypto processing fees compare to traditional credit card merchant fees?

    Crypto processing fees are substantially lower than traditional merchant fees, typically sitting at approximately 1%. In contrast, international credit card transactions often cost 3.5% or more when factoring in cross-border surcharges. This significant delta is a core part of the value proposition for businesses researching how to choose a crypto payment processor. Lowering these overheads directly improves your operational margins and capital efficiency.

    Can we receive settlements in our local fiat currency immediately?

    You can receive settlements in your local fiat currency almost immediately through a T+0 settlement cycle. This is a major improvement over the standard multi-day SWIFT cycle found in traditional banking. Funds are converted and settled into your account, providing a clear advantage for working capital management. It ensures that your liquidity is never trapped in the settlement process, allowing for faster reinvestment and global growth.

    What happens if a stakeholder is fundamentally opposed to digital assets?

    Position the integration as a strategic tool for cost reduction and global market expansion rather than a speculative investment. Emphasize that the “Hands-Off” model ensures the company never touches the digital assets directly. By focusing on the data from a low-risk pilot program, you can demonstrate tangible improvements in transaction speed and fee savings. This shifts the focus from the asset’s reputation to the technology’s institutional utility.

    Disclaimer

    The information provided on this website and blog is for general informational and educational purposes only and does not constitute financial, investment, legal, tax, or other professional advice.
    Cryptocurrency and digital asset services may be subject to regulatory restrictions in certain jurisdictions. Users are solely responsible for ensuring compliance with applicable local laws and regulations before using any products or services mentioned on this website.
    PallaPay does not guarantee the accuracy, completeness, or timeliness of any information published and accepts no liability for any loss or damages arising from reliance on the content. Any opinions expressed are those of the respective authors and may change without notice.
    Certain services, features, or products referenced may be provided through third-party partners, licensed entities, or affiliated service providers subject to separate terms and regulatory approvals. Availability of services may vary by country or region.
    This website may contain references to digital assets, virtual currencies, or blockchain-related services that are not available to residents of certain jurisdictions, including where prohibited by law. Nothing on this website constitutes an offer, solicitation, or recommendation to buy or sell any financial instrument or virtual asset.
  • Overcoming Common Objections to Accepting Crypto Payments: A 2026 Merchant Guide

    Overcoming Common Objections to Accepting Crypto Payments: A 2026 Merchant Guide

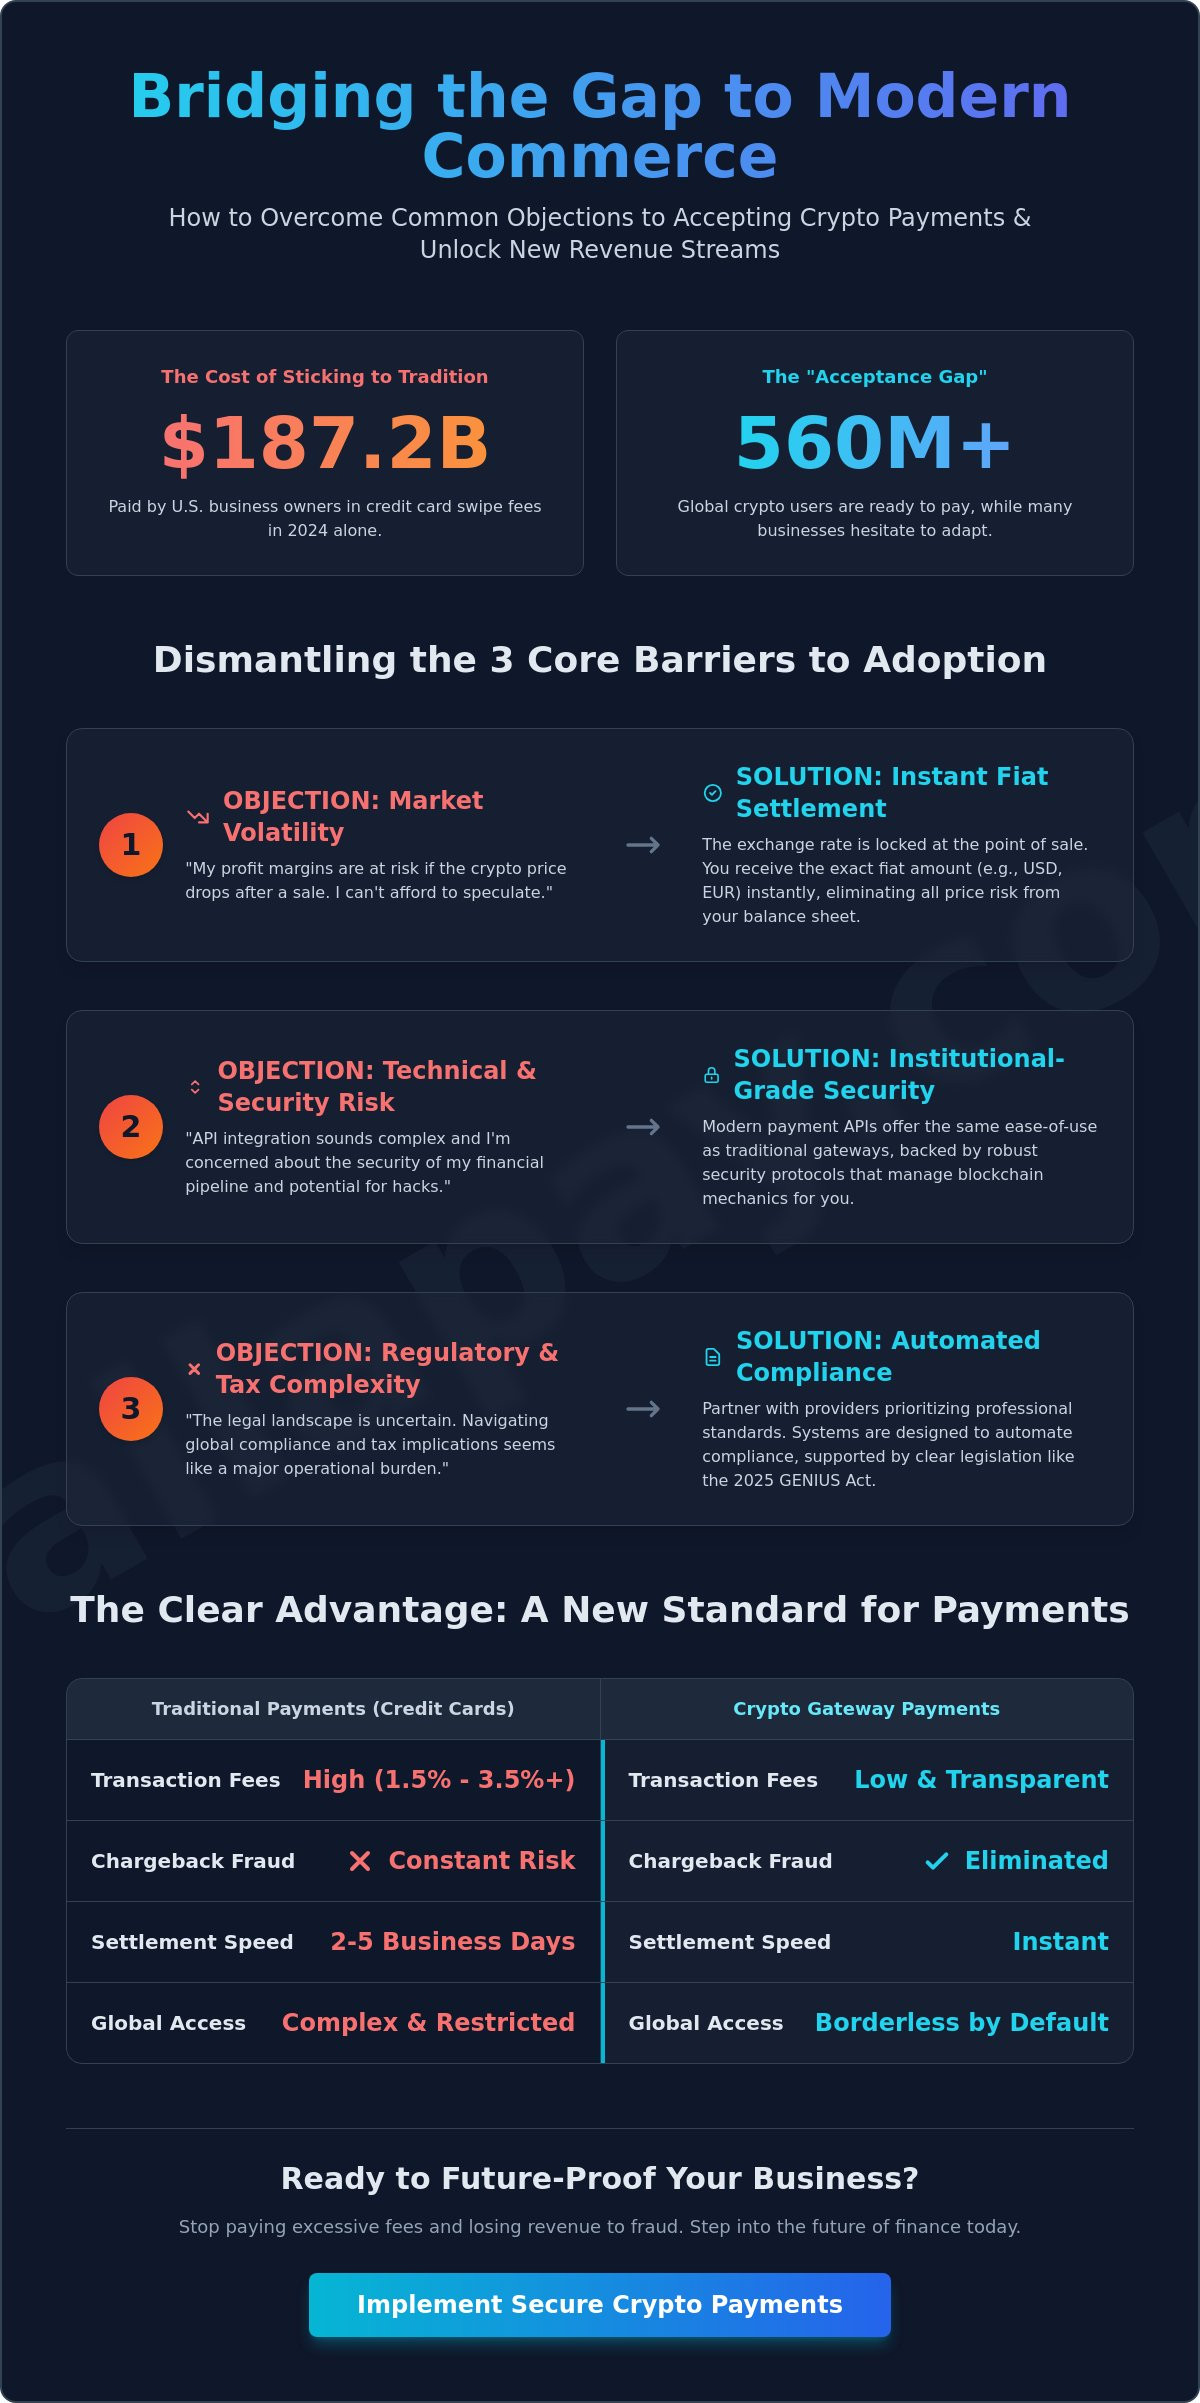
    U.S. business owners paid a staggering $187.2 billion in credit card swipe fees in 2024, yet many still hesitate to adopt more efficient digital alternatives. You likely feel that the traditional financial system is expensive; however, the common objections to accepting crypto payments, such as price volatility and regulatory uncertainty, often stall progress. It’s natural to prioritize the stability of your margins and the technical security of your operations above all else.

    This guide will demonstrate how modern financial technology has matured to dismantle these barriers, transforming previous risks into measurable competitive advantages. You’ll discover how to leverage a crypto payment gateway to receive fiat currency instantly, ensuring your bottom line remains protected from market fluctuations. We provide a clear framework for mitigating risks through institutional-grade security measures and explain how recent legislation, like the 2025 GENIUS Act, provides the regulatory clarity your business needs to grow. By the end of this article, you’ll understand how to bridge the gap between established commerce and the inevitable global evolution of finance.

    Key Takeaways

    • Eliminate price risk by utilizing instant fiat settlement, ensuring your profit margins are preserved regardless of market movement.
    • Address common objections to accepting crypto payments by understanding how modern API integrations provide the same ease of use as traditional credit card gateways.
    • Protect your revenue from fraudulent chargebacks by leveraging the inherent irreversibility of blockchain transactions to secure every sale.
    • Navigate global compliance with confidence by partnering with providers that prioritize professional regulatory standards and secure offramp procedures.
    • Discover how a comprehensive ecosystem allows you to convert crypto to USD or EUR instantly, bridging the gap between digital assets and traditional commerce.

    Why Businesses Still Hesitate to Adopt Cryptocurrency Payments

    The “Acceptance Gap” remains a visible friction point in modern commerce. While consumer interest in digital assets has surged to over 560 million global users, operational hesitation still prevents many enterprise leaders from fully integrating these systems. By 2026, cryptocurrency has transitioned from a speculative experiment into a standard asset class. However, a psychological barrier persists among traditional finance leaders who often view decentralized systems with caution. They fear a lack of institutional oversight or a loss of control over their financial pipelines.

    Modern financial technology acts as a supportive facilitator in this environment. It doesn’t ask businesses to abandon their established practices; instead, it provides a professional bridge that connects traditional reliability with modern efficiency. By 2026, roughly 19% of U.S. small businesses have already adopted these tools to lower costs and reach new demographics. The goal is to turn technical complexity into a background process that feels like a standard business operation.

    The Evolution of Merchant Crypto Adoption

    Merchant services have moved far beyond the early days of direct peer-to-peer transfers. In the past, “do-it-yourself” crypto acceptance required businesses to manage private keys and manual conversions, which led to many of today’s common objections to accepting crypto payments. Today, sophisticated gateway ecosystems have replaced those high-friction methods. Institutional-grade infrastructure now handles the underlying blockchain mechanics, allowing merchants to focus on their core growth while the technology manages the transaction flow in the background.

    Identifying the Core Categories of Resistance

    Resistance to adoption generally falls into three distinct categories that require specific technological answers. Understanding these risks is the first step toward mitigating them effectively:

    • Financial Risk: Concerns regarding market volatility and the immediate liquidity of digital assets.
    • Operational Risk: Anxiety over technical integration, security protocols, and the potential for hacking.
    • Compliance Risk: Navigating Regulatory Compliance and Tax Complexity across different jurisdictions.

    By utilizing a professional payment API, businesses can bypass these hurdles. These systems are designed to automate compliance and security, ensuring that your transition into digital finance is both secure and legally sound. When you implement a structured fiat settlement process, the perceived risks of the crypto market effectively disappear from your balance sheet.

    Objection 1: Market Volatility and Financial Stability Risks

    Market volatility is frequently cited as the most significant hurdle for merchants. The fear of losing profit margin between the moment of a transaction and the eventual bank deposit is understandable. This concern remains one of the most common objections to accepting crypto payments, but it’s based on an outdated understanding of how modern payment gateways function. By 2026, the technology has evolved to remove this risk entirely through automated background processes. Businesses no longer need to speculate on market prices to participate in the digital economy.

    Modern financial infrastructure acts as a protective shield for your margins. When a customer initiates a payment, the exchange rate is captured in real time. This ensures that the value you see at the point of sale is the value that arrives in your account. By removing the exposure to market swings, businesses can focus on growth rather than monitoring price charts. If you’re looking to stabilize your revenue, you can convert crypto to USD instantly to maintain your financial stability.

    How Fiat Settlement Eliminates Price Risk

    The primary solution to volatility is a robust fiat settlement system. This mechanism locks in the exchange rate at the exact moment a customer clicks “pay.” Even if the underlying asset’s value fluctuates seconds later, the merchant receives the precise fiat amount requested. This process transitions digital assets to fiat currency automatically, ensuring that businesses never have to ‘hold’ volatile assets on their balance sheet. It effectively treats a Bitcoin or Ethereum transaction with the same financial stability as a standard credit card payment.

    The Role of Stablecoins in 2026 Commerce

    Stablecoins like USDT have become a preferred settlement layer for international B2B transactions. These assets offer the speed of blockchain technology without the price fluctuations of traditional cryptocurrencies. While traditional banking cycles often take 3 to 5 business days for cross-border settlement, digital asset rails provide near-instant movement of value. This efficiency reduces cross-border transaction fees and improves cash flow management. For businesses requiring physical operational flexibility, services to sell crypto to bank accounts or exchange USDT for cash provide the liquidity needed to meet immediate obligations.

    Strategic partners now offer comprehensive ecosystems that handle these complex technical conversions. This allows you to accept a wide variety of assets while settling in the currency that best suits your operational needs. By utilizing these professional tools, you can turn a perceived financial risk into a distinct operational advantage.

    Overcoming Common Objections to Accepting Crypto Payments: A 2026 Merchant Guide

    Objection 2: Regulatory Compliance and Tax Complexity

    Regulatory uncertainty often manifests as a “Regulatory Ghost” in the boardroom. Finance directors frequently worry that adopting digital assets will lead to unintentional non-compliance with anti-money laundering (AML) protocols or complex tax audits. These fears represent significant common objections to accepting crypto payments. However, the regulatory landscape of 2026 is far more defined than in previous years. The enactment of the GENIUS Act in July 2025 provided a comprehensive framework for stablecoins, while the CLARITY Act of 2026 defined most digital assets as commodities. These legislative milestones have replaced ambiguity with a clear roadmap for institutional adoption.

    By choosing a partner with formal Money Services Business (MSB) registration, merchants effectively transfer the bulk of the compliance burden to the provider. This professional bridge ensures that every transaction is screened and recorded according to global standards. It’s a shift from a “do-it-yourself” compliance model to a managed service that scales with your business. This level of institutional financial reliability is essential for any merchant aiming to capture a share of the 560 million global crypto users safely.

    Partnering with Regulated MSB Entities

    MSB registration is the non-negotiable gold standard for merchant security in 2026. When you partner with a regulated entity in regions like the US or Canada, you gain access to institutional-grade financial reliability. The gateway handles the complex Know Your Customer (KYC) and AML checks automatically. This process protects your business from high-risk actors while maintaining a frictionless experience for legitimate customers. It’s a strategic move that transforms a potential legal liability into a secure, regulated operational flow. A regulated partner acts as a supportive facilitator, allowing your leadership team to focus on strategic growth rather than navigating the intricacies of federal laws.

    Automating Tax and Accounting Workflows

    Manual bookkeeping is no longer a requirement for digital asset commerce. Modern gateways generate automated, tax-ready reporting that simplifies the audit trail for your internal teams. These systems track capital gains at the moment of transaction, removing the need for manual ledger entries or complex year-end reconciliations. By utilizing specialized e-commerce industry solutions, you can integrate sales data directly into your existing accounting software. These automated reporting features are essential for maintaining a clean audit trail across 180+ countries. It ensures that your tax filings are accurate and defensible, regardless of the volume of international sales.

    Objection 3: Technical Integration and Security Concerns

    Technical complexity and perceived security vulnerabilities are often the final hurdles for merchants. Many business leaders believe that integrating blockchain technology requires a specialized internal team or a complete overhaul of their existing stack. These technical anxieties are among the most persistent common objections to accepting crypto payments. In reality, the 2026 integration landscape has achieved parity with traditional payment systems. Modern solutions are designed to be plug-and-play, ensuring that the underlying mechanics remain invisible to both the merchant and the end consumer.

    Security is no longer a matter of manual oversight but of institutional-grade automation. Protecting the digital perimeter involves multi-signature wallets and advanced encryption protocols that far exceed the security standards of traditional magnetic stripe or chip-and-pin systems. By utilizing a professional payment API, you can secure your transaction data without needing to understand the complexities of cryptographic hashing. This technology creates a secure environment where digital assets move with the same reliability as fiat currency, protecting your business from the erratic nature of the early crypto era.

    Seamless API and POS Integration

    Implementing these solutions follows a logical, step-by-step progression that mirrors standard payment setup. First, select a gateway with a robust API to handle the background logic and currency conversions. Second, configure your checkout experience to ensure zero-friction user journeys, allowing customers to pay with their preferred assets in seconds. For physical storefronts, deploying dedicated crypto POS machines allows for real-time processing in retail store environments. This hardware-software synergy ensures that whether your customer is online or in-person, the transaction is handled with absolute trust and speed. Modern API documentation is now so streamlined that integration times have dropped from weeks to just a few days of configuration.

    Turning Irreversibility into a Security Feature

    Traditional finance often highlights transaction irreversibility as a risk, yet for merchants, it’s a significant security upgrade. Credit card chargeback fraud remains a hidden cost that drains billions from global commerce annually. Crypto payments protect your revenue from “friendly fraud” because once a transaction is verified on the blockchain, it cannot be reversed by the customer. This transparency builds a different kind of trust. Every sale is final and verifiable, eliminating the anxiety of unauthorized reversals weeks after a product has shipped. By removing the threat of chargebacks, you can protect your margins and simplify your dispute management processes.

    If you’re ready to secure your revenue stream, you can integrate a professional payment API today to eliminate chargeback risks and streamline your global operations.

    Strategic Solutions: How Pallapay Eliminates Merchant Friction

    Pallapay serves as the professional bridge between traditional commerce and the digital future. While previous sections have dismantled the common objections to accepting crypto payments through technical and regulatory evidence, the practical execution requires a unified ecosystem. A fragmented approach often leads to operational friction; however, an integrated platform ensures that every transaction remains efficient and secure. Pallapay provides this stability by combining institutional financial reliability with accessibility-focused tools that simplify the user experience. By 2026, over 560 million global users are active in the digital asset space, and having a strategic partner allows you to capture this market without technical debt.

    Speed is a definitive competitive edge in modern finance. The ability to convert crypto to fiat instantly ensures that your business maintains the liquidity required for daily operations. Whether you need to settle in USD, EUR, GBP, or CNY, the infrastructure is designed to handle these conversions in real time. This global reach extends to over 180 countries, providing a secure perimeter for international expansion. You don’t need to be a blockchain expert to succeed; you simply need a facilitator that handles the background complexity while you focus on your core growth objectives.

    The Pallapay Ecosystem Advantage

    The Pallapay ecosystem is built for high-performance commerce. It combines advanced crypto security with high-volume OTC capabilities, allowing merchants to move significant assets without market slippage. Global desks provide professional support for complex transactions, ensuring that your financial operations remain grounded in practical commerce. A unique benefit of this ecosystem is the Pallapay Mastercard. This tool enables you to spend your crypto earnings instantly at any point of sale, bypassing the multi-day delays typical of traditional banking systems. It turns your digital revenue into a liquid resource for immediate reinvestment or operational expenses.

    Getting Started: The Path to Crypto Readiness

    Transitioning your business is a logical, step-by-step progression. You can begin by setting up a merchant account and selecting the integration that suits your business model, such as an online gateway for ecommerce or a physical POS machine for retail. For businesses that require traditional bank settlement, the crypto off-ramp provides a streamlined path for transfers to your corporate accounts. This ensures that you can always access your funds in the currency of your choice, including AED, INR, or EUR. The common objections to accepting crypto payments are solved through this comprehensive suite of services. Join the evolution of global commerce today by partnering with a trusted strategic facilitator and secure your place in the future of finance.

    Securing Your Competitive Advantage in the Global Economy

    The landscape of 2026 offers unparalleled opportunities for businesses to move beyond traditional payment limitations. By addressing the common objections to accepting crypto payments through instant fiat settlement and regulated compliance, you can protect your margins while expanding your global reach. You’ve seen how modern technology transforms perceived risks into operational strengths. Institutional-grade security and automated tax reporting are no longer optional extras; they’re essential tools for any growth-oriented enterprise.

    As a regulated MSB in the USA and Canada, Pallapay provides the 2026-ready secure POS and API infrastructure needed to serve customers in over 180 countries. This comprehensive ecosystem ensures that your transition is both efficient and legally sound. It’s time to scale your business with Pallapay’s secure crypto payment gateway. Embracing these advancements positions your company at the forefront of financial innovation. The transition to digital finance is a standard business operation that empowers your brand to lead in an evolving global market. Your progress starts today.

    Frequently Asked Questions

    Is it legal for my business to accept cryptocurrency payments in 2026?

    Yes, it’s legal in many major economies, including the United States and Canada. The GENIUS Act of 2025 and the CLARITY Act of 2026 have established a clear regulatory framework for digital assets and stablecoins. By using a regulated Money Services Business (MSB), you ensure that your operations comply with federal standards, effectively removing the legal ambiguity that once characterized the industry.

    How do I protect my business from Bitcoin price volatility?

    You can protect your margins by utilizing instant fiat settlement services. This technology captures the exchange rate at the exact moment of the transaction, ensuring the value you receive isn’t affected by subsequent market swings. Many businesses choose to convert crypto to USD or EUR immediately. This process eliminates the financial risk of holding volatile assets on your balance sheet while allowing you to enjoy the benefits of digital commerce.

    Do I need to be a tech expert to integrate a crypto payment gateway?

    You don’t need specialized technical expertise to implement a modern crypto payment solution. Current API integrations and physical POS machines are designed for seamless, plug-and-play operation within your existing infrastructure. These systems handle the complex background mechanics of the blockchain, allowing your team to focus on standard business operations. Most merchants can complete the setup process in just a few days by following a logical configuration guide.

    What are the tax implications of accepting digital assets for services?

    Modern gateways simplify tax compliance by generating automated, tax-ready reporting for every transaction. These systems track capital gains and losses at the point of sale, which removes the need for manual ledger entries or complex year-end reconciliations. By addressing these common objections to accepting crypto payments through automation, you maintain a clean audit trail. This ensures that your accounting workflows remain efficient and accurate across different jurisdictions.

    Can I convert crypto payments directly into my local bank account?

    Yes, you can transfer your earnings directly to your local bank account. Professional off-ramp services allow you to sell crypto to bank accounts in multiple currencies, including USD, EUR, and GBP. This bridge between digital assets and traditional finance ensures you have immediate access to liquidity for your operational needs. The process is fast and secure, providing the same reliability as a standard international wire transfer but with improved settlement speeds.

    How do crypto transaction fees compare to traditional credit card processors?

    Cryptocurrency transaction fees are typically significantly lower than traditional credit card processing costs. While credit card swipe fees often range from 1.5% to 3.5%, digital asset gateways generally charge between 0.5% and 2%. For example, U.S. business owners paid $187.2 billion in swipe fees in 2024. Adopting crypto payments can lead to substantial cost savings, directly improving your profit margins on every international and domestic sale.

    What happens if a customer sends the wrong amount of crypto?

    The payment gateway handles payment discrepancies through automated reconciliation protocols. If a customer sends an incorrect amount, the system flags the transaction and provides a clear path for a refund or a top-up payment. This prevents manual bookkeeping errors and ensures your records remain precise. These automated systems are designed to resolve common objections to accepting crypto payments by providing a predictable, professional experience for both the merchant and the consumer.

    Is there a risk of my merchant account being hacked?

    Institutional-grade security measures effectively mitigate the risk of unauthorized access. Regulated providers utilize advanced encryption, multi-signature wallets, and cold storage to protect your assets and data. These protocols are far more robust than the security standards used in many traditional financial systems. By choosing a partner with a proven track record in digital asset security, you ensure that your merchant account remains protected against modern cyber threats.

    Disclaimer

    The information provided on this website and blog is for general informational and educational purposes only and does not constitute financial, investment, legal, tax, or other professional advice.
    Cryptocurrency and digital asset services may be subject to regulatory restrictions in certain jurisdictions. Users are solely responsible for ensuring compliance with applicable local laws and regulations before using any products or services mentioned on this website.
    PallaPay does not guarantee the accuracy, completeness, or timeliness of any information published and accepts no liability for any loss or damages arising from reliance on the content. Any opinions expressed are those of the respective authors and may change without notice.
    Certain services, features, or products referenced may be provided through third-party partners, licensed entities, or affiliated service providers subject to separate terms and regulatory approvals. Availability of services may vary by country or region.
    This website may contain references to digital assets, virtual currencies, or blockchain-related services that are not available to residents of certain jurisdictions, including where prohibited by law. Nothing on this website constitutes an offer, solicitation, or recommendation to buy or sell any financial instrument or virtual asset.
  • The Business Case for Accepting Crypto Payments in 2026: A Strategic Guide

    The Business Case for Accepting Crypto Payments in 2026: A Strategic Guide

    Did you know that stablecoin on-chain transfer volumes reached approximately $36 trillion by 2025, surpassing the total transaction volumes of legacy giants like Mastercard and American Express? You’ve likely felt the daily friction of traditional banking, where high cross-border fees and the persistent threat of chargeback fraud eat into your margins. Building a robust business case for accepting crypto payments is no longer about following a trend. It’s about securing a strategic advantage in a globalized economy that demands speed and absolute security.

    You deserve a financial infrastructure that works as fast as your business does. We’ll show you how integrating cryptocurrency payments drives revenue, eliminates chargeback fraud, and opens your doors to a high-net-worth audience of over 560 million global users. This guide provides a clear look at how modern payment gateways allow you to bypass slow settlement times and access global markets without currency hurdles. We’ll examine the operational shift toward instant fiat conversion and the regulatory frameworks that have turned digital assets into a reliable, institutional-grade tool for growth.

    Key Takeaways

    • Understand why legacy T+3 settlement cycles are no longer competitive and how to transition your operations toward real-time financial liquidity.
    • Build a compelling business case for accepting crypto payments by comparing standard credit card fees against the efficiency of high-performance blockchain rails.
    • Expand your reach into emerging global markets and connect with a high-net-worth customer base that values borderless, friction-free transactions.
    • Master the strategies for mitigating market volatility through instant fiat conversion and navigating the evolving 2026 regulatory landscape.
    • Explore the technical integration of sophisticated payment APIs and physical POS machines to unify your digital and in-person sales channels effortlessly.

    The Strategic Shift: Why Businesses Are Prioritizing Crypto in 2026

    By 2026, the global financial landscape has matured beyond the era of speculative volatility. Digital assets have transitioned from experimental novelties into essential utility-driven tools for modern commerce. This shift is driven by a fundamental breakdown in legacy banking infrastructure. Traditional T+3 settlement cycles, which keep merchant capital locked for days, are no longer viable in a high-velocity market. Businesses now demand real-time liquidity to maintain their competitive edge. In this environment, the borderless merchant has emerged, using decentralized technology to bypass the geographic and operational silos of traditional finance.

    Digital assets now serve as a sophisticated bridge between disparate fiat systems. Instead of navigating a web of intermediary banks and high cross-border fees, companies use blockchain rails to move value instantly across continents. To understand what is cryptocurrency in a 2026 context, one must look past the code and see a high-performance payment rail. It provides a standardized layer for value exchange that operates independently of local banking hours or clearinghouse delays.

    The Death of the “Wait-and-See” Approach

    Institutional adoption is no longer a future prediction; it’s a current reality. With global crypto users exceeding 560 million, the demographic of digital asset holders is too large to ignore. A 2026 market analysis shows that 85% of merchants now view these payments as a primary vehicle for reaching tech-savvy, high-net-worth customers. Staying on the sidelines creates a measurable competitive disadvantage. If your rivals offer the speed of blockchain confirmation while you remain tethered to legacy systems, you risk losing market share to more agile competitors. The business case for accepting crypto payments is fundamentally a transition from viewing payments as a cost-center to leveraging them as a strategic profit-driver.

    Stablecoins as the New Global Standard

    The primary driver of merchant adoption in 2026 isn’t Bitcoin’s price action but the utility of stablecoins. Assets like USDT and USDC have become the preferred choice for commercial transactions because they combine the stability of fiat with the technical advantages of blockchain. In 2025, stablecoins supported an annual on-chain transfer volume of approximately $36 trillion. This massive liquidity pool allows businesses to price goods in familiar denominations while benefiting from instant, irreversible transactions.

    Modern treasury management now relies on the ability to move in and out of positions without friction. By utilizing fiat settlement, companies can accept digital assets and receive their local currency almost immediately. This setup effectively eliminates the volatility argument. Merchants can enjoy the benefits of a global, 24-hour payment network without exposing their balance sheets to market fluctuations. It’s a secure, efficient, and highly scalable way to manage international revenue streams.

    Quantifying the ROI: Transaction Efficiency and Cost Reduction

    Measuring the financial impact of new technology requires a move beyond surface-level excitement. A strong business case for accepting crypto payments rests on the immediate reduction of operational overhead. Traditional merchant accounts often come with a complex web of fees that can range from 1.5% to 3.5% per transaction. In contrast, typical crypto payment gateways in 2026 operate with fees between 0.5% and 1%. For high-volume enterprises, this 2% delta represents a significant recovery of net profit that would otherwise be lost to legacy processing networks.

    The savings extend into the removal of hidden costs associated with traditional banking. Intermediary banks, currency conversion spreads, and mandatory holding periods often drain resources before funds ever reach a merchant’s account. By adopting digital asset rails, businesses can expand into international markets without the need for local entities or regional bank accounts. This borderless approach allows a company to capture global demand while maintaining a centralized, efficient treasury.

    The End of Chargeback Risk

    One of the most immediate benefits of blockchain technology is the elimination of chargeback fraud. Credit card systems are built on “pull” mechanics, where a customer or bank can reverse a transaction weeks after a service is rendered. This creates a massive financial liability, especially for e-commerce and high-ticket retail. Cryptocurrency operates on a “push” model. Once a transaction is confirmed on the ledger, it’s permanent. This immutability protects merchants from “friendly fraud” and allows firms to redirect their fraud prevention budgets toward active growth initiatives. It’s a fundamental shift that places financial control back into the hands of the business owner.

    Accelerating Cash Flow with Instant Settlement

    Liquidity is the lifeblood of any scaling operation. Legacy banking systems often operate on a T+3 settlement cycle, meaning funds are locked for three business days or more. In a fast-paced economy, this delay is a significant bottleneck. Real-time payment rails provide T+0 settlement, providing almost instant access to capital. By utilizing efficient crypto to bank transfers, businesses can move their digital revenue into traditional accounts without the multi-day delays typical of the SWIFT network.

    This speed enables rapid reinvestment into inventory, marketing, or payroll. Reconciliation also becomes more streamlined. Automated blockchain ledgers provide an immutable, transparent record of every transaction, reducing the administrative burden on accounting departments. For merchants looking to optimize their checkout flow, integrating a sophisticated payment API is the first step toward reclaiming lost margins and achieving true financial agility.

    Capturing New Markets: Borderless Commerce and Consumer Demand

    Accepting digital assets isn’t just a defensive move against transaction fees; it’s an offensive strategy to capture a share of the $3 trillion global crypto market cap. This capital represents a massive pool of liquid wealth that is increasingly seeking utility in the real-world economy. A central pillar of the business case for accepting crypto payments is the ability to reach unbanked and underbanked populations in emerging markets. These individuals may lack access to traditional credit cards or institutional banking, yet they often possess significant digital assets. By providing a gateway for these users, you open your business to entirely new demographics that were previously unreachable due to systemic financial barriers.

    The B2B sector is also witnessing a major transformation through large-scale international supplier payments. Instead of waiting days for a SWIFT transfer to clear, businesses are using stablecoins to settle high-value invoices in minutes. This speed reduces the counterparty risk inherent in long settlement windows and allows for more aggressive inventory management. To build deeper engagement, sophisticated brands are launching gift card and reward programs. These initiatives allow customers to convert their digital holdings into brand-specific credit, creating a closed-loop ecosystem that encourages repeat business and enhances customer retention.

    The Crypto-Native Consumer Profile

    By 2026, the profile of the crypto-native consumer has evolved into a high-net-worth segment with a distinct preference for efficiency. These users typically exhibit higher average order values (AOV) compared to traditional credit card users, often due to the lack of arbitrary spending limits on blockchain transactions. For the e-commerce sector, the priority is creating a frictionless checkout experience. This involves integrating payment flows that recognize the user’s wallet instantly, allowing for a secure, one-click confirmation. When you remove the friction of manual data entry and multi-step verification, conversion rates naturally climb.

    Global Expansion Without Geographic Friction

    The broader business case for accepting crypto payments extends into your ability to expand operations into 180+ countries without a complex web of local bank accounts. Cryptocurrency acts as a universal financial layer, allowing you to accept payments from anywhere in the world without suffering from currency conversion loss or regional banking delays. This is a strategic advantage for the hotel industry and luxury retail, where international guests often encounter issues with credit card authorizations or high foreign transaction fees. By offering a digital payment option, you provide a premium, white-glove experience that simplifies the “last mile” of the customer journey, ensuring that your global expansion remains unhindered by geographic borders.

    The Business Case for Accepting Crypto Payments in 2026: A Strategic Guide

    Mitigating Risk: Compliance, Security, and Volatility

    The most common objection to digital assets is market volatility, yet this concern is largely obsolete for the modern merchant. By 2026, the business case for accepting crypto payments is reinforced by the widespread availability of instant fiat conversion. This technological bridge ensures that the merchant receives the exact fiat amount at the moment of sale, regardless of subsequent market movements. By using a sophisticated fiat settlement process, businesses can lock in exchange rates immediately, effectively removing the “volatility myth” from their operational risk profile.

    Compliance is the second pillar of risk mitigation in the current landscape. Regulatory frameworks like MiCA in the European Union and the FSMA in the United Kingdom have established clear, enforceable rules for digital asset service providers. Working with a partner that adheres to these standards is essential for maintaining institutional financial reliability. Integrated gateway solutions now handle the heavy lifting of AML/KYC requirements, acting as a filter that protects the business from illicit actors while ensuring that every transaction meets global anti-money laundering standards.

    Institutional-Grade Security Standards

    Modern gateways handle private key management with institutional-grade rigor, removing the burden of technical custody from the merchant. This setup allows your team to focus on core operations while the underlying technology secures the assets. Multi-signature wallets have become the standard for corporate governance, requiring multiple authorizations for high-value transfers to prevent unauthorized access. Implementing crypto security best practices ensures that your digital treasury remains as secure as any traditional bank vault, providing a calm and stable environment for growth.

    Regulatory Peace of Mind

    Working with a regulated Money Services Business (MSB) in the US and Canada is non-negotiable for businesses that prioritize long-term stability. These entities provide the necessary oversight to ensure that your payment rails remain open and functional. Automated reporting tools now simplify the complexities of tax and compliance audits by providing a transparent, immutable record of every transaction. A crypto payment gateway serves as a compliance shield, protecting your operations from the shifting sands of global regulation and ensuring you remain on the right side of financial evolution. To secure your revenue streams and ensure absolute regulatory alignment, consider integrating a regulated settlement solution today.

    Implementation: Future-Proofing with the Pallapay Ecosystem

    Deploying a digital asset strategy requires a platform that bridges the gap between technical complexity and operational simplicity. The final pillar of the business case for accepting crypto payments is the ease of execution within a unified ecosystem. By using a sophisticated Payment API, you can connect your existing e-commerce storefront to global liquidity pools in a single integration. This setup allows your business to maintain its current checkout flow while adding a high-performance payment rail that settles in the currency of your choice.

    Managing global operations becomes effortless through a centralized merchant dashboard. This interface provides real-time visibility into every transaction, from the initial wallet confirmation to the final fiat deposit. The transition from registration to your first crypto-to-fiat settlement is designed to be a streamlined procedural flow. Once your account is verified, you can immediately begin accepting assets like USDT or Bitcoin, with the system handling all background conversions to ensure your balance sheet remains stable and predictable.

    The Omnichannel Advantage

    Modern commerce isn’t limited to a single screen. To achieve true market penetration, businesses must integrate digital payments into their physical retail stores. By deploying specialized hardware like Crypto POS machines, you can accept in-person payments with the same speed and security as your online sales. This hybrid approach enables mobile payments for field services and pop-up commerce, ensuring you never miss a revenue opportunity. Synchronizing online and offline digital asset accounting within one platform eliminates the administrative burden of manual reconciliation, allowing your finance team to focus on higher-value growth initiatives.

    Scaling with Professional OTC Services

    As your volume grows, your infrastructure must scale accordingly. Enterprise-level merchants often require specialized handling for high-value transactions to avoid market slippage and ensure deep liquidity. Utilizing a professional OTC crypto exchange provides the necessary environment for large-scale settlements without disrupting the broader market. This service allows for customized settlement schedules that match your specific business liquidity needs, whether you require daily transfers or weekly consolidations. By partnering with a strategic facilitator that offers dedicated global support, you ensure that your transition to modern financial rails is both secure and highly efficient.

    Securing Your Position in the Future of Global Commerce

    The evolution of digital finance has transformed payments from a background utility into a powerful driver of organizational growth. By eliminating the friction of legacy banking and capturing the demand of over 560 million global users, you’re not just adding a payment method; you’re future-proofing your entire operational model. The business case for accepting crypto payments is built on the pillars of instant liquidity, zero chargeback fraud, and seamless cross-border expansion. These strategic advantages allow you to reclaim lost margins and scale without the geographic constraints of traditional financial systems.

    Transitioning to these high-performance rails requires a partner that balances innovation with institutional reliability. As a regulated MSB in the USA and Canada, Pallapay provides the security and compliance necessary for enterprise-scale operations. We serve merchants in 180+ countries, offering instant fiat settlement in USD, EUR, and other major currencies to ensure your cash flow remains uninterrupted. Empower your business with Pallapay’s secure crypto gateway and start leveraging the efficiency of real-time commerce. Your journey toward a more agile, borderless financial future begins today.

    Frequently Asked Questions

    Is it legal for my business to accept cryptocurrency payments in 2026?

    Accepting digital assets is legal in most major global economies, provided you comply with local financial regulations. In 2026, frameworks like the EU’s Markets in Crypto-Assets (MiCA) and the UK’s Financial Services and Markets Act provide clear guidelines for commercial use. To ensure absolute compliance, businesses should partner with a regulated Money Services Business (MSB) that is registered with authorities like FinCEN in the United States or FINTRAC in Canada.

    How do I avoid the risk of Bitcoin price volatility when selling products?

    You can eliminate market risk entirely by utilizing instant fiat conversion at the point of sale. Modern payment gateways lock in the exchange rate the moment a customer completes their checkout. This ensures your business receives the exact fiat amount in your preferred currency, such as USD or EUR. By converting digital assets to fiat instantly, you bypass the volatility of the underlying asset while still offering a modern payment experience.

    What are the tax implications of accepting crypto for my business?

    Tax authorities generally treat cryptocurrency as property or a financial asset, meaning transactions are subject to standard corporate tax and capital gains rules. It’s essential to maintain accurate records for every sale. A professional gateway simplifies this process by providing automated reporting tools and immutable ledgers for tax audits. You should always consult with a qualified tax professional to ensure your reporting aligns with current regional requirements.

    Do I need a special bank account to receive fiat settlements from crypto sales?

    No, you don’t need a specialized bank account to receive your funds. You can continue using your existing corporate bank account to accept fiat settlements. The gateway acts as the technical bridge, converting the customer’s digital payment into your local currency. Once the conversion is complete, the funds are transferred to your bank via standard rails, making the entire process feel like a traditional merchant settlement.

    How much are the transaction fees compared to traditional credit cards?

    Transaction fees for digital assets are significantly lower, typically ranging from 0.5% to 1%. Traditional credit card processing often costs merchants between 1.5% and 3.5% per transaction. Reducing these overheads is a central part of the business case for accepting crypto payments. By switching to blockchain rails, you can recover significant margins that were previously lost to intermediaries and legacy network fees.

    What happens if a customer wants a refund for a crypto payment?

    Refunds are handled by initiating a new “push” transaction from your merchant dashboard to the customer’s wallet address. Because blockchain transactions are irreversible, you have total control over the refund process. Most businesses calculate the refund amount based on the fiat value at the time of the original purchase. This ensures the customer receives the correct value while protecting your business from fluctuations in the asset’s market price.

    Can I accept multiple cryptocurrencies like USDT, Ethereum, and Bitcoin simultaneously?

    Yes, a sophisticated payment gateway allows you to accept a diverse range of assets through a single integration. You can simultaneously offer stablecoins like USDT for price stability and high-market-cap assets like Bitcoin or Ethereum for tech-savvy consumers. This flexibility ensures you don’t alienate potential customers. It also allows you to tap into the $3 trillion global market cap without managing multiple technical setups or separate wallet infrastructures.

    How long does it take for the funds to reach my bank account?

    While the blockchain confirmation is nearly instant, the final transfer to your bank account typically takes 24 hours. This T+1 settlement is a vast improvement over the T+3 cycles common in traditional finance. By accelerating your cash flow, you gain immediate access to capital for reinvestment. The speed of these operations mirrors the real-time nature of modern commerce, giving your business a distinct edge in liquidity management.

    Disclaimer

    The information provided on this website and blog is for general informational and educational purposes only and does not constitute financial, investment, legal, tax, or other professional advice.
    Cryptocurrency and digital asset services may be subject to regulatory restrictions in certain jurisdictions. Users are solely responsible for ensuring compliance with applicable local laws and regulations before using any products or services mentioned on this website.
    PallaPay does not guarantee the accuracy, completeness, or timeliness of any information published and accepts no liability for any loss or damages arising from reliance on the content. Any opinions expressed are those of the respective authors and may change without notice.
    Certain services, features, or products referenced may be provided through third-party partners, licensed entities, or affiliated service providers subject to separate terms and regulatory approvals. Availability of services may vary by country or region.
    This website may contain references to digital assets, virtual currencies, or blockchain-related services that are not available to residents of certain jurisdictions, including where prohibited by law. Nothing on this website constitutes an offer, solicitation, or recommendation to buy or sell any financial instrument or virtual asset.
  • Crypto Chargeback Protection for Merchants: The 2026 Guide to Fraud-Free Payments

    Crypto Chargeback Protection for Merchants: The 2026 Guide to Fraud-Free Payments

    By the end of 2026, global chargeback transactions are projected to reach 337 million, with “friendly fraud” accounting for a staggering 86% of these disputes. If you’ve ever felt the sting of the “guilty until proven innocent” stance taken by major card networks, you aren’t alone. Most merchants now lose an average of $4.61 for every single dollar of fraud. This creates a massive drain on global revenue that traditional insurance simply cannot fix. It’s a frustrating reality where legitimate sales are often reversed without your consent.

    This guide demonstrates how crypto chargeback protection for merchants shifts the paradigm from expensive insurance to a secure, irreversible payment architecture. You’ll discover how a professional crypto gateway eliminates the possibility of forced reversals while maintaining institutional-grade stability for your business operations. We will explore the mechanics of blockchain finality, the role of stablecoins in securing your cash flow, and how to integrate a seamless API that protects your bottom line from the rising tide of payment fraud.

    Key Takeaways

    • Understand why traditional chargeback insurance often fails to protect margins and how a structural shift in payment processing provides a permanent solution.
    • Learn the technical mechanics of blockchain finality and how the “push” payment model prevents customers from unilaterally reversing confirmed transactions.
    • Discover the significant cost advantages of adopting crypto chargeback protection for merchants to replace high-fee traditional card networks.
    • Identify the necessary steps to integrate a professional crypto POS machine or API into your current checkout flow for secure global revenue.
    • Explore how partnering with a regulated gateway registered with FinCEN and FINTRAC ensures institutional-grade security and cross-border compliance.

    The Rising Cost of Chargeback Fraud for Merchants in 2026

    In 2026, the global retail sector faces a critical threshold as chargeback volume reaches a projected 337 million transactions. This figure represents a 42% increase from 2023 levels, signaling a systemic vulnerability in traditional payment networks. For many operators, particularly those in ecommerce, the financial impact is severe. Merchants are currently losing an average of $4.61 for every dollar of fraud encountered. This isn’t just a loss of revenue; it’s a direct erosion of profit margins through lost inventory, wasted shipping overheads, and escalating processor penalties. Traditional chargeback insurance has become a reactive and expensive band-aid that fails to address the root cause of the problem.

    The Mechanics of the Traditional Dispute System

    The traditional chargeback mechanism relies on a “pull” payment model where banks can reverse a transaction weeks after the sale is finalized. This system inherently favors the consumer, placing a heavy burden of proof on the merchant. Even with detailed documentation, merchants rarely win these disputes because card networks prioritize user trust over business security. High chargeback ratios don’t just result in immediate fees; they threaten the longevity of your merchant account. When a business exceeds certain thresholds, processors often impose higher transaction fees or mandate restrictive cash reserves, further stifling growth and liquidity.

    Why 2026 Requires a New Merchant Protection Standard

    As we move through 2026, consumer fraud tactics have become significantly more sophisticated. The rise of “friendly fraud,” which accounts for up to 86% of all disputes, often involves customers using AI-generated documentation to validate illegitimate claims. Traditional tools like 3D Secure provide a layer of friction, yet they fail to stop post-transaction reversals. Businesses can no longer rely on systems that treat fraud as an inevitable tax on operations. True crypto chargeback protection for merchants offers a shift from risk mitigation to total risk elimination. By adopting a payment architecture based on blockchain finality, you ensure that once a transaction is confirmed, the revenue remains under your control. This technological answer solves the operational need for absolute payment certainty in an increasingly volatile global market.

    Mastercard projects that U.S. merchants alone will lose $15 billion to chargeback fraud this year. This staggering loss highlights the inadequacy of current card-based systems. Transitioning to a secure gateway allows your business to bypass the “guilty until proven innocent” stance of major card networks. It’s time to replace outdated insurance policies with a payment model that provides the ultimate protection for your global revenue.

    How Crypto Chargeback Protection Works: The Power of Irreversibility

    At its core, crypto chargeback protection for merchants is not a service or an insurance policy; it’s a fundamental property of blockchain technology. In traditional finance, payments operate on a “pull” model. When a customer swipes a card, the merchant’s processor requests funds from the issuing bank. This authorization remains conditional, allowing the bank to unilaterally reverse the transaction weeks or even months later. Cryptocurrency flips this logic by using a “push” model. The customer must actively initiate the transfer of assets from their wallet to yours. Once the network confirms the transaction, the funds are moved permanently. There’s no central issuing bank with the authority to “pull” those funds back into the customer’s account.

    Distributed ledger technology (DLT) provides a transparent, immutable proof of payment that serves as the ultimate record for your accounting. Because every transaction is cryptographically secured and broadcast across a global network, the evidence of the transfer is indisputable. This eliminates the middleman typically responsible for initiating disputes. Without a centralized authority to mediate or reverse transactions, the merchant retains full control over their revenue. This structural shift moves the responsibility of refunds back to your own customer service department, ensuring that you only return funds when a claim is legitimate and verified by your team.

    The Blockchain as a Final Settlement Layer

    Understanding transaction finality is essential for managing institutional-grade financial flows. Transaction finality is the definitive state where a payment is permanently recorded on the blockchain and cannot be altered or reversed by any party. This protocol-level security ensures that once a digital asset reaches your wallet, it’s yours. Smart contracts can further refine this process by automating escrow or multi-signature approvals, providing a secure bridge between payment and delivery without the risk of traditional reversals. For businesses handling complex cross-border transactions, this creates a level of certainty that legacy banking systems simply can’t match.

    Comparing Traditional vs. Crypto Protection Frameworks

    The traditional dispute framework is inherently merchant-liable and characterized by slow, expensive resolution processes. Research from The Payments Association highlights that rising fraud levels are putting nearly half of certain retail sectors at risk of scaling back in 2026. This vulnerability stems from a system designed to protect the consumer at the merchant’s expense. In contrast, crypto offers a zero-dispute architecture where payments are final at the point of sale. Merchants in high-ticket industries like hotels and luxury e-commerce are increasingly prioritizing these payments to secure revenue on items with high shipping costs or non-refundable bookings. Integrating a professional payment API allows you to adopt this fraud-free model while maintaining the speed and efficiency your customers expect.

    Traditional Gateways vs. Crypto Chargeback Protection

    Traditional payment providers often market “chargeback protection” as a comprehensive shield, yet it’s essentially a reactive insurance policy laden with exclusions. These services typically require merchants to pay a premium on every transaction, often pushing processing fees well above 3%. In contrast, crypto chargeback protection for merchants is a structural feature of the payment architecture itself. By removing the ability for a central authority to reverse funds, the need for expensive insurance disappears. This allows for a leaner operational model where processing costs are significantly reduced compared to legacy card networks.

    Global reach and liquidity speed also define the divide between these two systems. Traditional card networks frequently flag cross-border sales as high-risk, leading to higher decline rates or extended hold periods that can last up to 14 days. These delays are designed to buffer the bank against potential disputes. Cryptocurrency transactions operate independently of these geographic restrictions and banking “cooling-off” periods. Settlements occur with near-instant speed, allowing businesses to maintain a healthier cash flow and re-invest capital into growth rather than waiting for funds to clear a processor’s risk department.

    The Hidden Limitations of Card Protection Services

    The “fine print” of traditional unauthorized transaction coverage often reveals a complex web of requirements. Merchants must frequently provide perfect evidence within strict timeframes to even qualify for protection. This creates an administrative nightmare that drains resources and rarely guarantees a win. Even if a merchant is “protected,” high chargeback ratios can still damage their reputation with acquiring banks. This can lead to increased scrutiny, higher reserve requirements, or the sudden termination of the merchant account. Relying on card-based protection means managing a symptom rather than curing the underlying vulnerability of the “pull” payment model.

    The Crypto Advantage: Proactive Security

    A secure crypto payment gateway provides proactive security by ensuring that every transaction is final at the point of confirmation. This structural irreversibility eliminates the “fraud tax” that many businesses have come to accept as a cost of doing business. As detailed in the report How Crypto Shields Merchants Against Chargeback Fraud, the shift to blockchain finality removes the mechanism that makes friendly fraud possible. By adopting this technology, businesses move away from the “guilty until proven innocent” stance of traditional finance. This shift toward crypto chargeback protection for merchants represents a move from passive risk management to active revenue security, allowing you to focus on global expansion without the fear of arbitrary fund reversals.

    Crypto Chargeback Protection for Merchants: The 2026 Guide to Fraud-Free Payments

    Implementing a Chargeback-Free Strategy for Your Business

    Transitioning to a fraud-free environment requires a deliberate shift in your payment architecture. To begin, select a regulated gateway that aligns with institutional standards. This ensures your revenue is handled by an entity registered with authorities like FinCEN in the USA or FINTRAC in Canada. Establishing this foundation is the first step in securing crypto chargeback protection for merchants. Once the partnership is formed, you can move toward technical integration. This process transforms your payment flow from a conditional authorization model to a definitive settlement model.

    Communicating the benefits of these payments to your customers is equally vital. Transparency regarding the irreversibility of blockchain transactions helps set expectations and reduces the likelihood of confusion. You can manage these digital assets through a secure merchant dashboard, which provides real-time visibility into your global revenue. Finally, utilize professional off-ramps to convert your protected revenue into local currency, ensuring your cash flow remains liquid and usable for daily operations.

    Integrating Crypto Payments Without Technical Friction

    Modern businesses require solutions that integrate into existing workflows without disrupting the user experience. Using a payment API allows you to automate secure checkouts, providing a seamless transition for online customers. For physical retail locations, setting up Crypto POS machines offers a familiar interface for both staff and shoppers. These tools ensure the checkout mirrors traditional card flows while providing the underlying security of the blockchain. This balance of familiarity and innovation is essential for maintaining high conversion rates while eliminating dispute risk.

    Managing Volatility and Liquidity

    A common concern for businesses is the price movement of digital assets. Professional fiat settlement removes this risk by instantly converting incoming crypto payments into stable currencies. This feature ensures that the value you see at the point of sale is the exact value you receive in your account. By setting up automated off-ramps to your corporate bank account, you can maintain a steady stream of liquidity. For instance, direct settlement in AED can save merchants approximately 2% to 3% on currency conversion costs compared to traditional methods. Maintaining a secure digital wallet for operational liquidity further empowers your business to move capital across borders with unmatched efficiency. To begin securing your global revenue, integrate a secure crypto gateway today.

    Secure Your Global Revenue with Pallapay’s Ecosystem

    Pallapay serves as the definitive destination for businesses seeking institutional financial reliability alongside disruptive innovation. In 2026, securing your global revenue requires a partner that understands both the technical finality of the blockchain and the practicalities of modern commerce. By providing crypto chargeback protection for merchants across more than 180 countries, we offer a level of stability that traditional networks cannot match. Our ecosystem is built on the confidence of a global industry leader, ensuring that your transition to digital asset payments is both secure and effortless. This global reach is supported by local expertise, ensuring that regardless of where your customers are located, your revenue remains protected from the risks of “friendly fraud” disputes.

    Institutional-Grade Compliance and Security

    Trust is the backbone of any financial operation. Pallapay maintains active MSB registration with FinCEN in the United States and FINTRAC in Canada, providing a professional bridge to established regulatory standards. We handle the complex background processes of Anti-Money Laundering (AML) and Know Your Customer (KYC) protocols so your team doesn’t have to manage these technical burdens. For high-volume settlements, our OTC crypto exchange offers a secure environment that prioritizes speed and safety. Additionally, our presence in major global hubs reinforces merchant trust through physical accessibility and dedicated support. This institutional grounding ensures that your business operates within a framework of absolute security and regulatory harmony.

    The Pallapay Merchant Advantage

    Adopting our technology means gaining access to a comprehensive suite of tools designed for rapid growth. The Pallapay merchant dashboard provides advanced statistics and cost-tracking, allowing you to monitor your global revenue with absolute clarity and real-time precision. We offer customizable solutions for retail stores and online platforms, ensuring that your specific operational needs are met with precision. This tailored approach allows you to scale your payment infrastructure at your own pace.

    Beyond basic processing, our ecosystem includes the Pallapay Mastercard and diverse gift card products, which add immediate utility to your digital holdings. These tools allow you to convert protected revenue into spending power instantly, bypassing the friction of traditional banking delays. By integrating these services, you create an efficient cycle of liquidity that supports your business’s momentum. Pallapay serves as the professional bridge that connects established practices with modern advancements, ensuring your business is ready for the inevitable global evolution of payments.

    Securing the Future of Global Merchant Revenue

    The evolution of digital commerce in 2026 demands a move away from the restrictive “guilty until proven innocent” mindset of traditional card networks. By adopting a system built on blockchain finality, you eliminate the mechanism that makes friendly fraud possible. This structural shift ensures that confirmed revenue stays in your control, providing the most reliable form of crypto chargeback protection for merchants available today. You’re no longer just managing risk; you’re removing it from your balance sheet entirely.

    Professional growth requires a partner that combines disruptive technology with institutional stability. Pallapay provides this through our status as an MSB registered entity in the USA and Canada, backed by a global OTC presence and near-instant fiat settlement capabilities. This ensures that your liquidity remains high while your operational friction stays low. It’s time to transition from outdated dispute systems to a future of absolute payment certainty. Secure your business against chargebacks with Pallapay’s global payment gateway. We look forward to helping you scale your international operations with total confidence.

    Frequently Asked Questions

    Is there any way for a customer to get a refund on a crypto payment?

    Yes, but the refund must be initiated by the merchant rather than the customer’s bank. Because blockchain transactions are irreversible by the sender, you retain full authority over your return policy. This structural shift is the core of crypto chargeback protection for merchants, ensuring that funds are only returned if you verify the claim is legitimate. It places the merchant back in control of the customer service and dispute resolution process.

    Do I need to understand blockchain technology to use crypto chargeback protection?

    No, you don’t need deep technical knowledge to implement these security features. Modern payment gateways handle the underlying cryptographic processes and network confirmations in the background. You interact with a professional merchant dashboard that feels identical to traditional financial tools. This allows you to focus on scaling your business while the technology provides a secure, fraud-free environment for every transaction you process.

    How do crypto gateway fees compare to traditional chargeback insurance?

    Crypto gateway fees are significantly more cost-effective, typically ranging from 0% to 1%. Traditional card networks often charge between 2.1% and 3.5%, and that doesn’t include the added premiums for separate chargeback insurance or the high costs of dispute penalties. By adopting a system with inherent protection, you eliminate the need for expensive “band-aid” insurance policies and reduce your overall operational overhead immediately.

    Can crypto payments be used for high-ticket items in industries like luxury travel?

    Yes, cryptocurrency is exceptionally well-suited for high-value transactions where the risk of “friendly fraud” is greatest. When selling luxury goods or travel packages, a single forced reversal can devastate your monthly margins. Using a secure gateway ensures that large payments are final at the point of confirmation. This provides institutional-grade certainty for high-ticket sectors, allowing you to ship goods or confirm bookings without the fear of post-sale fund withdrawals.

    What happens if a customer claims they didn’t receive the item after paying in crypto?

    The merchant manages the dispute internally based on their established terms and conditions. Unlike card networks that often side with the consumer by default, crypto payments don’t have a third-party “issuing bank” that can freeze your funds. You can review the customer’s claim and shipping evidence fairly. If a mistake occurred, you can issue a voluntary refund; if the claim is fraudulent, your revenue remains safely in your account.

    Is crypto chargeback protection legal and compliant for US-based merchants?

    Yes, accepting cryptocurrency is fully legal and compliant for merchants in the United States and other global regions. To ensure institutional trust, it’s essential to partner with a gateway that is MSB registered. Pallapay is registered with FinCEN in the USA and FINTRAC in Canada, ensuring that your crypto chargeback protection for merchants is backed by a framework of global regulatory compliance and institutional financial reliability.

    How quickly can I convert my crypto payments into fiat currency like USD or EUR?

    Conversions can happen near-instantly through professional fiat settlement services. You don’t have to wait for the traditional 7 to 14 day hold periods required by many credit card processors. Most gateways allow you to lock in the exchange rate at the moment of the transaction, protecting you from price volatility. This ensures that your revenue is available for bank transfer or operational use in your local currency with minimal delay.

    Can I accept multiple cryptocurrencies like Bitcoin, Ethereum, and USDT simultaneously?

    Yes, a comprehensive payment gateway allows you to accept a diverse range of digital assets through a single API or POS integration. This flexibility caters to a global audience while consolidating all incoming payments into a unified merchant dashboard. Whether a customer pays in Bitcoin or a stablecoin like USDT, the transaction remains irreversible. This ensures your business captures every sales opportunity without exposing itself to the risks of traditional payment disputes.

    Disclaimer

    The information provided on this website and blog is for general informational and educational purposes only and does not constitute financial, investment, legal, tax, or other professional advice.
    Cryptocurrency and digital asset services may be subject to regulatory restrictions in certain jurisdictions. Users are solely responsible for ensuring compliance with applicable local laws and regulations before using any products or services mentioned on this website.
    PallaPay does not guarantee the accuracy, completeness, or timeliness of any information published and accepts no liability for any loss or damages arising from reliance on the content. Any opinions expressed are those of the respective authors and may change without notice.
    Certain services, features, or products referenced may be provided through third-party partners, licensed entities, or affiliated service providers subject to separate terms and regulatory approvals. Availability of services may vary by country or region.
    This website may contain references to digital assets, virtual currencies, or blockchain-related services that are not available to residents of certain jurisdictions, including where prohibited by law. Nothing on this website constitutes an offer, solicitation, or recommendation to buy or sell any financial instrument or virtual asset.
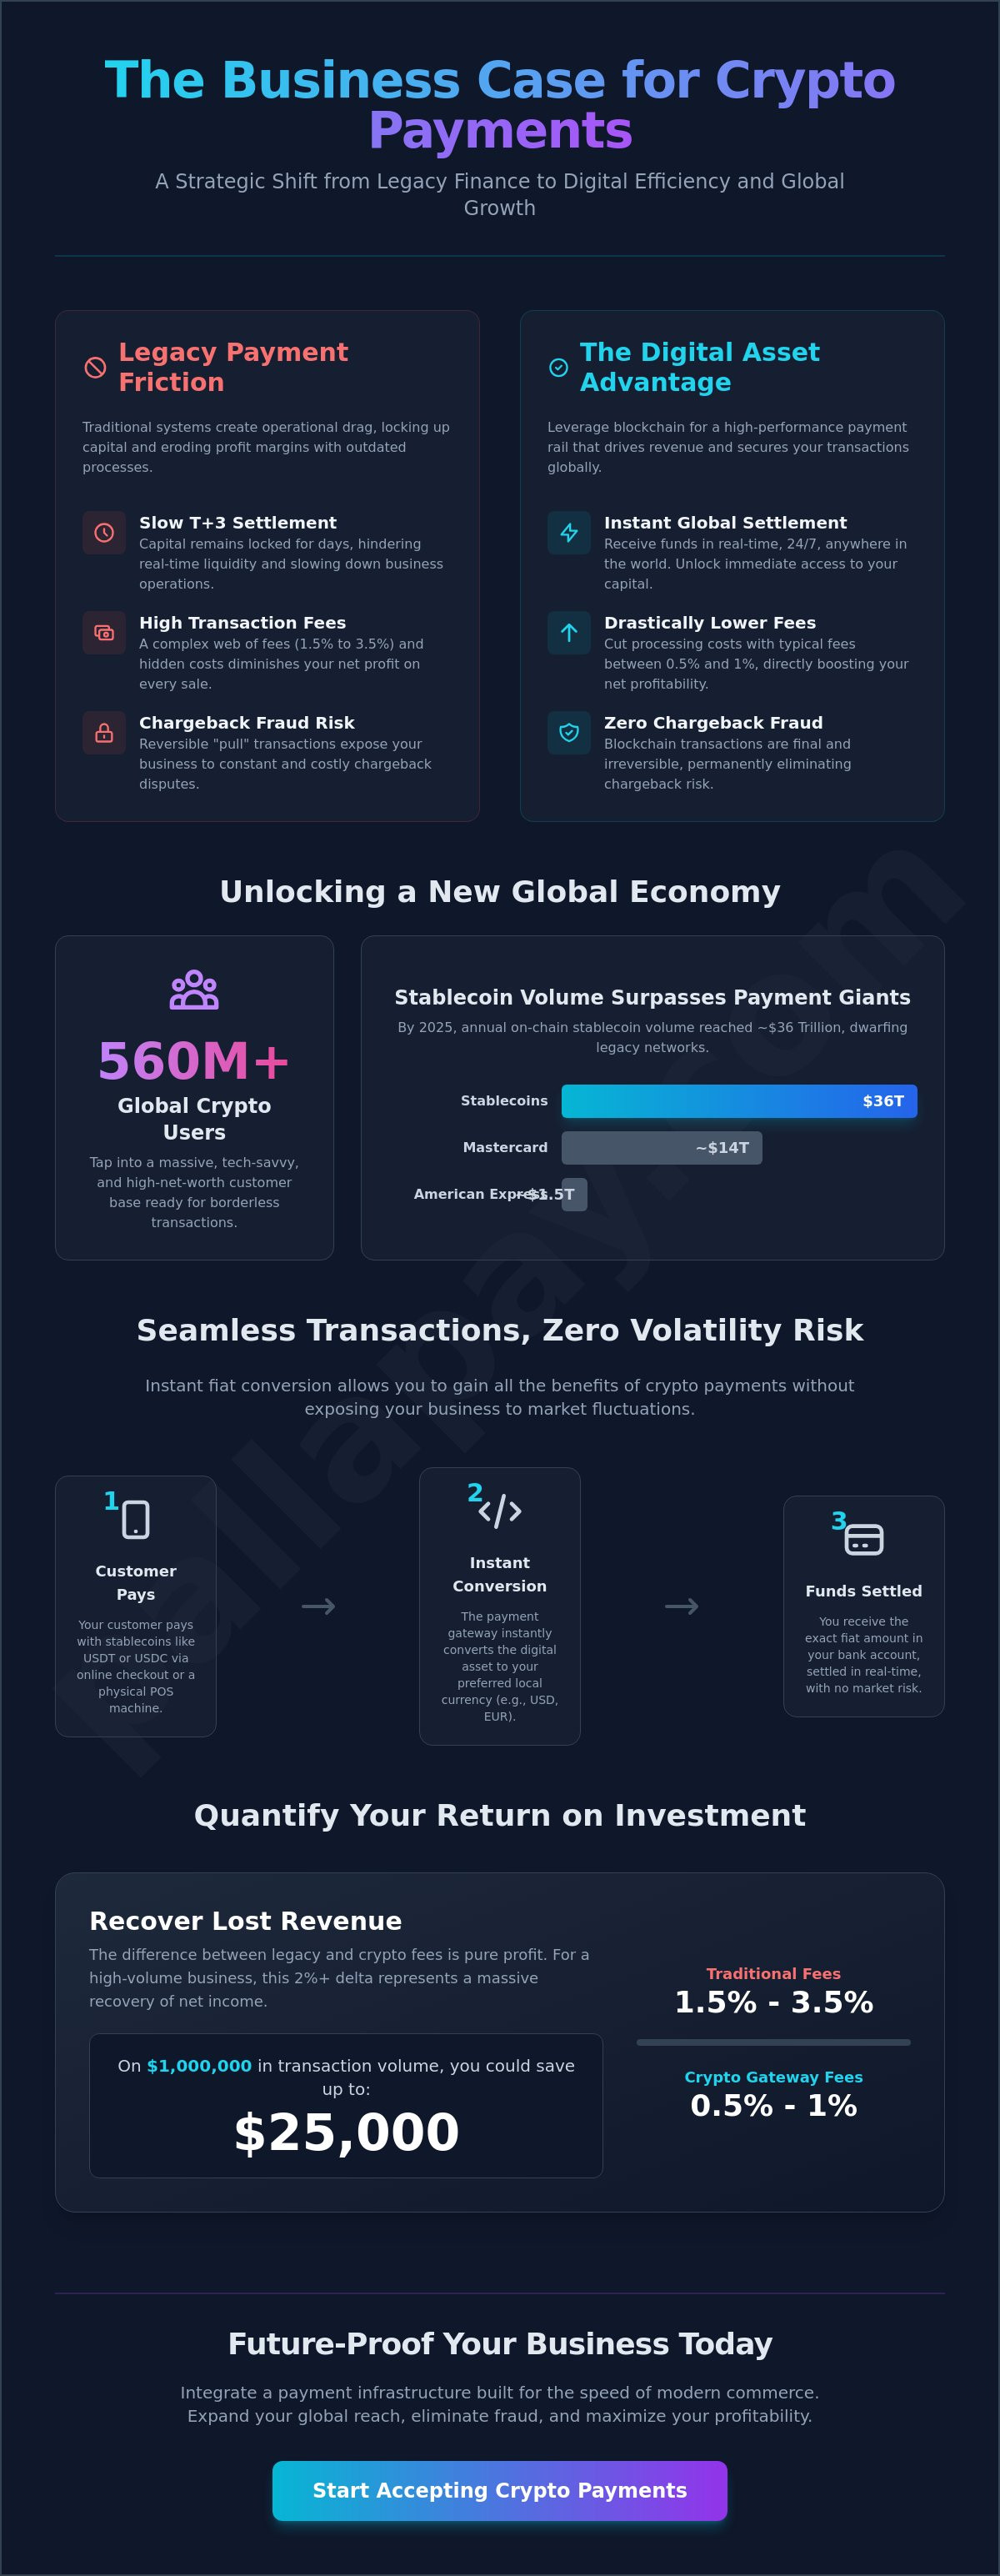
  • Protecting Business From Crypto Volatility: The 2026 Strategic Guide

    Protecting Business From Crypto Volatility: The 2026 Strategic Guide

    In 2026, market price swings are no longer an acceptable excuse for stagnant business growth. While Bitcoin fluctuates between $77,000 and $80,000, many leaders remain hesitant because they fear a sudden crash could erase their operational margins. You’re right to be cautious; manual exchange processes are slow and regulatory deadlines like the July 1 MiCA cutoff in the EU add layers of complexity. However, protecting business from crypto volatility has evolved from a complex hedging strategy into a standard, automated utility.

    You don’t have to be a market speculator to benefit from the $4 trillion digital asset economy. This article explains how to accept payments and scale your operations without ever being exposed to market price fluctuations. We’ll explore the transition to a set and forget payment system that utilizes instant conversion to local currency and regulated settlement routes. By the end of this guide, you’ll understand how to integrate a crypto payment gateway that handles the technical background processes, ensuring every transaction settles as stable fiat in your account.

    Key Takeaways

    • Identify and close the settlement gap by neutralizing the time delay between customer payment and fiat receipt.
    • Utilize automated fiat conversion to lock in real-time exchange rates, ensuring your profit margins remain unaffected by sudden market shifts.
    • Deploy stablecoins like USDT and USDC as strategic buffers to facilitate secure and predictable international B2B settlements.
    • Build a resilient infrastructure for protecting business from crypto volatility by integrating regulated payment APIs with official MSB registrations.
    • Scale your operations with institutional-grade OTC support and crypto-to-bank transfer routes designed for compliant, high-volume shielding.

    What is Crypto Volatility and Why Does it Challenge Modern Business?

    Crypto volatility represents the rapid, often unpredictable price fluctuations of digital assets over condensed timeframes. For a trader, these swings are an opportunity for profit; for a business owner, they represent an operational threat. To understand What is Cryptocurrency and its inherent behavior, one must recognize that price action is driven by market sentiment and liquidity rather than traditional quarterly earnings. While a 5% daily move is standard in digital markets, it can be catastrophic for a company operating on thin margins.

    The primary challenge for merchants lies in the “Settlement Gap.” This is the critical window between the moment a customer initiates a payment and the moment the business receives usable funds in their bank account. If the asset value drops during this interval, the merchant effectively loses revenue before the transaction even clears. Protecting business from crypto volatility requires closing this gap through automated fiat settlement systems that provide an immediate hedge against market movement.

    The Hidden Costs of Unmanaged Fluctuations

    Unmanaged exposure erodes profit margins, especially during high-velocity sell-offs where prices can drop faster than manual exchange processes can clear. Beyond direct losses, accounting teams face significant complexities when the value of an asset shifts between the time an invoice is issued and the final audit. Price slippage occurs when the final execution price of a trade differs from the requested price due to market movement or insufficient liquidity, often resulting in unexpected costs for high-ticket B2B transactions. These friction points turn a modern payment method into a financial liability without the right shielding tools.

    Why 2026 Market Dynamics Require a Proactive Stance

    By mid-2026, the landscape has shifted due to massive institutional participation and maturing regulatory frameworks. With Bitcoin trading between $77,000 and $80,000 as of May 2026, and the scheduled launch of CME Group’s Bitcoin Volatility futures on June 1, price movements have become more sophisticated and faster. Liquidity now plays a dual role; deep liquidity can stabilize prices, yet global economic shifts can trigger rapid business-day swings that catch unprepared merchants off guard. Protecting business from crypto volatility is no longer about avoiding digital assets, but about using professional infrastructure to neutralize their erratic nature. Modern commerce demands a proactive stance where volatility is managed as a technical variable rather than a financial risk.

    The Mechanics of Instant Fiat Settlement: Your Primary Defense

    Relying on manual trading to manage digital assets is a high-stakes gamble that few corporations can afford. Protecting business from crypto volatility becomes a seamless background process through the implementation of instant fiat settlement. A professional gateway functions as a sophisticated buffer; it locks the exchange rate for a specific transaction window, typically between 15 and 20 minutes. This lock-in ensures that the amount of local currency you expect is exactly what arrives in your treasury, regardless of market movements during the confirmation process.

    The technological engine behind this is fiat settlement, which facilitates the automated conversion of assets like Bitcoin or Ethereum into USD, EUR, GBP, or CNY. This process removes the need for your company to hold volatile assets on its balance sheet. By choosing instant settlement over batch processing, you maintain superior cash flow and avoid the risk of overnight price drops that frequently plague unshielded accounts. It’s the difference between managing a currency and managing a risk.

    Eliminating Exchange Rate Risk at the Point of Sale

    Gateways calculate real-time spreads by connecting to institutional liquidity providers. These providers guarantee the locked price, absorbing the market risk so your business doesn’t have to. This automated workflow eliminates the human error and delay associated with manual trading. It’s a strategic shift from speculative uncertainty to operational stability. Businesses looking to automate this transition often integrate a crypto payment API to synchronize sales with financial records in real-time.

    Streamlining Accounting and Tax Compliance

    Receiving fiat directly simplifies VAT and corporate tax reporting significantly. It establishes a clear 1:1 ratio between the invoice amount and the settled bank deposit, which is essential for audit transparency. When you settle directly to bank accounts, you bypass the friction of digital asset custody.

    • Direct fiat settlement removes the need for complex capital gains calculations on every individual sale.
    • It allows for seamless integration with standard ERP systems, ensuring your books remain balanced without manual intervention.
    • Financial teams can treat these transactions as standard bank transfers rather than digital asset movements, reducing the training required for staff.

    This approach turns a disruptive technology into a standard, effortless business operation. By removing the volatility variable, you focus on growth while the gateway handles the underlying mechanics of currency conversion.

    Stablecoins: Using USDT and USDC as a Strategic Buffer

    While instant fiat conversion is the premier defense for retail transactions, many B2B operations require a more flexible medium for holding digital value. Stablecoins are digital assets pegged 1:1 to traditional currencies like the US Dollar, combining the borderless efficiency of blockchain with the price predictability of fiat. By utilizing these assets, you create a strategic layer for protecting business from crypto volatility without needing to exit the digital ecosystem entirely. As of March 2026, USDT maintains its position as a primary liquidity tool with a market capitalization of approximately $183.6 billion, while USDC has grown to $75.3 billion, largely due to its alignment with the GENIUS Act in the United States and MiCA regulations in Europe.

    The operational utility of stablecoins relies on a reliable transition between digital and traditional finance. Converting these assets into bank transfers or physical cash is handled through professional off-ramp services, which act as a vital bridge for global liquidity. This infrastructure allows a business to accept USDT from an international client and move it into a corporate bank account with the same speed and security as a local wire transfer. It’s a sophisticated method for protecting business from crypto volatility while maintaining the ability to deploy capital whenever it’s needed.

    Cross-Border Payments Without the Swing

    Traditional SWIFT transfers are often slow and burdened by high intermediary fees. Stablecoins bypass these legacy bottlenecks, allowing businesses to pay global suppliers instantly at any hour. This is particularly advantageous during “weekend” market gaps when traditional banks are closed but digital markets remain active. By settling in USDT or USDC, you ensure that the value sent on Friday is the same value received on Saturday, regardless of how Bitcoin or Ethereum might perform over the weekend. It’s an essential tool for maintaining price consistency across complex supply chains.

    Managing Liquidity with Digital Wallets

    A secure crypto wallet serves as more than just storage; it’s a command center for holding operational reserves. Professional teams use these wallets to balance fiat holdings with stablecoin liquidity, allowing for rapid re-investment or settlement without waiting for traditional banking cycles. In 2026, audited and fiat-backed stablecoins operate within a mature regulatory framework, providing a transparent and secure foundation for corporate treasury management. This integrated approach ensures that your business remains agile and liquid, regardless of broader market fluctuations.

    Protecting Business From Crypto Volatility: The 2026 Strategic Guide

    Building a Volatility-Resistant Infrastructure for Retail and Web

    Establishing a robust infrastructure requires a multi-layered approach that bridges digital and physical sales channels. Protecting business from crypto volatility is most effective when the protection is baked into the hardware and software used daily. First, prioritize a regulated provider with official MSB registrations in credible jurisdictions like the US and Canada to ensure compliance and institutional trust. Second, integrate a crypto payment API to automate web checkouts and eliminate manual conversion delays. Third, for physical locations, deploy Crypto POS machines that lock in rates at the moment of sale. Fourth, configure auto-withdraw settings to move funds to your bank account daily. Finally, train your finance team to view these assets as a high-speed payment rail rather than a speculative investment.

    This systematic deployment turns a complex financial challenge into a standard operational workflow. By automating the conversion and withdrawal process, you ensure that your treasury remains liquid and denominated in the currency you use to pay your bills. Protecting business from crypto volatility isn’t about predicting the market; it’s about building a system that doesn’t care what the market does.

    Unified Protection for Omni-channel Commerce

    Managing online and offline sales through a single dashboard provides a comprehensive view of global liquidity and transaction history. For retail stores, this setup allows staff to process transactions without needing to manage private keys or understand blockchain mechanics. Hardware-level encryption in POS terminals ensures that every swipe or scan is secure, providing institutional-grade safety at the point of sale. This unified approach eliminates the data silos that often lead to accounting errors in multi-channel businesses.

    Future-Proofing with Advanced Payment APIs

    Advanced APIs allow you to display prices in local fiat while accepting digital assets, ensuring that your customers see familiar figures while you avoid market risk. This is crucial for e-commerce platforms scaling to a global audience with multi-currency support. Managing refunds and chargebacks becomes a standard accounting task when the system automatically calculates the fiat-equivalent value at the time of the transaction. This level of automation allows you to scale from local sales to global distribution without increasing your financial risk profile.

    Ready to secure your revenue streams? Integrate a professional payment API to automate your volatility protection and streamline your global checkouts.

    Why Pallapay is the Professional Choice for Volatility Management

    Pallapay stands as a definitive destination for corporations seeking to bridge the gap between disruptive innovation and institutional financial reliability. By maintaining official MSB registrations in the United States and Canada, the platform provides a foundation of trust that many unregulated entities cannot match. This regulatory standing is essential for protecting business from crypto volatility, as it ensures that every conversion and settlement follows strict compliance protocols. Businesses gain access to a comprehensive, integrated ecosystem that includes a robust crypto payment gateway, physical POS machines, and the Pallapay Mastercard. This suite of tools allows you to manage digital assets as easily as traditional fiat, creating a seamless environment for modern commerce without the friction of multiple third-party providers.

    The brand functions as a professional bridge that connects established practices with modern advancements. By providing a single destination for all technical needs, it removes the complexity of managing disparate systems. This personality is reliable, efficient, and highly focused on empowering the user. It projects an image of a sophisticated partner that handles complex background processes, allowing you to focus on your core business growth while the infrastructure handles the market dynamics.

    Institutional Security and Compliance

    Adhering to rigorous crypto security standards is a core requirement for safeguarding merchant funds in 2026. Working with a regulated entity significantly reduces the risk of exposure to “dirty” cryptocurrency, which can lead to frozen accounts and legal complications. Pallapay acts as a professional facilitator, ensuring that all digital assets entering your treasury are vetted and compliant with international anti-money laundering standards. This level of institutional-grade oversight is a powerful tool for business expansion into over 180 countries. It gives your finance team the confidence to accept payments from diverse markets while knowing that the underlying technical background processes are handled by a sophisticated strategic partner.

    High-Volume Shielding with OTC Services

    Large-scale enterprises often require specialized handling for high-value transactions that exceed standard gateway limits. Through OTC crypto exchanges, businesses can move millions of dollars in assets without triggering market price slippage. This private, high-volume shielding is supported by a global network of physical offices that provide personalized corporate settlement assistance. These locations serve as a professional bridge, allowing for direct cash-to-crypto or crypto-to-bank transfers in a secure environment. It’s an efficient way to manage large-scale liquidity while protecting business from crypto volatility at every step of the conversion process, ensuring that institutional users maintain absolute stability.

    Strategic stability is the hallmark of a successful 2026 enterprise. By integrating these tools, you transform digital assets into a reliable utility for growth. Protect your business from volatility with Pallapay today and join a global network of professionals who prioritize security and speed.

    Secure Your Global Revenue Strategy

    The evolution of digital finance in 2026 has transformed market swings from a merchant’s nightmare into a manageable technical variable. By implementing instant fiat settlement and leveraging regulated stablecoin buffers, you’ve seen that liquidity and stability can coexist within a single ecosystem. Protecting business from crypto volatility is no longer a matter of timing the market; it’s about selecting the right institutional-grade infrastructure to automate your treasury flows. This proactive approach ensures your profit margins remain intact while you tap into a maturing $4 trillion global economy.

    Pallapay provides this essential bridge, offering MSB-registered security in the USA and Canada while serving professional clients across 180+ countries. You can now accept digital assets with the absolute confidence of instant fiat settlement in USD, EUR, and other major currencies. Secure your business margins with Pallapay’s regulated payment gateway and turn disruptive innovation into a standard, effortless business operation. Your enterprise is ready to lead in a borderless market. Take the next step toward a stable, high-growth future today.

    Frequently Asked Questions

    How can a business accept Bitcoin without being exposed to its volatility?

    You can accept Bitcoin safely by using a crypto payment gateway that facilitates instant fiat conversion at the point of sale. This system locks the exchange rate for the duration of the transaction window, ensuring you receive the exact local currency amount. By converting the asset immediately, your business avoids the risk of holding a digital asset that might decrease in value before you can manually exchange it.

    Is it better to settle in fiat currency or keep stablecoins in 2026?

    The decision depends on your treasury needs; fiat settlement provides immediate stability for local expenses while stablecoins offer high-speed liquidity for international B2B settlements. Many corporations choose fiat for retail operations to simplify accounting and tax reporting. Stablecoins like USDT or USDC are often reserved for paying global suppliers or maintaining digital reserves that don’t require traditional banking hours to move.

    What is the difference between a crypto exchange and a merchant payment gateway?

    A merchant payment gateway is a specialized tool for commercial transactions that prioritizes rate locks and automated settlement, whereas an exchange is built for trading and speculation. Gateways provide the essential infrastructure for protecting business from crypto volatility by removing the need for manual trading. They integrate directly with your sales platform to ensure that every transaction settles into your bank account as a standard currency deposit.

    Can I set my own exchange rates when accepting crypto payments?

    Merchants typically don’t set their own rates because the gateway provides a real-time institutional rate at the moment of checkout. This rate is pulled from deep liquidity providers to ensure it remains competitive and accurate for the customer. Attempting to set manual rates would likely lead to significant price slippage or lost sales due to uncompetitive pricing compared to the global market average.

    How do I handle taxes if the crypto price changes before I sell it?

    You should consult a qualified tax professional to understand the specific reporting requirements in your region. Using a gateway that converts crypto to fiat instantly simplifies this task by establishing a clear cost basis at the exact moment of the sale. This creates a transparent, 1:1 record between your invoice and your bank deposit, which is vital for maintaining compliant records during a corporate audit.

    What are the fees for protecting a business from crypto volatility?

    Fees for volatility protection are generally integrated into the transaction spread or charged as a small percentage of the total volume processed through the gateway. You should review the specific service agreement of your provider to understand the costs associated with POS machines or API integrations. The cost of protecting business from crypto volatility is usually far lower than the potential revenue loss from a single market crash.

    Is a Crypto POS machine safer than a standard wallet for my store?

    A Crypto POS machine is much safer for retail environments because it uses hardware-level encryption and prevents staff from accessing private keys. Standard wallets are designed for individual custody and lack the multi-user permissions and reporting features required for a commercial setting. POS systems are purpose-built to handle high-velocity sales and facilitate instant settlement into your corporate accounts without manual intervention.

    How long does it take to convert crypto to a bank transfer?

    The conversion from crypto to fiat is often instant through a professional gateway, while the transfer to your bank account depends on standard banking network speeds. Most off-ramp services facilitate these transfers within the same business day or the next, depending on the destination currency and bank. Automated withdrawal settings can be configured to ensure your funds move from the gateway to your bank account on a recurring daily schedule.

    Disclaimer

    The information provided on this website and blog is for general informational and educational purposes only and does not constitute financial, investment, legal, tax, or other professional advice.
    Cryptocurrency and digital asset services may be subject to regulatory restrictions in certain jurisdictions. Users are solely responsible for ensuring compliance with applicable local laws and regulations before using any products or services mentioned on this website.
    PallaPay does not guarantee the accuracy, completeness, or timeliness of any information published and accepts no liability for any loss or damages arising from reliance on the content. Any opinions expressed are those of the respective authors and may change without notice.
    Certain services, features, or products referenced may be provided through third-party partners, licensed entities, or affiliated service providers subject to separate terms and regulatory approvals. Availability of services may vary by country or region.
    This website may contain references to digital assets, virtual currencies, or blockchain-related services that are not available to residents of certain jurisdictions, including where prohibited by law. Nothing on this website constitutes an offer, solicitation, or recommendation to buy or sell any financial instrument or virtual asset.
  • How to Avoid Crypto Volatility for Merchants in the UAE: The 2026 Strategic Guide

    How to Avoid Crypto Volatility for Merchants in the UAE: The 2026 Strategic Guide

    Market volatility isn’t a barrier to entry; it’s a technicality that your payment processor should handle for you. Many business owners across the UAE hesitate to adopt digital assets because they fear a sudden price crash could erase their daily margins. You can effectively avoid crypto volatility for merchants uae by utilizing instant fiat settlement systems that lock in the exchange rate at the exact moment of sale. This approach transforms a fluctuating asset into a stable AED deposit within seconds, ensuring your revenue remains protected from market swings.

    You likely agree that managing a business is demanding enough without monitoring the hourly price of Bitcoin or decoding the latest Securities and Commodities Authority (SCA) mainland regulations. This strategic guide will show you how to eliminate market risk and accept digital payments with the confidence of receiving AED or USD directly in your bank account. We’ll explore the 2026 regulatory landscape, including the 9% corporate tax threshold for profits exceeding AED 375,000, and demonstrate how a seamless gateway provides a friction-free checkout for your global customers.

    Key Takeaways

    • Master the “lock-in” mechanism that secures exchange rates at the moment of checkout to protect your business revenue from market fluctuations.
    • Identify the specific technological bridges required to avoid crypto volatility for merchants uae and secure instant fiat settlements for every sale.
    • Evaluate the operational differences between holding stablecoins and receiving direct AED bank transfers to optimize your corporate liquidity.
    • Navigate the evolving UAE regulatory environment by aligning your payment infrastructure with current SCA and ADGM standards for total compliance.
    • Leverage a proprietary gateway to automate the complex process of crypto-to-fiat conversion, ensuring a seamless, friction-free experience for your customers.

    The UAE Merchant Dilemma: Balancing Innovation with Market Stability

    The UAE has solidified its status as a premier global destination for digital finance. With the national Digital Economy Strategy aiming to increase the sector’s GDP contribution to 19.4% by 2032, businesses are under pressure to modernize. For many, the first step is accepting cryptocurrency at the point of sale. However, a significant gap exists between speculative interest and commercial utility. While an investor might welcome a 15% price surge, a business owner cannot risk a 15% drop during a settlement window. Learning how to avoid crypto volatility for merchants uae is no longer a luxury; it’s a functional requirement for sustainable growth in 2026.

    The current market sentiment reflects a sophisticated consumer base. High-net-worth individuals in the UAE increasingly prefer settling luxury purchases using digital assets. For the merchant, this creates a specific dilemma. Rejecting these payments means losing market share to tech-forward competitors. Accepting them without a strategy means exposing the balance sheet to unnecessary risk. Implementing technology to avoid crypto volatility for merchants uae is the only way to bridge this gap, ensuring that innovation doesn’t compromise your financial stability.

    The Psychology of Market Swings in UAE Commerce

    Consumer behavior in the UAE is closely tied to digital asset performance. When markets rally, spending power in the retail and hospitality sectors typically increases. Merchants often fear the “Volatility Tax,” which is the loss of value that occurs when a payment is received in a volatile asset and held in a traditional wallet. To thrive, businesses must adopt a settlement mindset. This means viewing the transaction as a bridge to fiat currency rather than an investment. By prioritizing instant fiat settlement, you remove the emotional and financial stress of monitoring market charts.

    Impact on Business Margins and Financial Reporting

    Financial precision is critical, especially with the UAE’s 9% corporate tax on profits exceeding AED 375,000. For industries with thin margins, such as retail stores or electronics, even a minor price dip can turn a profitable sale into a loss. Accounting for fluctuating assets is a complex task for compliance teams. The UAE’s regulatory framework, managed by the SCA and ADGM, provides a stable environment, but it’s the merchant’s responsibility to ensure price certainty. Utilizing a gateway that locks in exchange rates ensures that your financial reporting remains accurate and your margins stay protected from the first transaction to the final audit.

    Understanding the Architecture of Volatility Mitigation

    Eliminating market risk requires a robust technical architecture that acts as a digital shield. A professional crypto payment gateway serves as this barrier, separating your business operations from the inherent price swings of the digital asset market. By integrating such a system, you can effectively avoid crypto volatility for merchants uae while providing modern payment options to your clientele. The core of this protection is the lock-in mechanism. This feature secures the exchange rate at the exact moment of checkout, typically via a timed QR code. It ensures the AED value you see on your invoice is exactly what arrives in your bank account, regardless of market movements during the transaction.

    The journey of a transaction is designed for maximum efficiency and security. It begins when a customer initiates a payment from their digital wallet. The gateway immediately communicates with global liquidity providers to source the best available rate. Instead of holding the asset and hoping for stability, the system executes an instant trade. The funds are then routed through a secure settlement engine, moving from the blockchain to the traditional banking system in the form of fiat currency. This process removes the burden of managing private keys or monitoring exchange charts, letting you focus on core business growth.

    Instant Conversion vs. Long-term Holding

    Speed functions as the ultimate hedge against financial loss. Real-time conversion removes the window of exposure where price drops typically occur. Instant Settlement is the immediate conversion of digital assets to fiat at the point of sale. This process ensures that your books are always balanced in AED or USD, even if a specific token drops in value minutes later. Merchants who prioritize this rapid transition can scale their digital offerings without the burden of speculative risk. It’s the difference between being a passive investor and a proactive global merchant.

    Liquidity Pools and Slippage Protection

    Maintaining rate stability during high-volume periods requires access to deep liquidity pools. These pools allow the gateway to execute large orders without causing slippage, which is the difference between the expected price and the actual executed price. Utilizing a robust payment-api ensures that your checkout process remains stable even during peak market activity. This technical reliability is reinforced by the UAE’s official virtual asset regulations, which provide the legal foundation for secure, institutional-grade financial services. For businesses seeking a truly hands-off approach, exploring a dedicated fiat settlement solution is the most efficient way to modernize your corporate treasury.

    Stablecoins vs. Instant Fiat Settlement: Choosing Your Shield

    Selecting the appropriate financial instrument is the next step in securing your business revenue. While the technical architecture protects you from price swings, your choice between stablecoins and fiat currency determines your daily liquidity. To effectively avoid crypto volatility for merchants uae, you must evaluate whether your business benefits more from holding digital assets or receiving bank deposits. Stablecoins like USDT provide a digital-native solution, while fiat-settlement offers the familiarity of traditional accounting. Both options eliminate the “Volatility Tax” discussed earlier, but they carry different operational costs and benefits.

    • Stablecoin Gas Fees: These are network costs paid to the blockchain. During high-traffic periods, these can fluctuate, though Layer 2 solutions have significantly reduced these costs in early 2026.
    • Gateway Processing Fees: These are predictable, flat-rate or percentage-based fees that include the conversion service, security, and compliance reporting.
    • Accounting Clarity: Fiat settlements provide a clear audit trail in AED, which simplifies reporting for the UAE’s 9% corporate tax on profits exceeding AED 375,000.

    The Strategic Role of USDT in Regional Trade

    USDT has become a cornerstone of UAE commerce, acting as a “Digital Dirham” for many B2B transactions. It offers a middle ground, providing the speed of blockchain with the price stability of the US Dollar. For cross-border trade, USDT is often superior to traditional banking because it settles in seconds rather than days. This liquidity advantage is particularly valuable for merchants who need to pay international suppliers immediately after a sale. Since crypto transactions in the UAE are exempt from the 5% VAT, using stablecoins for large-scale procurement can result in significant cost efficiencies compared to traditional wire transfers.

    Automated Workflows for Fiat Payouts

    High-ticket industries, such as luxury retail or hospitality, often require the certainty of a bank balance. You can streamline this by setting up an automated off-ramp. This system triggers a conversion to AED, USD, or EUR as soon as the transaction is verified on the blockchain. Modern gateways integrate directly with your existing accounting software, allowing for seamless reconciliation without manual data entry. By automating these payouts, you ensure that your corporate treasury is never exposed to market fluctuations, even for a few minutes. This hands-off approach makes digital payments feel like a standard, effortless business operation.

    How to Avoid Crypto Volatility for Merchants in the UAE: The 2026 Strategic Guide

    Regulatory Compliance and Infrastructure for UAE Businesses

    Compliance isn’t just a legal hurdle; it’s a strategic asset for those who want to avoid crypto volatility for merchants uae. By operating within the UAE’s multi-tiered regulatory system, businesses gain access to institutional-grade security that protects their liquidity. Whether you are governed by the Securities and Commodities Authority (SCA) on the mainland or the Financial Services Regulatory Authority (FSRA) in Abu Dhabi, adherence to these standards ensures your settlement gateway remains operational. As of April 2026, new guidance on virtual asset issuance has further clarified reporting requirements, making it easier to integrate digital payments without risking your commercial license.

    Rigorous AML (Anti-Money Laundering) and KYC (Know Your Customer) protocols are the backbone of a reliable payment infrastructure. These processes verify the source of funds and prevent fraudulent transactions from entering your ecosystem. For a merchant, this means every AED or USD received is verified and fully compliant with international reporting frameworks like the OECD’s Crypto-Asset Reporting Framework (CARF). High security standards in 2026 also include multi-signature authorization and cold storage for any non-settled assets, providing a definitive defense against digital theft.

    Choosing a Regulated Fintech Partner

    Unregulated gateways are a liability that no professional business can afford. If a provider lacks the necessary Money Services Business (MSB) registration, they risk sudden shutdowns that could freeze your corporate funds. A verified partner should offer transparent fee structures and clear jurisdictional authority. You can read more about institutional standards in our OTC Crypto Exchange Guide to understand how high-volume transactions are secured at the professional level. Selecting a partner that prioritizes compliance is the only way to ensure long-term stability.

    Hardware vs. Software: Securing the Point of Sale

    Your choice of infrastructure depends on your specific business model. Physical locations benefit from implementing Crypto POS Machines, which provide a familiar, secure checkout experience for customers. For online ventures, end-to-end encryption and a unified merchant dashboard are essential for tracking sales across multiple locations. These tools allow you to monitor your settlements in real-time, ensuring you always have a clear view of your cash flow. Secure your business today with our compliant payment API to begin accepting digital assets with total peace of mind.

    The Pallapay Advantage: Instant Settlements for the Modern Merchant

    Pallapay stands as a visionary partner for businesses ready to bridge the gap between blockchain innovation and institutional financial reliability. By utilizing a proprietary instant conversion engine, we provide the technical infrastructure needed to avoid crypto volatility for merchants uae. Our technology manages the heavy lifting of real-time conversion, allowing your team to focus on customer service rather than currency charts. Whether you’re operating in the hotels sector or managing high-volume retail store chains, our ecosystem provides a unified solution that scales with your ambition. As of March 2026, we maintain a competitive edge with transaction fees ranging from 0% to 1%, ensuring that your transition to digital payments remains cost-effective.

    The Pallapay ecosystem is designed as an all-in-one destination for corporate financial needs. From robust API integrations for e-commerce to physical POS terminals for storefronts, we ensure that every touchpoint is secure and efficient. Merchants can also access up to a 50% discount on transaction fees by holding the Palla token, a feature designed to reward long-term partners within our network. This utility-focused approach transforms complex crypto-fiat processes into a standard, effortless business operation that mirrors the speed of modern commerce.

    The Future of Payments: Zero-Risk Crypto Acceptance

    Accepting digital assets doesn’t have to carry speculative risk. Our platform allows you to bypass the 24/7 market fluctuations by locking in exchange rates at the exact moment of checkout. This instant settlement approach means the volatility seen on global exchanges never touches your balance sheet. For technical specifications and a deeper look at our infrastructure, you can consult our Ultimate Guide to Crypto Payment Gateways. By removing the window of exposure, we empower you to offer more payment options without compromising your financial stability.

    Scaling Globally from a UAE Foundation

    Business agility in 2026 depends on instant liquidity and global reach. Our multi-currency support allows international ventures to receive payments in various digital assets while settling in their preferred fiat currency. To further enhance corporate efficiency, the Pallapay Mastercard provides a direct link to your merchant wallet, allowing you to manage corporate expenses using your settled funds immediately. This integration ensures that you aren’t just reacting to the market; you’re leading it. By removing the friction of traditional banking delays, we enable you to avoid crypto volatility for merchants uae while accelerating your journey into the future of payments.

    Securing Your Position in the Future of Payments

    The transition to digital assets is no longer a speculative choice; it’s a strategic evolution for UAE businesses. By implementing the technical architecture of a professional gateway, you can effectively avoid crypto volatility for merchants uae and secure your daily revenue. You’ve learned that instant fiat settlement transforms fluctuating tokens into stable AED or USD deposits. Adhering to the 2026 SCA and ADGM frameworks ensures your license remains protected while you scale your operations across the region. This approach eliminates the risk of price crashes and allows you to meet the growing consumer demand for digital payment options.

    Pallapay provides the institutional reliability your business requires to thrive. We are MSB Registered in the USA and Canada, and we maintain physical offices in major global financial hubs to support our partners. Our proprietary engine ensures instant conversion to fiat currency, removing the technical complexity of manual trades. Empower your business with Pallapay’s Instant Settlement Gateway to join the next generation of global commerce. Your journey toward a secure, high-tech payment infrastructure begins today.

    Frequently Asked Questions

    How do I accept crypto without being affected by price changes?

    You can effectively avoid crypto volatility for merchants uae by utilizing an instant settlement gateway that locks in exchange rates at the moment of checkout. This technology executes a real-time trade, converting the digital asset into AED or USD before the market has a chance to shift. By using this “lock-in” mechanism, the exact value displayed on your customer’s invoice is what arrives in your corporate account, regardless of subsequent price crashes.

    Is it legal for UAE merchants to accept cryptocurrency in 2026?

    Yes, accepting digital assets is fully legal under the UAE’s multi-tiered regulatory framework. The Securities and Commodities Authority (SCA) regulates the mainland, while the Abu Dhabi Global Market (ADGM) and its Financial Services Regulatory Authority (FSRA) govern Abu Dhabi. In April 2026, federal updates to the virtual asset issuance rulebook provided greater clarity, ensuring that compliant businesses can safely integrate these payments into their daily operations.

    What is the fastest way to convert received crypto into AED?

    The fastest method is through an automated fiat settlement engine that provides direct bank transfers. Unlike manual exchanges that can take days, a professional gateway executes the conversion instantly and routes the funds to your UAE bank account. This process ensures that your liquidity remains high and your capital isn’t tied up in volatile digital wallets, allowing you to pay suppliers and staff in local currency without delay.

    Do I need a special bank account to receive crypto settlements?

    You don’t need a specialized “crypto-friendly” bank account if you use a settlement service that pays out in fiat. Because the gateway handles the conversion, the funds arrive at your bank as a standard AED or USD transfer. This allows you to maintain your existing relationships with major UAE financial institutions while still benefiting from the global reach of digital asset payments.

    How much does it cost to implement a crypto payment gateway?

    Implementation costs are generally low, with most providers charging a small percentage per transaction. As of March 2026, Pallapay offers a standard transaction fee of 0% to 1% for merchants in the UAE. In contrast, international providers like BitPay utilize tiered structures, such as 2% plus 25 cents for monthly volumes under $500,000 USD, making local providers a more cost-effective choice for regional businesses.

    Can I accept USDT and Bitcoin at the same physical POS terminal?

    Yes, modern POS terminals are designed to be multi-asset hubs that support a wide range of cryptocurrencies. Whether a customer wants to pay with Bitcoin or a stablecoin like USDT, the terminal generates a unique QR code for that specific asset. This flexibility is a key strategy to manage your daily treasury, as it allows you to prioritize stablecoin settlements for your immediate operational needs.

    What happens if the crypto price drops during a customer transaction?

    Your revenue remains protected by the gateway’s rate guarantee. When a QR code is generated, the exchange rate is fixed for a specific window, typically 15 minutes. Even if the asset’s price drops significantly during that time, the payment processor honors the original rate. This ensures that you receive the full fiat value of the sale, shifting the risk of market movement away from your business.

    Are there tax implications for UAE businesses accepting digital assets?

    UAE businesses are subject to a 9% corporate tax on annual profits exceeding AED 375,000 as of 2026. It’s important to note that crypto transactions remain exempt from the 5% Value Added Tax (VAT). Choosing a gateway to avoid crypto volatility for merchants uae helps maintain accurate records for these filings. Additionally, businesses with annual revenue below AED 3,000,000 can apply for Small Business Relief until December 31, 2026.

    Disclaimer

    The information provided on this website and blog is for general informational and educational purposes only and does not constitute financial, investment, legal, tax, or other professional advice.
    Cryptocurrency and digital asset services may be subject to regulatory restrictions in certain jurisdictions. Users are solely responsible for ensuring compliance with applicable local laws and regulations before using any products or services mentioned on this website.
    PallaPay does not guarantee the accuracy, completeness, or timeliness of any information published and accepts no liability for any loss or damages arising from reliance on the content. Any opinions expressed are those of the respective authors and may change without notice.
    Certain services, features, or products referenced may be provided through third-party partners, licensed entities, or affiliated service providers subject to separate terms and regulatory approvals. Availability of services may vary by country or region.
    This website may contain references to digital assets, virtual currencies, or blockchain-related services that are not available to residents of certain jurisdictions, including where prohibited by law. Nothing on this website constitutes an offer, solicitation, or recommendation to buy or sell any financial instrument or virtual asset.
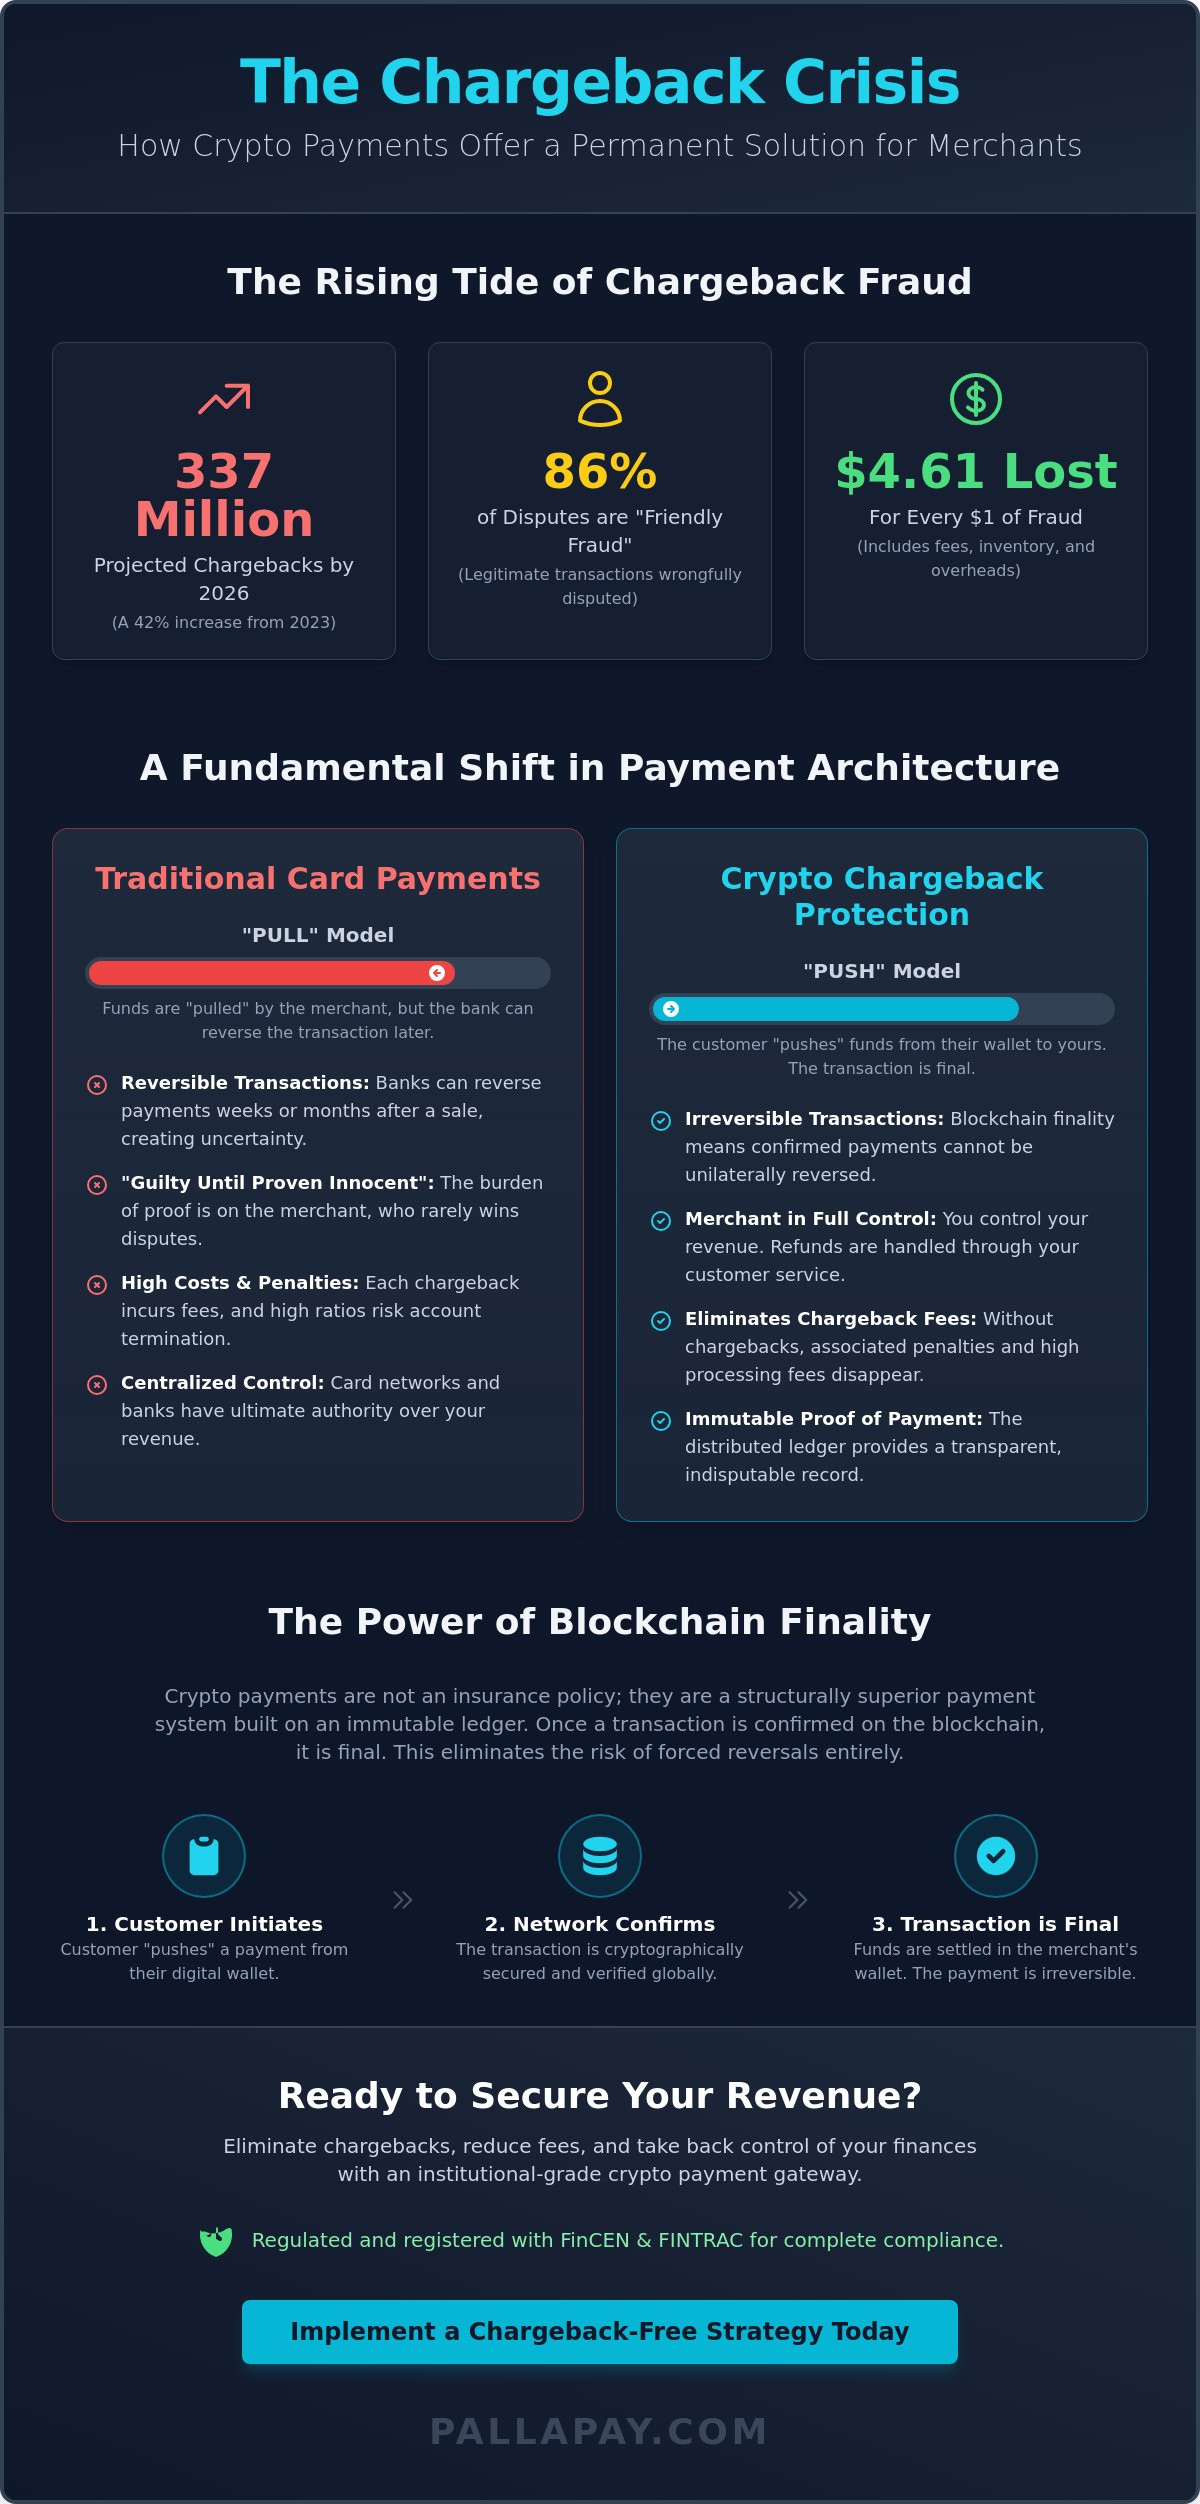
  • Crypto Payment Gateway for Shopify UAE: The Complete 2026 Merchant Guide

    Crypto Payment Gateway for Shopify UAE: The Complete 2026 Merchant Guide

    In 2026, the distinction between a traditional merchant and a digital leader is defined by the ability to process assets with institutional precision. You’ve likely noticed that while the demand for digital currency is surging across the Emirates, the friction of high fees and regulatory hurdles often makes integration feel like a liability. It’s common for businesses to feel overwhelmed by the Capital Market Authority’s Decision No. 4/R.M/2026 or the hidden costs of global providers that drain 3% of every sale through currency conversion.

    This guide empowers you to master the integration of a crypto payment gateway for shopify uae to turn these challenges into a competitive advantage. You’ll learn how to leverage local fintech infrastructure to achieve instant AED settlements and benefit from 0% transaction fees that preserve your business margins. We’ll examine the specific steps to align your store with the latest federal frameworks, ensuring your brand remains a secure, visionary partner in the future of payments.

    Key Takeaways

    • Understand how to leverage the 2026 federal crypto framework to eliminate chargeback fraud and secure your Shopify store’s revenue.
    • Identify the critical criteria for selecting a crypto payment gateway for shopify uae that ensures local compliance and minimizes transaction overhead.
    • Discover the strategic advantage of instant AED settlements, which allow you to convert digital assets into business liquidity without the 7-day delays of global providers.
    • Master the professional integration process to seamlessly connect your merchant dashboard with Shopify using secure, high-speed API protocols.
    • Learn how a unified financial ecosystem bridges the gap between your e-commerce operations and physical retail through integrated crypto POS technology.

    The Rise of Crypto Commerce in the UAE: Why Shopify Merchants are Switching

    The 2026 e-commerce environment in the Emirates is defined by a rapid migration toward decentralized settlement. As the Capital Market Authority’s federal framework provides a clear legal path, merchants no longer view digital assets as peripheral experiments. Integrating a crypto payment gateway for shopify uae has become a prerequisite for capturing market share in a region where a significant portion of retail payments are now settled via blockchain. This evolution is driven by a sophisticated consumer base that demands the same speed in their financial transactions that they experience in every other aspect of their digital lives.

    Traditional payment methods often introduce friction that slows down business growth. High-net-worth individuals across the UAE have transitioned from holding assets to using them as utility currency for luxury goods and daily services. By adopting these technologies, your store signals its status as a visionary partner in the future of payments. It’s a professional bridge that connects your brand with the most liquid and tech-savvy segment of the national economy, ensuring you don’t miss out on high-ticket sales due to legacy banking limits.

    The “No-Chargeback” Advantage for E-commerce

    Chargeback fraud remains a persistent threat to online retailers, often resulting in lost inventory and heavy administrative penalties. Traditional banking systems allow for transaction reversals long after the product has been shipped, leaving the merchant vulnerable to friendly fraud. Blockchain technology eliminates this risk through the principle of transaction finality. Once a customer confirms a payment on the network, the transfer is immutable and cannot be reversed by a central authority or a third-party bank.

    This structural security is vital for merchants in high-value categories like electronics, luxury apparel, or specialized equipment. It creates a predictable cash flow environment where confirmed sales are absolute. Blockchain finality eliminates the cost of payment disputes for UAE vendors, allowing you to focus on scaling operations rather than managing balance sheet risks associated with disputed transactions.

    Tapping into the Abu Dhabi Crypto-Wealth Demographic

    The tech-forward population of Abu Dhabi represents a massive opportunity for Shopify merchants. With the Abu Dhabi Global Market (ADGM) and the Financial Services Regulatory Authority (FSRA) establishing world-class standards, the capital has become a global hub for digital-native wealth. These consumers actively seek out brands that support their preferred financial tools, particularly stablecoins like USDT. Integrating Pallapay for Ecommerce allows you to tap into this affluent demographic seamlessly while maintaining institutional reliability.

    Positioning your store as “crypto-ready” provides an immediate branding advantage in a crowded market. It demonstrates a commitment to innovation that aligns with the UAE’s broader national goals for a digital economy. This strategic move ensures your store captures high-ticket sales that might otherwise be blocked by traditional bank transfer limits or international payment friction. It’s about empowering the user while securing your business margins in a competitive, tech-first landscape.

    How to Choose the Best Crypto Payment Gateway for Shopify in the UAE

    Selecting a crypto payment gateway for shopify uae is a strategic commitment to your company’s liquidity and legal standing. You can’t afford to treat your payment stack as an afterthought. A professional gateway must offer more than just a checkout button; it needs to function as a regulated financial bridge. This means prioritizing providers with established MSB registrations and local banking relationships that facilitate instant conversion. This foundation ensures that your digital sales are converted into business liquidity without the friction of cross-border delays.

    Transaction fees are only one part of the equation. While some global providers advertise low entry rates, they often hide 2% to 3% costs in foreign currency conversion and settlement fees. In contrast, local leaders like Pallapay emphasize direct AED settlement to protect your margins. You should also verify that the provider supports the specific assets your customers use. In the local retail sector, USDT remains the dominant choice for its stability and ease of use. Beyond fees, the technical integration must be seamless. Look for a gateway that offers a native Shopify app or comprehensive documentation for a secure payment API. This ensures your checkout process remains fast and professional, reflecting the high standards of the UAE market.

    Compliance and Regional Regulatory Standards in 2026

    Adhering to local regulations is the only way to ensure long-term business continuity. As of February 2026, the UAE Capital Market Authority (CMA) has implemented a federal framework under Decision No. 4/R.M/2026. This requires virtual asset service providers to meet strict capital requirements, ranging from AED 500,000 to AED 4 million. Using an unregulated offshore gateway puts your local trade license at risk and leaves you with no legal recourse in the event of a dispute. A regulated partner provides the institutional trust necessary to scale your Shopify operations safely. This reliability is why many institutional players look for MSB registrations as a benchmark for security.

    Multi-Currency Support and USDT Dominance

    While Bitcoin and Ethereum are essential, USDT is the preferred medium for commerce across the Emirates. Its peg to the US Dollar provides a level of predictability that volatile assets can’t match. Your gateway should handle the heavy lifting of Fiat Settlement behind the scenes, converting these digital tokens into AED instantly. This process protects your business from market swings during the settlement window. To see how these processes integrate with your existing workflow, you might explore our unified ecosystem for a custom implementation.

    Pallapay vs. Global Alternatives: Why Local Expertise Matters

    Most merchants start their journey with global providers because of familiar branding. It’s a logical first step until you encounter the wall of regional banking friction. Global gateways are primarily designed for Western markets; they often treat the Middle East as a secondary tier. This perspective leads to extended settlement windows and unnecessary compliance hurdles. When you integrate a crypto payment gateway for shopify uae, you need an infrastructure that understands the specific requirements of local financial institutions from day one.

    The difference in settlement speed is the most immediate impact on your operations. While a global provider might require 3 to 7 business days to process a withdrawal to your local account, Pallapay operates on an instant to 24-hour cycle. This speed is essential for maintaining liquidity in a fast-paced retail environment. Beyond speed, there’s the issue of bank rejection. Local banks in the Emirates are often cautious about transfers originating from offshore crypto entities. Working with a regulated local partner ensures that your incoming funds are recognized as legitimate business revenue, providing a clean transaction trail that builds trust with your banking partners.

    High-volume merchants also benefit from our physical presence across the Emirates. Unlike global competitors that offer only digital ticket support, we provide high-touch service through our OTC desks in locations like Abu Dhabi. This physical infrastructure allows for professional, face-to-face support when handling significant liquidity requirements, ensuring you’re never left waiting for a response from a different timezone.

    The Settlement Gap: Getting AED into Your Bank

    Getting funds into an account at a local institution shouldn’t be a struggle. Global gateways often route payments through multiple intermediary banks, adding layers of cost and potential points of failure. We’ve simplified the crypto off-ramp to ensure that your Shopify earnings arrive exactly when you need them. Having a dedicated support team in your own timezone means you aren’t waiting for a Western office to wake up just to resolve a critical payment query. It’s a more efficient way to manage the future of payments.

    Fee Transparency: Avoiding the “Cross-Border” Tax

    Global providers frequently hide an additional 2% to 3% in currency conversion fees when they move funds from USD to AED. This cross-border tax quietly erodes your profits on every transaction. Pallapay provides a direct route for AED conversion, keeping your costs predictable and your margins healthy. This transparent approach is designed to empower merchants rather than penalize them for their geographic location. For a deeper look at how these cost structures impact your bottom line, you can explore The Ultimate Guide to Crypto Payment Gateways for a comprehensive fee comparison.

    Crypto Payment Gateway for Shopify UAE: The Complete 2026 Merchant Guide

    Step-by-Step: Integrating a Crypto Gateway into Your Shopify Store

    Integrating a crypto payment gateway for shopify uae transforms your digital storefront into a high-performance financial hub. The process begins with establishing a verified Pallapay Merchant account. This verification serves as your regulatory foundation, ensuring your business remains compliant with the federal standards implemented in early 2026. Once your identity is confirmed, you gain access to the merchant dashboard, which acts as the command center for your digital liquidity and regional settlement settings.

    The technical handshake between your store and the blockchain occurs through secure API keys. You’ll generate these credentials within your Pallapay dashboard to allow Shopify to communicate transaction data safely. In your Shopify admin, navigate to the “Payments” settings and locate the “Additional Payment Methods” or “Alternative Payments” section. By selecting Pallapay, you enable a checkout experience that mirrors the sophistication of your brand. You can customize the look and feel of the payment interface to ensure a seamless transition for your customers, maintaining trust throughout the final stages of the purchase.

    Testing is a non-negotiable step for institutional reliability. We recommend performing small-value transactions using USDT to verify that the webhook flow is functioning correctly. This ensures that when a customer pays, the order status in your Shopify backend updates from “Pending” to “Paid” without manual intervention. It’s an efficient way to confirm that your automated fulfillment workflows are ready for high-volume traffic.

    Configuring the Pallapay Payment API

    For developers and tech-savvy merchants, the Payment API provides a robust framework for managing the lifecycle of a digital transaction. It handles the nuances of blockchain confirmations, moving orders through the system as soon as the network validates the transfer. Because the UAE is a mobile-first market, our API ensures that every payment screen is fully responsive. This technical precision captures the 95% of local shoppers who prefer completing transactions on their smartphones, ensuring you never lose a sale to technical friction.

    Testing and Go-Live Checklist

    Your go-live phase should be methodical. The “First Transaction” test is your final check to ensure the merchant dashboard reflects real-time data accurately. You should also activate automated fiat settlements at this stage. This feature ensures that your digital revenue is converted to AED instantly, removing the risk of holding volatile assets on your balance sheet. Finally, prepare your customer support team; they should know how to verify transaction hashes on the blockchain to assist customers with payment queries. To start your professional integration today, access our merchant API documentation and secure your place in the future of payments.

    Future-Proofing Your UAE Business with Pallapay’s Unified Ecosystem

    Adopting a crypto payment gateway for shopify uae is a strategic first step, but true market leadership requires a unified financial stack. In the competitive landscape of 2026, successful merchants don’t just look for a plugin; they seek a comprehensive ecosystem that bridges digital innovation with institutional reliability. Pallapay functions as this definitive destination, offering a suite of tools that manage your entire capital lifecycle. This all-in-one approach ensures that your business can scale from a niche online boutique to a global retail powerhouse without switching providers or complicating your financial reporting.

    The future of payments is inherently mobile and accessible. Beyond the digital checkout, we provide the Pallapay Mastercard, which grants you instant access to your business earnings. This allows you to reinvest your revenue or manage operational expenses without waiting for traditional banking cycles. By centralizing your liquidity within a single, secure environment, you eliminate the friction that typically slows down tech-forward enterprises. It’s a professional bridge that connects your digital success to real-world utility, positioning you as a visionary partner in the regional economy.

    Omnichannel Retail: Online and In-Store

    Modern commerce demands a seamless transition between digital and physical storefronts. Our ecosystem allows you to sync your Shopify inventory with physical retail store crypto payments through our advanced Crypto POS Machines. This synergy ensures that whether a customer pays with USDT on your website or at a physical counter in Abu Dhabi, all revenue flows into a single merchant dashboard. Unified reporting simplifies tax and accounting for UAE firms by providing a consolidated view of all digital asset transactions in a standardized format. This clarity is essential for maintaining compliance with the federal frameworks established in early 2026.

    Institutional Liquidity via OTC Desks

    As your Shopify store grows, your liquidity needs will inevitably become more complex. High-volume merchants can utilize our OTC Crypto Exchange services to handle large-scale fiat conversions with minimal market impact. This institutional-grade support is backed by the security of established physical offices within the Emirates, providing merchants with the peace of mind that comes from face-to-face professional service. We handle the heavy lifting of technology and liquidity management behind the scenes, allowing you to focus on your core business growth. Scale your Shopify store with Pallapay today.

    Lead the Evolution of Regional Commerce

    Integrating a crypto payment gateway for shopify uae is no longer an experiment; it’s a strategic move to secure your business liquidity and eliminate the risk of chargeback fraud. You’ve seen how regional regulatory clarity under the 2026 federal frameworks provides a stable foundation for growth. By choosing a partner that prioritizes instant AED settlements, you protect your margins from market volatility and ensure that digital success translates into immediate business capital. This efficiency is the hallmark of a modern enterprise.

    Pallapay bridges the gap between digital assets and institutional finance as a regulated MSB in the United States and Canada. We handle the technical heavy lifting, providing your store with secure API integrations and reliable paths to local bank accounts. It’s time to transform your checkout experience and embrace the future of payments with a partner committed to your long-term expansion. Start Accepting Crypto on Shopify with Pallapay today and join the most innovative merchants in the Emirates. Your journey toward a frictionless financial future begins with a single, secure integration.

    Frequently Asked Questions

    Is accepting crypto on Shopify legal in the UAE in 2026?

    Accepting cryptocurrency is fully legal under the federal framework established by the Capital Market Authority (CMA) in February 2026. Decision No. 4/R.M/2026 provides the specific legal structure for virtual asset service providers to operate within the Emirates. Merchants must ensure they partner with a regulated crypto payment gateway for shopify uae to maintain compliance with these national standards.

    How long does it take to settle crypto payments into my UAE bank account?

    Settlement occurs within a window ranging from instant to 24 hours when using our localized infrastructure. This is a significant improvement over global providers that typically require 3 to 7 business days to process cross-border transfers. Our direct banking relationships in the Emirates facilitate rapid liquidity, ensuring your business capital is always available for operational needs.

    What are the transaction fees for using a crypto payment gateway for Shopify in the UAE?

    Pallapay provides a crypto payment gateway for e-commerce with a 0% transaction fee as of April 2026. This allows merchants to avoid the 2.9% plus AED 1 fees often charged by traditional credit card processors like Stripe. By eliminating the middleman, you preserve your profit margins while only accounting for standard network or withdrawal costs.

    Can I accept USDT on my Shopify store and receive AED?

    You can accept USDT and receive AED directly into your local bank account through our automated conversion system. Our gateway manages the liquidity exchange behind the scenes, converting digital stablecoins into fiat currency at the point of settlement. This process removes the technical burden of manual trading and ensures your revenue is ready for immediate business use.

    Do I need a special license to accept crypto payments on my website in the UAE?

    Merchants generally don’t need a specific virtual asset license if they utilize a regulated third-party gateway provider. Your existing UAE trade license is sufficient for retail operations, provided the gateway handles the underlying regulatory requirements set by the Capital Market Authority. The provider acts as the licensed bridge, managing the heavy lifting of compliance and reporting on your behalf.

    How does Pallapay protect my business from crypto price volatility?

    We protect your revenue by offering instant conversion to fiat currency at the exact moment of the transaction. When a customer pays in a volatile asset like Bitcoin, the system locks in the current exchange rate and converts it to a stable value immediately. This ensures the AED amount settled into your account matches your Shopify product price regardless of market fluctuations.

    Can I use the Pallapay gateway for international Shopify customers outside the UAE?

    The gateway fully supports transactions from international customers regardless of their geographic location. While our settlement is optimized for the local market, your Shopify store can accept digital assets from any global wallet. This provides a seamless payment experience for a worldwide audience, allowing you to scale your brand as a visionary partner in the future of payments.

    Disclaimer

    The information provided on this website and blog is for general informational and educational purposes only and does not constitute financial, investment, legal, tax, or other professional advice.
    Cryptocurrency and digital asset services may be subject to regulatory restrictions in certain jurisdictions. Users are solely responsible for ensuring compliance with applicable local laws and regulations before using any products or services mentioned on this website.
    PallaPay does not guarantee the accuracy, completeness, or timeliness of any information published and accepts no liability for any loss or damages arising from reliance on the content. Any opinions expressed are those of the respective authors and may change without notice.
    Certain services, features, or products referenced may be provided through third-party partners, licensed entities, or affiliated service providers subject to separate terms and regulatory approvals. Availability of services may vary by country or region.
    This website may contain references to digital assets, virtual currencies, or blockchain-related services that are not available to residents of certain jurisdictions, including where prohibited by law. Nothing on this website constitutes an offer, solicitation, or recommendation to buy or sell any financial instrument or virtual asset.
  • How to Accept Crypto Payments in Dubai: The Complete 2026 Merchant Guide

    How to Accept Crypto Payments in Dubai: The Complete 2026 Merchant Guide

    Dubai’s Digital Economy Strategy aims to double the digital sector’s contribution to GDP to 100 billion dollars by 2031, leaving no room for businesses that rely solely on legacy financial systems. To accept crypto payments dubai merchants need a solution that bridges the gap between disruptive innovation and institutional stability. You recognize that your customers demand the flexibility of digital assets, yet the complexity of VARA regulations and the risk of market volatility remain significant barriers to entry. It is a challenge to balance the need for innovation with the necessity of financial security.

    This guide provides the professional clarity you need to integrate cryptocurrency with absolute confidence. We’ll show you how to establish a secure, VARA-compliant payment gateway that offers instant conversion to AED, ensuring your liquidity is never compromised by price swings. You will discover the exact steps to eliminate technical friction and position your brand as a visionary leader in the future of payments. We will explore the seamless transition from digital assets to fiat settlement, covering everything from liquidity management to automated API integrations for a truly global reach.

    Key Takeaways

    • Understand the 2026 VARA regulatory framework to ensure your business remains fully compliant within Dubai’s evolving cashless ecosystem.
    • Discover the seamless process to accept crypto payments dubai merchants use to tap into a global market of high-net-worth digital asset holders.
    • Learn how instant fiat settlement eliminates volatility risks by converting cryptocurrency payments into AED with institutional-grade efficiency.
    • Explore industry-specific integration strategies for luxury real estate and hospitality that streamline high-ticket transactions via specialized OTC desks.
    • Identify the strategic benefits of an all-in-one payment ecosystem to future-proof your business with a regulated, global fintech partner.

    The Regulatory Landscape: Accepting Crypto in Dubai in 2026

    Dubai’s transition to a digital economy reached a critical milestone in 2026. The Dubai Cashless Strategy, launched by the Digital Dubai Office, now targets a 100% digital transaction rate across all government and private sector interactions. This initiative transformed how businesses accept crypto payments dubai, moving digital assets from the fringes of finance into the heart of the city’s commercial infrastructure. The city’s commitment to becoming a global hub for the “Future of Payments” is no longer a goal; it’s a reality that businesses must adapt to for continued growth.

    The Virtual Assets Regulatory Authority (VARA) provides the framework that makes this possible. Established under the Virtual Assets Law of 2022, VARA introduced refined 2026 updates that clarify exactly how merchants can process digital wealth. These updates distinguish between “Proprietary Trading” and “Merchant Services,” ensuring that retail businesses don’t face the same licensing hurdles as major exchanges. While individuals enjoy high levels of freedom, businesses must operate through regulated gateways to maintain legal standing. You can find more detail on the global context of cryptocurrency legality in the UAE and how it compares to other international jurisdictions.

    VARA Compliance for Merchants

    Compliance doesn’t have to be a barrier for your business. The 2026 regulatory updates allow merchants to utilize licensed providers like Pallapay to manage the technical and legal heavy lifting. These providers utilize fiat settlement systems to ensure businesses receive local currency directly into their bank accounts. This setup eliminates the need for the merchant to register as a Virtual Asset Service Provider (VASP). The licensed gateway handles all KYC and AML requirements instantly, whether you use an online API or a crypto POS machine in a physical store. Global trust is further reinforced through MSB (Money Services Business) registrations, ensuring every transaction meets international standards for cross-border commerce.

    Taxation and Legal Clarity in the UAE

    The UAE’s tax environment remains one of the most competitive globally. As of 2026, the 9% corporate tax rate applies to taxable business profits exceeding 375,000 AED, including income derived from crypto transactions. However, individual residents still benefit from a 0% tax rate on personal capital gains from digital assets. For a business to accept crypto payments dubai safely, precise reporting is mandatory. Every transaction must be recorded in the company’s ledger at its fair market value in AED at the time of the trade. This level of clarity has turned 2026 into the definitive year for institutional crypto integration, providing the stability that traditional CFOs require. It’s a professional bridge between the old financial world and the new.

    Technical Integration: Choosing the Right Gateway for Your Business

    Selecting a payment infrastructure requires a shift from fragmented tools to a unified ecosystem. In 2026, merchants don’t have time to manage separate liquidity providers and settlement layers. The ability to accept crypto payments dubai effectively depends on a centralized dashboard that offers instant visibility into cash flow. This all-in-one approach reduces technical debt and simplifies daily reconciliation. High-volume traders specifically require low-latency API connections to execute transactions without price slippage. When a gateway processes thousands of transactions, every millisecond of latency can impact the final settlement value.

    Security is the foundation of institutional trust. Cold storage and multi-sig protocols are non-negotiable requirements for any gateway in the current market. These systems ensure that private keys are never exposed to online vulnerabilities, protecting merchant funds from external threats. For businesses operating within the Dubai International Financial Centre, technical stacks should reflect the standards set by the DFSA Crypto Token framework. This alignment ensures that your operation meets the highest regulatory expectations in the region while maintaining absolute security.

    E-commerce Gateway Integration

    Online merchants must prioritize a frictionless checkout to prevent cart abandonment. Implementing a crypto payment gateway through advanced Payment APIs allows for a white-label experience. This means the payment interface matches your brand’s aesthetic perfectly, keeping the user journey consistent. The e-commerce industry benefits from multi-currency support, which lets global customers pay in various tokens while you receive your preferred settlement currency. It’s the most efficient way to accept crypto payments dubai on a global scale.

    In-Store Physical POS Solutions

    Retail environments demand speed and reliability. Using a personal wallet for business transactions is an amateur approach that creates accounting nightmares. A professional crypto POS machine provides the same level of sophistication as traditional banking hardware. These devices utilize NFC and QR code flows to complete transactions in under 5 seconds. For retail stores in Dubai’s premier malls, having dedicated hardware is essential for maintaining a premium customer experience. It’s The Future of Payments, delivered through a physical interface that consumers already understand. If you’re ready to upgrade your storefront, exploring a dedicated POS solution is the logical next step.

    Instant Fiat Settlement: Converting Crypto to AED

    Volatility remains the primary deterrent for merchants considering digital assets. When you accept crypto payments dubai, a 5% price swing during a transaction can erase your entire profit margin. Pallapay eliminates this risk through fiat settlement, a process that locks the exchange rate at the exact moment of the customer’s checkout. This ensures the amount you see on the invoice is the exact amount that reaches your balance, regardless of market fluctuations that occur after the sale.

    Settlement cycles define your business liquidity. While traditional merchant services often operate on T+2 or T+3 cycles, the 2026 Dubai market demands higher velocity. Pallapay provides Instant settlement options, allowing corporate entities to maintain cash flow without waiting days for funds to clear. For high-volume transactions exceeding 1 million AED, managing liquidity requires a partner capable of deep market depth to avoid slippage. Our infrastructure handles the heavy lifting of global liquidity, providing a secure and stable environment for large-scale commerce.

    The Crypto-to-Bank Transfer Process

    The transition from blockchain to your corporate treasury is a controlled, three-step sequence. First, the customer’s wallet sends the digital asset to the gateway. Second, the system executes an automated conversion at the locked rate. Finally, the funds are dispatched to your bank. By routing through compliant processors, you maintain healthy relationships with institutions like Emirates NBD and Mashreq. This professional layer prevents the account freezes often associated with direct, unverified peer-to-peer transfers, ensuring your financial operations remain seamless and secure.

    Using USDT as a Settlement Bridge

    USDT acts as the primary liquidity bridge for the UAE business ecosystem. Its 1:1 peg to the US Dollar provides a stable medium for merchants who aren’t ready to hold volatile assets. Many Dubai businesses choose to sell USDT for cash or direct bank deposits to simplify their accounting. This method offers superior exchange rates compared to direct Bitcoin-to-AED conversions. It’s a strategic way to accept crypto payments dubai while keeping your books in a currency that matches your local tax and operational obligations. This all-in-one approach transforms complex crypto-fiat conversion into a standard, effortless business operation.

    How to Accept Crypto Payments in Dubai: The Complete 2026 Merchant Guide

    Industry-Specific Use Cases for Dubai Merchants

    Dubai’s economy isn’t a monolith. A boutique in the Dubai Mall has different operational needs than a luxury developer in Business Bay. When you decide to accept crypto payments dubai provides a unique regulatory environment that rewards industry-specific expertise. Pallapay serves as the professional bridge for these sectors, ensuring that blockchain innovation meets institutional financial reliability. Our ecosystem handles the technical friction so you can focus on scale.

    • Luxury Real Estate: Property developers manage high-ticket sales through specialized desks. This process handles the heavy lifting of liquidity and ensures large-cap transactions don’t suffer from price slippage. Developers in the 2024 Dubai Creek Harbour projects require settlements that mirror traditional escrow safety; similarly, global investors can explore Direct Home Purchase for Cash for streamlined liquidity in other markets.
    • Hospitality: Dubai welcomed 17.15 million international visitors in 2023. Leading hotels and tourism providers use digital assets to bypass high cross-border credit card fees and offer Instant booking confirmations.
    • Luxury Retail: High-net-worth individuals in Downtown Dubai expect modern payment flexibility. Accepting digital assets signals that your brand is a visionary partner in the global economy rather than a legacy merchant.
    • Gaming and Entertainment: Speed is the priority for digital entertainment. Fast-tracking micro-transactions for the gaming industry keeps the user experience seamless. The UAE’s gaming market is projected to reach $446 million by 2027, making these Instant capabilities essential for growth.

    High-Volume OTC Solutions

    Standard payment gateways work for retail, but they aren’t built for multi-million dollar property or luxury car sales. When transactions exceed 500,000 AED, merchants should move to an OTC crypto exchange model. This provides discreet, secure settlements for institutional-grade clients. It’s the definitive destination for businesses that need to accept crypto payments dubai and convert large volumes of digital assets into fiat without market disruption. Instant liquidity ensures that your capital remains accessible and stable at all times.

    Customer Loyalty and Retention

    Digital assets are powerful tools for building long-term relationships. Merchants use crypto gift cards to drive repeat business from the global “crypto nomad” demographic. These individuals contributed to a global crypto market cap that peaked over $2.5 trillion in 2024. Rewarding customers with digital assets in a compliant manner attracts tech-savvy spenders to your Dubai location. It’s not just a payment method; it’s The Future of Payments and a key driver of modern commerce. This strategy transforms a one-time buyer into a loyal advocate for your brand.

    Future-Proofing Your Business with Pallapay

    Choosing the right partner determines whether your transition to digital assets is a hurdle or a competitive edge. Pallapay acts as the professional bridge between traditional commerce and the blockchain ecosystem. As a regulated Money Services Business (MSB) with operations spanning North America and the Middle East, we provide the institutional reliability required for modern enterprise. When you decide to accept crypto payments dubai, you aren’t just adding a checkout option; you’re integrating into a global liquidity network that operates 24/7.

    Efficiency drives our infrastructure. Merchants can utilize the Pallapay Mastercard to bridge the gap between digital revenue and corporate expenses. This card enables instant access to funds for vendor payments or operational costs, bypassing the multi-day delays typical of legacy banking. Getting started is a streamlined process: local entity registration, technical integration via our API or POS hardware, and processing your first live transaction. Most businesses complete this cycle in under 24 hours, ensuring no downtime for your sales team.

    The All-in-One Merchant Dashboard

    The dashboard provides a centralized command center for your entire financial operation. You can track global sales and settlements in real-time across various digital currencies. For businesses managing 10 or more branches, the interface allows for granular control of multiple POS locations from a single login. The system generates tax-compliant reports that align with Dubai’s regulatory requirements, making the preparation for FTA audits straightforward and data-driven.

    Expert Support and Local Presence

    Our commitment to your success extends beyond digital software. We maintain physical OTC desks in Business Bay, offering face-to-face consulting for high-volume transactions and strategic planning. Technical support remains active 24/7 to ensure 99.9% uptime for your payment gateway. This local presence ensures that as you accept crypto payments dubai, you have a visionary partner available to handle technical complexities while you focus on scaling your brand. We don’t just provide a service; we build a strategic partnership for long-term digital asset management.

    • Instant Settlements: Convert crypto to fiat immediately to avoid market volatility.
    • Global Reach: Accept payments from customers anywhere in the world without cross-border fees.
    • Secure Infrastructure: Benefit from institutional-grade security protocols and MSB-regulated compliance.

    Secure Your Competitive Edge in Dubai’s Digital Economy

    Dubai’s status as a global financial hub is solidified by its 2026 regulatory framework, making it essential for local merchants to adapt. To accept crypto payments dubai businesses must prioritize secure gateways that offer instant AED settlement to eliminate volatility risks. By choosing a partner with a physical presence in the Binary Tower, Business Bay, you ensure institutional-grade support and localized expertise. Every transaction should be a seamless bridge to growth rather than a technical hurdle.

    Pallapay bridges the gap between traditional commerce and blockchain innovation. We’re a regulated MSB in the USA and Canada, providing a foundation of absolute trust for every merchant we serve. Our platform was voted Best Crypto OTC and Payment Gateway at multiple global fintech summits, proving our utility for high-volume businesses. It’s time to transition from legacy systems to a streamlined, all-in-one ecosystem that handles the technical heavy lifting for you. This transition ensures your business remains a leader in the global marketplace.

    Empower your Dubai business with Pallapay; the future of payments starts here.

    We look forward to scaling your business in the new digital era.

    Frequently Asked Questions

    Is it legal to accept cryptocurrency for business in Dubai?

    Yes, accepting cryptocurrency for business is legal in Dubai under the Virtual Assets Regulatory Authority (VARA) framework established in March 2022. Merchants can legally process digital assets by partnering with licensed virtual asset service providers. This regulatory structure ensures that businesses remain compliant with anti-money laundering (AML) and counter-terrorism financing (CTF) standards. By following these established guidelines, your business can safely integrate digital currencies into its daily operations.

    How do I convert crypto payments into Emirati Dirhams (AED)?

    You can convert crypto payments into Emirati Dirhams (AED) instantly through a licensed payment gateway or an over-the-counter (OTC) desk. These platforms automate the exchange process by locking in real-time rates at the moment of transaction. Once the conversion is complete, the system transfers the fiat currency directly to your local bank account. This automated approach eliminates the risk of market volatility and ensures you receive the exact Dirham value of your sale.

    What are the fees for accepting crypto payments in Dubai?

    Transaction fees for businesses that accept crypto payments dubai generally range from 0.5% to 2% based on 2024 industry averages. These costs are often lower than the 3% or higher fees associated with traditional credit card processors. Merchants may also encounter network fees, often called “gas fees,” which vary depending on the specific blockchain used for the transaction. Choosing a provider with a transparent fee structure helps you maintain predictable profit margins.

    Do I need a special license to accept Bitcoin or USDT?

    You don’t usually need a specific virtual asset license to accept Bitcoin or USDT if you utilize a third-party provider that is already licensed by VARA. However, your existing trade license from the Dubai Department of Economy and Tourism (DET) or a relevant Free Zone must allow for your specific business activities. It’s essential to consult with your legal advisor to ensure your commercial license covers the receipt of digital assets through an authorized gateway.

    Can I accept crypto payments for real estate transactions in the UAE?

    Yes, you can accept crypto payments for real estate transactions provided the process involves a licensed intermediary and follows Circular No. 6 of 2022 from the Dubai Land Department. The buyer typically transfers the digital assets to a regulated exchange, which then settles the funds in AED to the developer or escrow account. This process ensures that all high-value property transfers remain transparent and fully compliant with UAE financial regulations.

    How long does it take to settle crypto funds into my bank account?

    Settlement times for crypto funds typically range from 24 to 48 hours for standard bank transfers within the UAE. Some advanced payment gateways offer near-instant settlement options for specific stablecoins like USDT. The exact duration depends on the internal processing times of your banking partner and the specific liquidity provider you use. Fast settlement cycles allow you to maintain healthy cash flow while offering modern payment alternatives to your customers.

    Which cryptocurrencies are most commonly used by customers in Dubai?

    Bitcoin (BTC), Ethereum (ETH), and Tether (USDT) are the three most frequently used cryptocurrencies in the Dubai market as of 2025. USDT is particularly popular for retail transactions because its value is pegged to the US Dollar, which provides price stability for both the merchant and the consumer. Many businesses that accept crypto payments dubai prioritize these three assets to cater to the widest possible range of digital-native shoppers.

    What happens if a customer wants a refund on a crypto payment?

    You should issue refunds based on the original Emirati Dirham (AED) value of the transaction at the time of purchase. This protects your business from losing money if the cryptocurrency’s market price has increased since the sale. Most payment gateways include a built-in refund tool that calculates the correct amount of crypto to return based on current exchange rates. Clear refund policies help manage customer expectations and maintain professional standards in every transaction.

    Disclaimer

    The information provided on this website and blog is for general informational and educational purposes only and does not constitute financial, investment, legal, tax, or other professional advice.
    Cryptocurrency and digital asset services may be subject to regulatory restrictions in certain jurisdictions. Users are solely responsible for ensuring compliance with applicable local laws and regulations before using any products or services mentioned on this website.
    PallaPay does not guarantee the accuracy, completeness, or timeliness of any information published and accepts no liability for any loss or damages arising from reliance on the content. Any opinions expressed are those of the respective authors and may change without notice.
    Certain services, features, or products referenced may be provided through third-party partners, licensed entities, or affiliated service providers subject to separate terms and regulatory approvals. Availability of services may vary by country or region.
    This website may contain references to digital assets, virtual currencies, or blockchain-related services that are not available to residents of certain jurisdictions, including where prohibited by law. Nothing on this website constitutes an offer, solicitation, or recommendation to buy or sell any financial instrument or virtual asset.
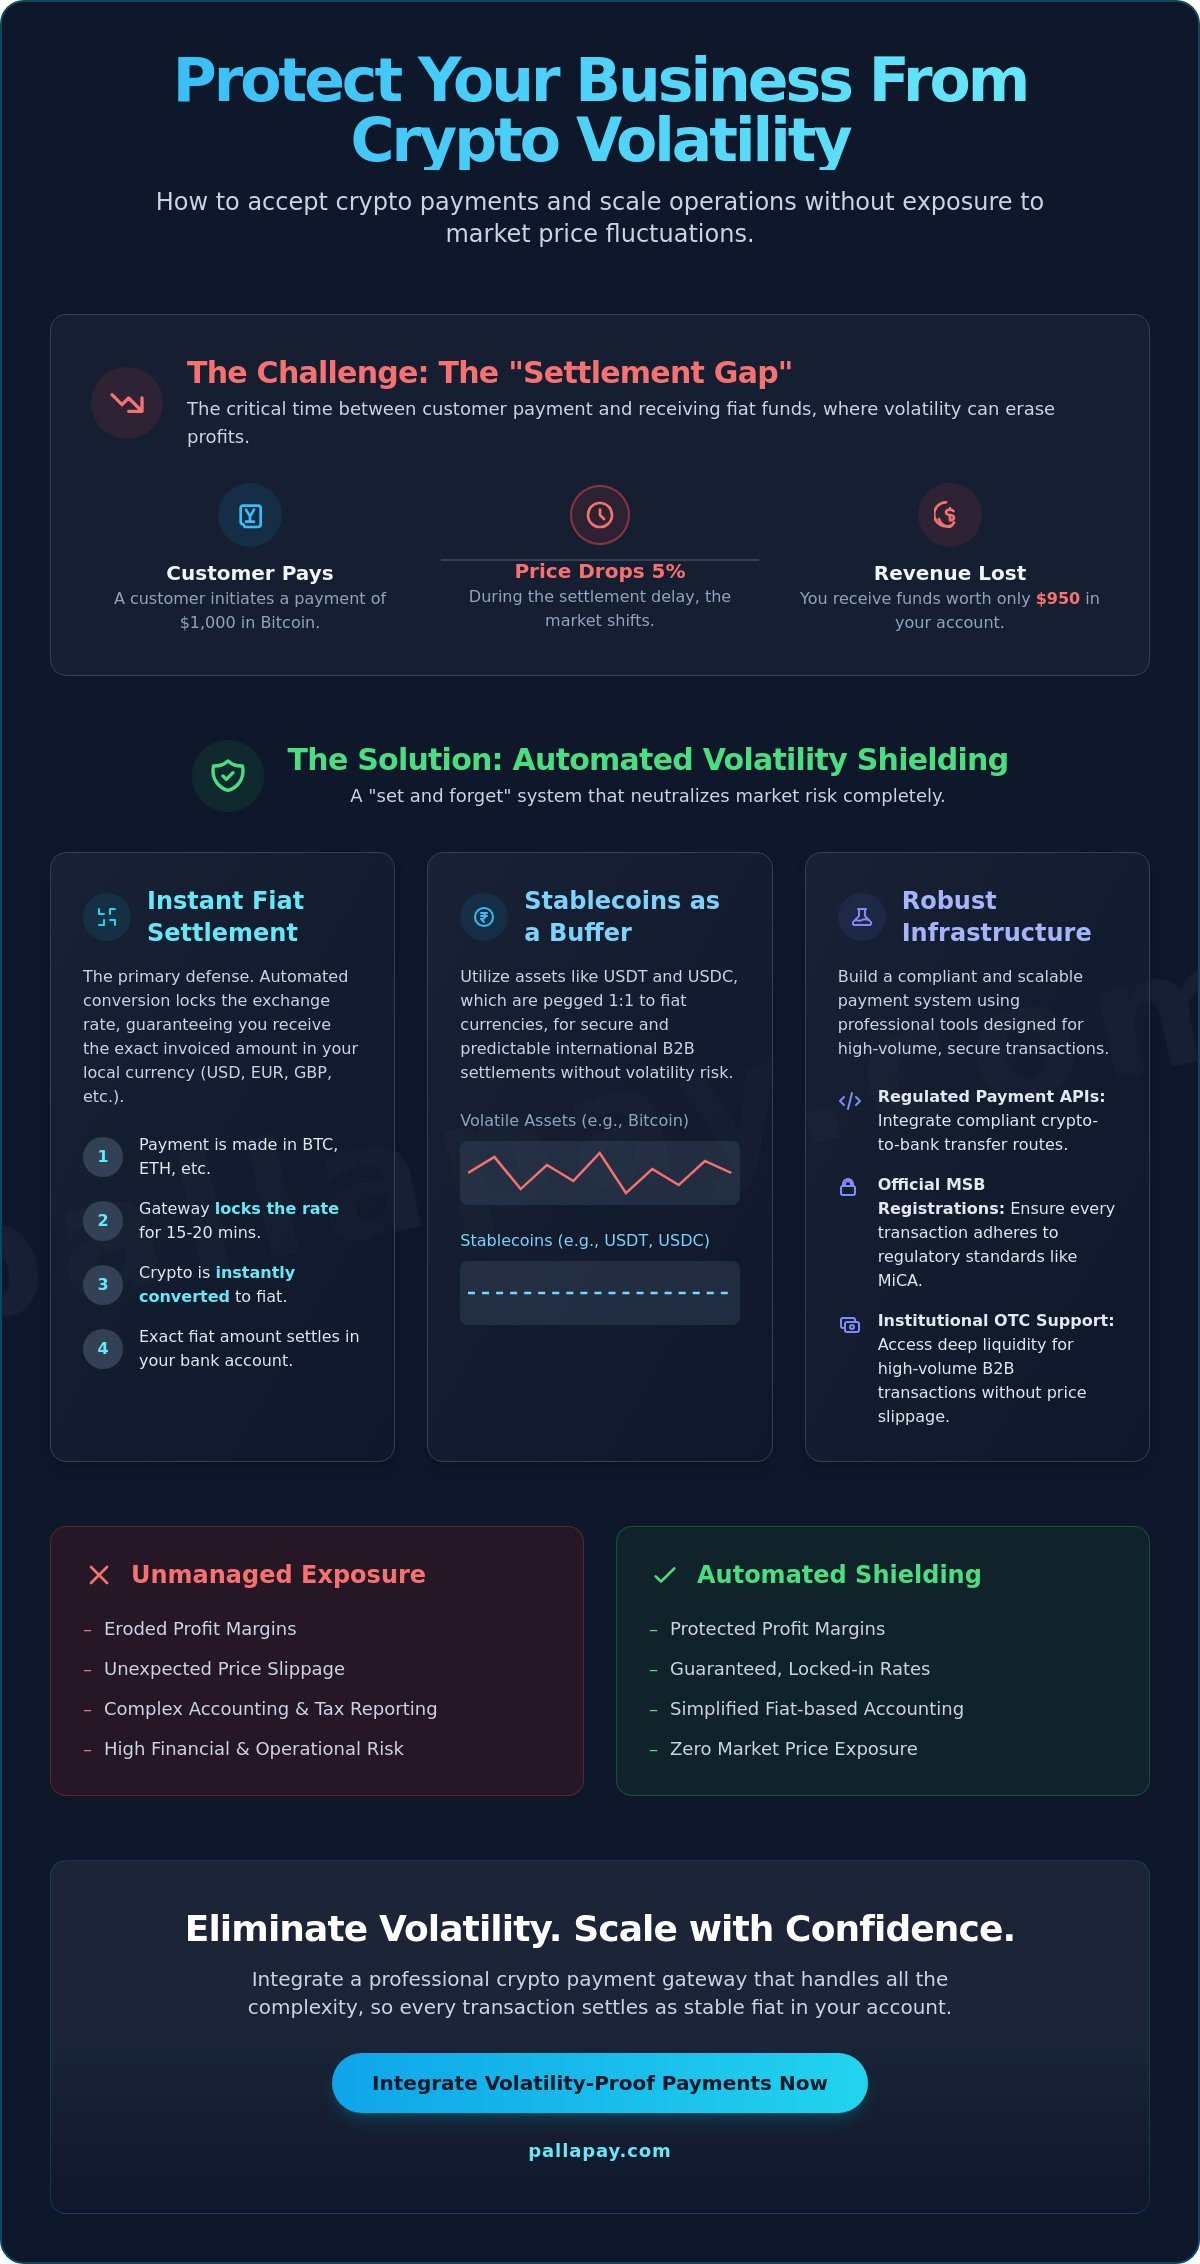
  • Crypto to Fiat Settlement: The 2026 Strategic Guide for Global Merchants

    Crypto to Fiat Settlement: The 2026 Strategic Guide for Global Merchants

    A business operating on a T+3 settlement cycle in 2026 is essentially functioning in the past while its competitors move at the speed of light. You’ve likely felt the frustration of watching market prices shift during the long wait for funds to clear your traditional bank account. It’s a common struggle; over 70% of global merchants report that the bridge between digital innovation and legacy finance is often paved with high fees and confusing MSB regulations. This guide provides a definitive roadmap to mastering crypto to fiat settlement, transforming what was once a complex hurdle into a streamlined, instant advantage for your enterprise.

    We’ll show you exactly how to eliminate price volatility risks and secure lower transaction costs than standard credit card networks. You’ll gain a comprehensive understanding of how to implement audit-ready reporting and instant conversion technology that scales across borders. This breakdown prepares your business to leverage the future of payments with absolute confidence and institutional reliability.

    Key Takeaways

    • Understand how to transition from holding digital assets to utilizing them as high-speed payment rails for modern global commerce.
    • Learn how advanced payment gateways lock in real-time exchange rates to eliminate price volatility during the conversion process.
    • Master the strategic choice between instant and batch crypto to fiat settlement to optimize your business cash flow and minimize bank fees.
    • Identify the regulatory gold standards, including MSB registration and AML protocols, required to protect your institutional financial integrity.
    • Discover how to bridge the gap between digital and physical commerce using an all-in-one ecosystem of gateways and crypto POS machines.

    What is Crypto to Fiat Settlement and Why It Matters in 2026

    Crypto to fiat settlement is the automated process of converting digital assets from a customer transaction into traditional currency and depositing it directly into a corporate bank account. While early adopters historically focused on holding assets for long-term appreciation, 2026 represents a fundamental shift toward utility. Global commerce now utilizes blockchain as a high-speed payment rail rather than a speculative instrument. This transition allows enterprises to tap into a $3 trillion global market while maintaining their existing accounting standards and functional currency.

    Modern technology has effectively solved the price fluctuation problem that once deterred traditional retailers. By leveraging a professional Cryptocurrency Exchange infrastructure, payment gateways now offer Instant conversion at the point of sale. This ensures that the value of a transaction remains fixed from the moment the customer pays until the funds reach the merchant’s ledger. It’s a secure bridge that connects decentralized innovation with institutional financial reliability.

    The Evolution of Merchant Settlement

    The industry has matured from manual exchange transfers to automated, API-driven gateway settlements. Settlement latency is the time delay between a customer’s payment and the availability of funds in the merchant’s bank account, which can severely restrict operational liquidity if not managed through real-time conversion. Modern providers now handle the heavy lifting by absorbing volatility risk during the transaction window. This evolution ensures that a business receives the exact fiat amount listed on its invoice, regardless of market movements during the crypto to fiat settlement process.

    Key Benefits for Modern Enterprises

    Enterprises adopting a crypto to fiat settlement strategy gain immediate competitive advantages over those relying solely on legacy systems. One primary benefit is the total elimination of chargeback fraud, a problem that continues to cost global merchants billions annually in traditional credit card processing. Additionally, blockchain-based settlements significantly lower cross-border fees when compared to the 50-year-old SWIFT banking network. This efficiency is particularly attractive for businesses targeting high-net-worth individuals. Sectors like luxury real estate and international hotels are already using these tools to provide seamless experiences for a growing demographic of crypto-affluent travelers who demand modern payment flexibility.

    The Mechanics: How Crypto-to-Fiat Conversion Works

    The transition from a customer’s digital wallet to a merchant’s bank account involves a sophisticated backend process that removes technical friction. When a transaction initiates, the payment gateway captures the current market price and freezes it for a specific window, typically lasting 15 to 20 minutes. This ensures the crypto to fiat settlement remains consistent even if the market fluctuates seconds later. By locking these rates, businesses avoid the risk of receiving less value than the sticker price of their goods or services, effectively neutralizing the 10% to 15% intraday swings common in digital assets.

    Behind the scenes, the gateway communicates with deep liquidity pools to execute the exchange. This is essential for high-volume trades where a lack of depth could lead to price slippage. As highlighted by payment experts in the whitepaper Crypto Payments: From Virtuality to Real Use Case, the move toward practical merchant adoption relies on these robust settlement layers that bridge decentralized finance with traditional banking.

    The Gateway vs. The Liquidity Provider

    The gateway serves as the professional interface, while the liquidity provider acts as the financial engine. Automated market makers (AMMs) and over-the-counter (OTC) desks provide the necessary fiat depth to handle large-scale enterprise transactions without delay. These entities work in tandem to ensure that even a million-dollar transaction doesn’t disrupt the market price. In high-volume settlement, the spread between the buy and sell price is more important than the commission fee because it directly impacts the final net amount received.

    API Integration and Automated Workflows

    Modern businesses scale by removing manual steps from their financial operations. Using payment APIs allows companies to embed this technology directly into their existing infrastructure. For ecommerce platforms, this means crypto to fiat settlement happens automatically the moment a purchase is confirmed.

    Merchants can set “Auto-Settlement” rules to convert incoming assets into their preferred local currency instantly. All activity is tracked through a comprehensive merchant dashboard crypto, providing real-time reporting and financial clarity. This level of automation turns a complex technological hurdle into a standard business process. To see how this fits your business model, you can review the benefits of a dedicated fiat settlement solution.

    Crypto to Fiat Settlement: The 2026 Strategic Guide for Global Merchants

    Comparing Settlement Methods: Instant vs. Batch vs. Stablecoin

    Selecting a settlement strategy is a critical decision for any enterprise integrating digital assets. The right choice balances speed against operational costs. A business’s ability to manage a crypto to fiat settlement determines its overall exposure to market shifts. Organizations typically choose between three primary models based on their liquidity needs and transaction volume.

    • Instant Settlement: This method converts digital assets at the exact point of sale. It eliminates price risk by locking in the exchange rate immediately. The merchant receives the precise fiat value displayed at checkout, regardless of market movements ten minutes later.
    • Batch Settlement: This approach consolidates daily transactions into a single transfer. It is a strategic choice for high-volume retail environments. By aggregating 500 individual sales into one daily settlement, businesses reduce recurring bank transfer fees by up to 90%.
    • Stablecoin Settlement: Many global firms choose USDT or USDC as their primary rail. This allows them to keep funds in a digital format that is pegged to the dollar, providing the speed of blockchain with the stability of fiat.
    • Direct to Bank Model: This handles the final mile of the process. It ensures that converted funds reach local bank accounts through established financial networks, bypassing the traditional 3 to 5 day wait associated with international wires.

    Same-Day Settlement vs. Traditional T+2

    Traditional banking systems rely on T+2 or T+3 settlement cycles. These legacy delays often trap capital for 48 to 72 hours. Modern fiat settlement products bypass these hurdles by utilizing blockchain’s 24/7/365 availability. While a traditional bank closes on Friday afternoon, blockchain rails continue to move value. This means weekend revenue is available for use on Monday morning rather than Wednesday. It’s a fundamental shift that provides businesses with superior cash flow management and immediate access to working capital.

    The Stablecoin Bridge Strategy

    High-volume entities often require rapid transitions between digital and physical liquidity. In major financial hubs, selling USDT for cash dubai has become a standard procedure for managing large-scale B2B payouts. This strategy is efficient for companies that need to pay international suppliers without waiting for slow SWIFT transfers. Stablecoins offer a level of transparency that traditional bank statements don’t provide. Every transaction is recorded on a public ledger, allowing for real-time audits. This transparency simplifies the crypto to fiat settlement process, as every dollar equivalent is accounted for on-chain before it ever hits a local bank account.

    By choosing the correct settlement rhythm, a business doesn’t just accept payments; it optimizes its entire financial operation. Pallapay acts as the professional bridge, ensuring these technical processes remain invisible to the end user while providing the merchant with absolute stability.

    Evaluating a Settlement Provider: Compliance and Security

    Selecting a partner for crypto to fiat settlement requires a rigorous audit of their legal standing and operational integrity. MSB (Money Services Business) registration represents the non-negotiable gold standard for institutional reliability. These licenses ensure the provider operates under strict financial oversight, which protects your capital from the inherent risks of unregulated markets. KYC (Know Your Customer) and AML (Anti-Money Laundering) protocols aren’t merely administrative hurdles; they’re essential defense mechanisms for your brand. By verifying every participant in the transaction chain, providers prevent illicit funds from entering your ecosystem, shielding your business from the 2024 surge in global regulatory enforcement actions.

    Fee transparency separates global fintech leaders from opaque startups. You’ll typically encounter two primary models: flat transaction fees and percentage spreads. A flat fee provides predictable costs for high-volume operations, whereas percentage spreads can often mask the true cost of liquidity. It’s vital to demand clear security disclosures regarding the conversion window. Top-tier providers use deep liquidity pools to lock in rates the moment a transaction initiates, ensuring that the price you see is the price you receive without slippage.

    • Regulatory Standing: Verify active MSB status in Tier-1 jurisdictions.
    • Risk Mitigation: Ensure robust AML screening is integrated into the API.
    • Cost Clarity: Compare the total cost of ownership between flat and spread-based models.
    • Fund Protection: Review the provider’s custody and insurance protocols during the settlement gap.

    Navigating Global Regulations

    US and Canadian MSB registrations serve as a hallmark of trust for global enterprises, ensuring compliance with the latest 2023 FATF standards. Businesses operating in retail stores must prioritize regulated partners to ensure long-term operational continuity and avoid bank account closures. Regulatory Arbitrage is the risky practice of selecting jurisdictions with weak oversight to bypass compliance; businesses should avoid it to prevent sudden asset freezes or legal liability. Professional providers bridge the gap between blockchain innovation and institutional finance.

    The Strategic Implementation Guide

    Consulting a crypto pos machine for business helps brick-and-mortar setups align their physical hardware with digital settlement speeds. Your chosen infrastructure must scale to handle peak volumes, such as the 40% increase in transaction density often recorded during global retail events. Reliable providers maintain a local presence in major financial hubs to offer real-time support and localized expertise. This ensures the future of payments remains a standard, effortless part of your daily operations.

    Secure your revenue stream and eliminate market risk by integrating our instant fiat settlement solution today.

    The Pallapay Advantage: An All-in-One Settlement Ecosystem

    Pallapay operates as a sophisticated bridge between disruptive blockchain technology and institutional financial reliability. The platform provides a unified environment where digital payment gateways link directly with physical crypto pos machines to ensure a frictionless experience for every stakeholder. By maintaining regulated operations in the USA, Canada, and the UAE, Pallapay offers a secure framework that supports global expansion without the compliance hurdles typically associated with digital assets. It’s a system built for scale and stability.

    Liquidity remains the most critical factor in any crypto to fiat settlement strategy. Pallapay addresses this through a hybrid network of automated online systems and physical OTC desks. This infrastructure ensures that whether a business is processing a small retail transaction or a multi-million dollar corporate transfer, the funds are available when needed. The ecosystem currently serves a diverse range of industries, providing specialized support for gaming platforms, high-end retail, and international hospitality groups.

    Bridging Physical and Digital Commerce

    Modern merchants need the ability to accept crypto in store without waiting days for bank clearances. Pallapay enables businesses to receive digital payments and complete a crypto to fiat settlement within the same hour. This rapid turnaround protects profit margins from market swings. For immediate access to capital, the Pallapay Mastercard allows merchants to spend their settled fiat funds at millions of locations worldwide. Large-scale corporate entities often require more personalized service, which is where the otc crypto exchange comes into play. These desks facilitate high-volume trades with deep liquidity, ensuring that institutional moves don’t suffer from price slippage or execution delays.

    The Future of Payments is Instant

    Pallapay removes the heavy lifting of complex technology for non-technical merchants. You don’t need to be a blockchain expert to modernize your payment stack. By consolidating the gateway, POS hardware, and fiat settlement into a single partnership, Pallapay eliminates the fragmentation that slows down business growth. This all-in-one approach provides a clear audit trail and a simplified user experience. It’s not just about adding a new payment method; it’s about evolving with the global economy. The future of payments is instant, secure, and professional. Optimize your business with Pallapay’s fiat settlement solutions today and secure your place in the new financial era.

    Future-Proof Your Global Commerce Strategy

    The financial landscape of 2026 demands a transition from traditional barriers to frictionless liquidity. High-growth merchants are moving away from legacy batch processing in favor of real-time efficiency to maintain a competitive edge. Mastering crypto to fiat settlement isn’t just a technical upgrade; it’s a strategic necessity for capturing global market share. Success requires a partner that bridges the gap between digital innovation and institutional reliability.

    Pallapay provides this bridge as a regulated MSB in both the USA and Canada. By leveraging an official MSB registration and a robust global OTC presence, businesses can access instant settlement across 180+ countries. This infrastructure eliminates the volatility risks typically associated with digital assets while ensuring full compliance with international standards. It’s time to integrate a solution that treats complex conversions as standard business operations.

    Scale your business with Pallapay’s professional fiat settlement solutions and secure your position in the future of payments. The tools for your global expansion are ready when you are.

    Frequently Asked Questions

    How long does crypto to fiat settlement take?

    Crypto to fiat settlement occurs instantly or within 24 hours depending on your chosen payout method. Pallapay processes these transactions in real-time to eliminate the risk of market fluctuations. While traditional bank transfers might take 1 to 3 business days, our internal ecosystem ensures liquidity is available immediately. This speed allows your business to maintain a steady cash flow without waiting for legacy banking cycles.

    Is crypto to fiat settlement taxable for my business?

    Tax obligations for your transactions depend on your specific jurisdiction and local tax laws. In regions like the UAE, corporate tax rates of 9% apply to businesses exceeding certain profit thresholds as of June 2023. You should consult with a certified financial advisor to ensure compliance with VAT and income reporting requirements. We provide detailed transaction logs to simplify your accounting and audit processes.

    Can I receive settlement in my local currency like AED, USD, or EUR?

    You can receive settlements in over 30 global currencies including AED, USD, and EUR. Our platform bridges the gap between digital assets and traditional finance by providing direct conversion into your preferred local tender. This flexibility ensures you avoid unnecessary exchange fees and can pay your local suppliers or employees without friction. It’s a key feature for businesses looking to scale internationally.

    What are the fees associated with crypto to fiat conversion?

    Fees for conversion are calculated based on your monthly transaction volume and the specific digital assets being processed. We prioritize transparency by displaying all costs before you finalize a transaction. This approach prevents hidden charges from impacting your profit margins. By using a professional gateway, you access institutional liquidity rates that are typically more favorable than standard retail exchanges.

    Do I need a special bank account to receive fiat settlements?

    You don’t need a specialized crypto bank account to receive your funds. Pallapay facilitates transfers directly to your existing corporate or personal bank account via standard SEPA or SWIFT protocols. This integration makes the transition from blockchain technology to traditional banking feel like a standard business operation. It ensures your current financial infrastructure remains compatible with the future of payments.

    Is it possible to settle payments in stablecoins instead of fiat?

    Businesses can choose to settle their transactions in stablecoins such as USDT or USDC to maintain digital liquidity. This option provides the stability of fiat currencies while retaining the speed and low cost of blockchain transfers. It’s an ideal solution for companies that operate globally and want to avoid the delays of the traditional banking system. You can switch between fiat and stablecoin settlements within your dashboard settings.

    How does a crypto payment gateway handle price volatility during a sale?

    Our gateway handles price volatility by locking the exchange rate at the exact moment of the transaction. This ensures the merchant receives the precise fiat amount regardless of market shifts that occur seconds later. By providing an instant crypto to fiat settlement, we remove the financial risk associated with digital asset price swings. This mechanism protects your revenue and provides the stability needed for predictable financial planning.

    What documents are required for a business to start using fiat settlement?

    Businesses must provide a valid trade license, proof of address, and identification for all beneficial owners to begin using the service. These requirements comply with global Anti-Money Laundering standards and the 2018 FATF recommendations for virtual asset service providers. Once your documentation is verified, your account is activated for full settlement capabilities. This rigorous onboarding process establishes the trust and security required for institutional financial operations.

    Disclaimer

    The information provided on this website and blog is for general informational and educational purposes only and does not constitute financial, investment, legal, tax, or other professional advice.
    Cryptocurrency and digital asset services may be subject to regulatory restrictions in certain jurisdictions. Users are solely responsible for ensuring compliance with applicable local laws and regulations before using any products or services mentioned on this website.
    PallaPay does not guarantee the accuracy, completeness, or timeliness of any information published and accepts no liability for any loss or damages arising from reliance on the content. Any opinions expressed are those of the respective authors and may change without notice.
    Certain services, features, or products referenced may be provided through third-party partners, licensed entities, or affiliated service providers subject to separate terms and regulatory approvals. Availability of services may vary by country or region.
    This website may contain references to digital assets, virtual currencies, or blockchain-related services that are not available to residents of certain jurisdictions, including where prohibited by law. Nothing on this website constitutes an offer, solicitation, or recommendation to buy or sell any financial instrument or virtual asset.