Tag: T+0 Settlement

  • Crypto to Fiat: Transforming Forex and Gold Profits into Real-World Wealth

    Crypto to Fiat: Transforming Forex and Gold Profits into Real-World Wealth

    Your ability to predict a gold breakout or a currency shift is only half the battle. The true measure of a professional trader is how quickly that digital gain becomes spendable wealth. You’ve likely felt the sting of seeing XAU/USD profits trapped behind slow bank processing or eroded by slippage during large-scale conversions. It’s a common frustration to master the markets only to be held back by the friction of traditional finance when you’re ready to exit a position.

    This guide shows you how to master the mechanics of instant crypto to fiat settlement to seamlessly transition your professional Forex and Gold CFD trading gains into liquid, usable capital. With gold trading near $4,450 per ounce in August 2026 and the U.S. Federal Reserve maintaining rates in the 3.50% to 3.75% range, the need for efficient liquidity is critical. We’ll explore the regulated frameworks like the GENIUS Act and the SEC proposal for Regulation Crypto Assets that provide the security you require. You’ll learn how to navigate T+0 settlement cycles and utilize deep liquidity pools to ensure your hard-earned profits are ready for the real world without unnecessary delay.

    Key Takeaways

    • Master the mechanics of instant crypto to fiat settlement to ensure your high-volume trading gains are converted without the systemic delays of traditional banking.
    • Explore how to leverage currency volatility and gold’s status as a premier hedge to build sustainable, real-world wealth through strategic CFD trading.
    • Identify strategies to minimize the hidden costs of settlement, such as slippage and wide spreads, by utilizing institutional-grade liquidity providers.
    • Understand the necessity of a regulated, MSB-compliant bridge to maintain financial security and transparency during large-scale profit liquidations.
    • Discover how a professional ecosystem, including tools like the Pallapay Mastercard, creates a seamless workflow from market exit to immediate spending.

    Understanding Crypto to Fiat Settlement in the 2026 Trading Landscape

    Settlement is the mechanism that transforms digital market gains into tangible, bankable liquidity. In the 2026 financial environment, this process isn’t just a technical swap; it’s the heartbeat of modern professional trading. High-volume CFD traders have shifted from speculative holding to strategic utilization of their capital. When you secure a profit on a gold breakout or a USD currency shift, that value remains theoretical until it’s successfully off-ramped into traditional currency. The evolution of cryptocurrency to fiat settlement has turned what was once a complex hurdle into a standard business operation.

    Stablecoins like USDT and USDC serve as the essential intermediary bridge in this landscape. They allow you to lock in gains from volatile Forex or XAU/USD positions without immediately exiting the digital ecosystem. By using a professional instant crypto to fiat settlement service, you can move from these stable digital pegs into your bank account with minimal friction. This ensures that your trading success translates directly into real-world purchasing power or reinvestment capital.

    The Mechanics: How Digital Assets Become Bankable Capital

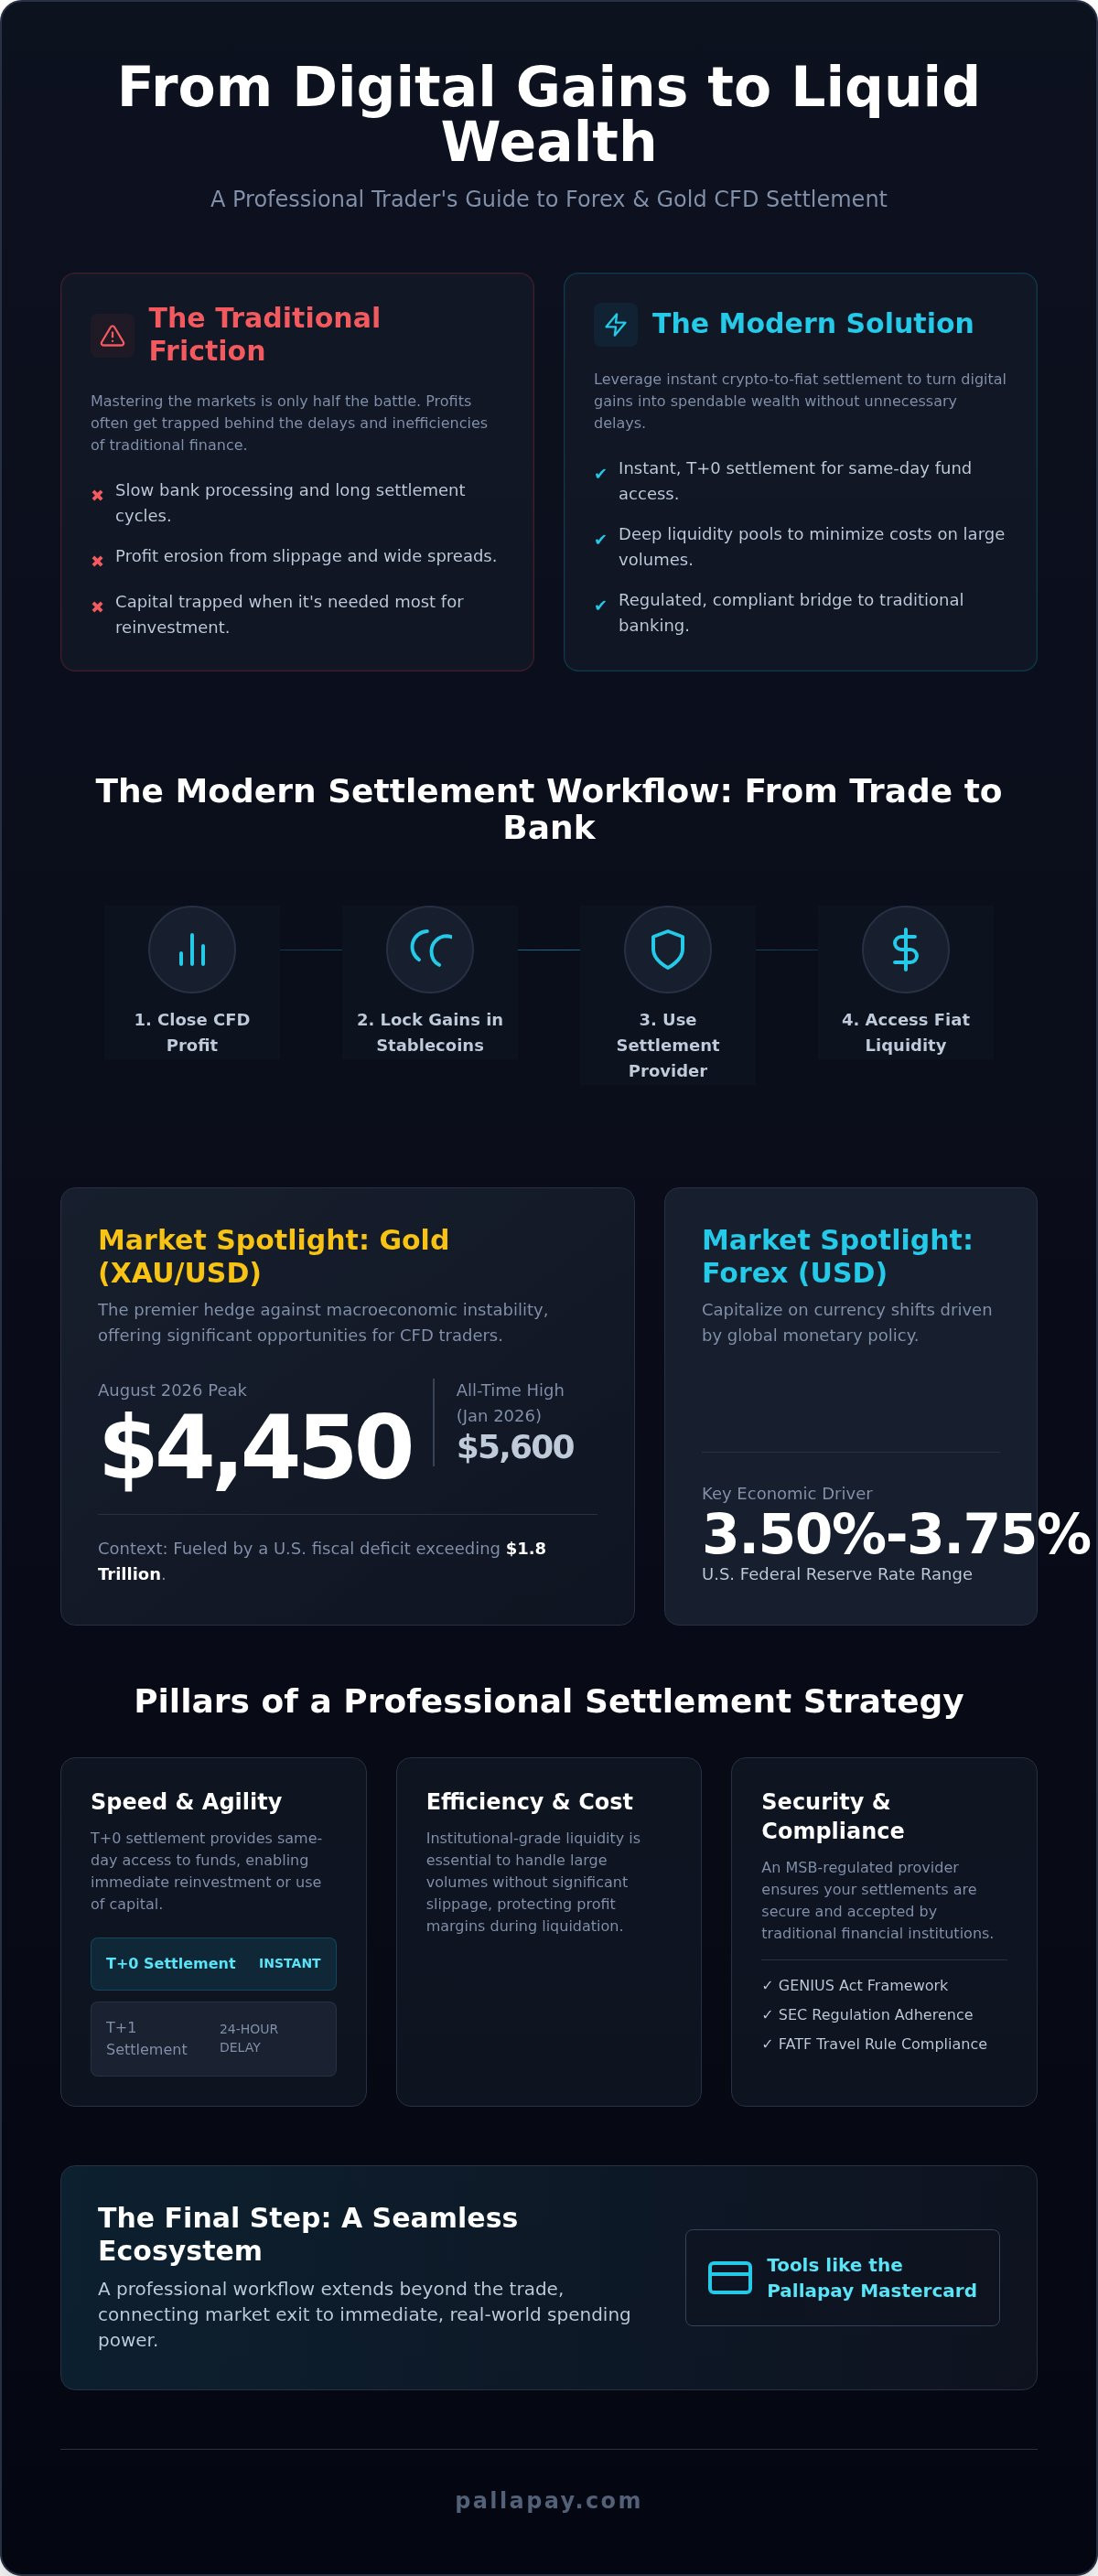
    The transition from a trading wallet to a bank account follows a precise technical flow. Once you close your CFD positions, your digital assets are transferred to a settlement provider. This provider utilizes institutional liquidity pools to execute the conversion. Liquidity depth refers to the market’s capacity to handle large transaction volumes without causing a significant change in the exchange price, which directly determines the efficiency of your final settlement. High-depth providers prevent the slippage that often eats into the margins of professional traders during large liquidations.

    Why Timing and Compliance Dictate Your Success

    The distinction between T+0 and T+1 settlement cycles is the difference between immediate opportunity and stalled progress. T+0 settlement provides same-day access to funds, while T+1 forces a 24-hour waiting period that can disrupt your operational cash flow. Speed must be balanced with institutional reliability. Using an MSB-regulated provider ensures that your high-value settlements comply with the FATF Travel Rule, which is a requirement for traditional banks to accept incoming transfers without freezing funds.

    Current U.S. frameworks, such as the GENIUS Act, have brought much-needed clarity to stablecoin reserves and settlement procedures. These regulations mean your off-ramp activities are backed by high-quality assets and transparent protocols. When your settlement partner operates within these legal boundaries, your trading gains are treated with the same legitimacy as any other corporate financial transaction, providing you with a secure bridge between disruptive innovation and established financial systems.

    The Transformative Power of Forex and Gold (XAU/USD) CFD Trading

    Professional CFD trading represents a paradigm shift in how individuals generate and manage wealth. By capitalizing on the inherent volatility of global markets, disciplined traders turn price fluctuations into substantial financial opportunities. This transformative potential isn’t merely about the technical execution of a trade; it’s about the strategic ability to move that generated value into the real-world economy. For the modern professional, success is defined by the seamless transition from a closed market position to liquid capital.

    Mastering the XAU/USD Market for Wealth Generation

    Gold (XAU/USD) remains the premier choice for traders seeking a hedge against macroeconomic instability. In August 2026, gold reached a two-month peak of approximately $4,450 per ounce, reflecting its role as a safeguard against a U.S. fiscal deficit that exceeded $1.8 trillion. While the all-time high of $5,600 set in January 2026 remains a benchmark for the asset’s potential, current volatility provides ample room for profit. Using CFDs allows for significant leverage, which can accelerate the path to major financial milestones. However, these high-leverage positions require a reliable exit strategy to ensure that gains are preserved during the liquidation process.

    Forex Trading: The Global Engine of Liquidity

    The Forex market acts as a global engine of liquidity, offering constant opportunities through major currency pairs. With the U.S. Federal Reserve maintaining interest rates in the 3.50% to 3.75% range as of August 2026, the USD remains a central focus for those exploiting interest rate differentials and monetary policy shifts. Successful traders rely on real-time data to execute precise entries and exits, yet the final hurdle is often the speed of the off-ramp. Transitioning these gains into usable funds is where many traditional systems fail to keep pace with the 24/7 nature of digital markets.

    This is why professional traders are increasingly turning to instant crypto to fiat settlement to manage their capital. This infrastructure removes the friction typically associated with high-volume liquidations, allowing you to move from a digital gain to a bankable status in minutes. As the global framework for digital asset regulation matures, having a regulated partner ensures that your financial transformation is both rapid and compliant. Utilizing a sophisticated fiat settlement solution ensures your trading success translates directly into tangible financial freedom.

    Overcoming the Liquidity Barrier: Why Settlement Infrastructure Matters

    High-volume CFD trading requires a robust infrastructure to handle the transition from digital gains to bankable wealth. Retail exchanges often fail during peak volatility, leading to excessive slippage that compromises your trading strategy. Institutional-grade gateway infrastructure offers a level of stability that retail exchanges simply cannot match. By integrating a professional instant crypto to fiat settlement workflow, you eliminate the uncertainty of delayed bank processing. Gold is a liquid asset, but converting XAU/USD profits through a standard wallet often introduces hidden costs that many traders overlook. These costs include network fees, platform commissions, and wide spreads that erode your hard-earned margins.

    Minimizing FX Risk During Market Conversions

    Real-time conversion engines are essential for locking in exchange rates during periods of high market activity. Market volatility, such as the 3.6% gain gold saw in the third week of August 2026, can significantly impact your final execution price if settlement isn’t handled immediately. The spread functions as a cost in a crypto-to-USD conversion by representing the gap between the bid and ask prices at the time of the transaction. Utilizing an instant crypto to fiat settlement service ensures that the price you see is the price you receive, shielding your capital from the erratic movements typical of the digital asset space.

    Scalability for High-Volume Investors

    Scaling your operations from a $10,000 liquidation to a $1,000,000 transaction requires a provider with institutional depth. Standard retail gateways often struggle with massive CFD profit liquidations, causing price impact that further reduces your returns. Dedicated settlement partners provide physical OTC desks for these high-volume conversions, offering a stable and discreet alternative to automated retail exchanges. While automated gateways are efficient for routine transactions, the manual oversight of an OTC desk ensures that institutional-grade liquidations are executed without disrupting market prices. This infrastructure acts as the professional bridge between digital market success and traditional financial stability, allowing you to focus on the transformative potential of your trading strategies.
    Crypto to Fiat: Transforming Forex and Gold Profits into Real-World Wealth

    Strategic Financial Transformation: From Digital Gains to Fiat Stability

    Trading isn’t just about the numbers on a screen; it’s about the lifestyle those numbers build. To achieve a true financial transformation, you need a workflow that effectively moves gains from the broker to your everyday life. This cycle of trade, settle, spend, and reinvest creates a sustainable loop of professional growth. Integrating an instant crypto to fiat settlement protocol into your routine turns digital market volatility into tangible stability. Moving profits into “hard” fiat currency provides the psychological security needed to maintain a high-performance trading mindset.

    Efficiency remains the priority for high-volume traders. Integrating settlement APIs into your personal or business dashboard reduces the manual labor of capital management and minimizes errors. You can access these funds immediately through the Pallapay Mastercard, which connects your settled balance to global payment networks. This eliminates the multi-day wait times associated with traditional banking off-ramps, ensuring your wealth is always within reach. It’s a professional bridge that connects your digital success to the physical economy.

    Diversification and Long-Term Capital Preservation

    Success in the XAU/USD market provides the seed capital for broader diversification. Rebalancing your portfolio between high-leverage CFDs and stable fiat reserves protects you from sudden market reversals. Many professional traders use their fiat settlement proceeds to fund traditional investments like real estate or equity markets. In 2026, meticulous record-keeping is vital for tax compliance. Maintaining a clear audit trail of every instant crypto to fiat settlement ensures your wealth remains transparent and legally secure.

    Global Accessibility: Settling Funds Anywhere in the World

    A global settlement network serving over 180 countries empowers you to manage an international lifestyle without borders. Traditional remittances often carry high costs and slow delivery times that disrupt cash flow. Crypto-based settlement bypasses these legacy inefficiencies, allowing for rapid cross-border capital movement at a fraction of the cost. Whether you’re funding operations in a new market or managing personal expenses abroad, the speed of modern infrastructure keeps your capital mobile and productive. This level of accessibility is the final piece of the professional trader’s toolkit.

    To automate your professional workflow, explore how our API for crypto payments can streamline your high-volume settlements.

    Pallapay: The Professional Standard for Crypto-to-Fiat Settlement

    Pallapay has established itself as the definitive bridge between disruptive digital assets and institutional financial reliability. For professional traders navigating the high-stakes world of Forex and Gold CFDs, a reliable partner for liquidating gains is a necessity, not a luxury. This platform provides a comprehensive ecosystem designed for strategic capital movement, offering everything from payment APIs to physical OTC desks for high-volume institutional liquidations. Professional traders choose this infrastructure because it prioritizes speed and security, ensuring that the transformative potential of market success is never hindered by technical friction.

    Whether you’re liquidating profits from a sustained gold rally or a successful currency pair trade, the need for deep liquidity is paramount. Pallapay specializes in these high-volume conversions, providing a stable environment where large-scale trades are handled with professional precision. By facilitating instant crypto to fiat settlement, the platform allows you to move capital at the speed of the market, bypassing the multi-day delays common in retail-level exchanges. This institutional reliability is the foundation upon which successful trading careers are built.

    Regulated Security for Your Digital Assets

    MSB registration in the USA and Canada provides a layer of protection that unregulated entities cannot offer. This status signifies a commitment to global financial standards, protecting your capital from the systemic risks associated with offshore platforms. Pallapay maintains strict adherence to AML and KYC protocols, ensuring that your high-value settlements are compliant with the evolving legal landscape of 2026. For a more comprehensive look at safeguarding your wealth, refer to our Crypto Security guide.

    Seamless Integration for Modern Commerce

    The ecosystem extends beyond individual trading, bridging the gap for ecommerce and retail operations that require real-time liquidity. A unified dashboard provides a clear view of all settlement and conversion history, allowing for efficient capital management and simplified record-keeping. This integrated approach ensures that every transaction is documented and accessible, providing the transparency required for modern commerce. It’s a sophisticated solution that makes complex financial flows feel like standard, effortless business operations.

    Start your settlement journey with Pallapay today to experience a professional standard of financial mobility and secure your trading gains with confidence.

    Secure Your Financial Evolution with Institutional Liquidity

    Transitioning from high-performance trading to bankable stability is the final step in a successful financial journey. You’ve mastered the volatility of the gold market and the complexities of currency pairs; now you need an infrastructure that matches your pace. By utilizing instant crypto to fiat settlement, you ensure that your trading gains aren’t just numbers on a screen but liquid capital ready for reinvestment or lifestyle enhancement. This strategic shift from digital gain to fiat stability is what separates hobbyists from professional wealth builders.

    Pallapay provides this professional bridge with official MSB registrations in the USA and Canada. Speed defines your edge. With global support for over 180 countries, it offers the real-time conversion capabilities that professional Gold and Forex traders demand. This regulated environment protects your capital while providing the efficiency necessary for modern commerce. It’s time to leverage an ecosystem that understands the depth of institutional liquidity and the importance of frictionless exits.

    Secure your trading profits with Pallapay’s regulated fiat settlement solutions. Your success in the global markets deserves a settlement partner that is as ambitious and efficient as your own trading strategy.

    Frequently Asked Questions

    What is crypto to fiat settlement and how does it differ from a simple exchange?

    Settlement is the institutional process of converting digital assets into bankable currency for immediate use. While a simple exchange might just swap one asset for another within a platform, settlement ensures the funds move out of the digital ecosystem and into the traditional financial system. It involves liquidity management and regulatory compliance to ensure that high-volume trading gains from Gold CFDs become usable capital in a global bank account.

    How long does it take for settled funds to reach my bank account?

    Settlement times depend on the specific region and banking network; however, professional providers prioritize T+0 or T+1 cycles. An instant crypto to fiat settlement aims for real-time processing, often completing in under five minutes for supported currencies. This speed is essential for Forex traders who need to maintain liquid cash flow to capitalize on market shifts. Always verify the specific settlement window for your region to ensure it aligns with your operational requirements.

    Is it possible to settle crypto profits directly to a debit card?

    Yes, professional ecosystems allow you to link your converted profits to physical spending tools. The Pallapay Mastercard is a primary example, enabling you to access settled funds immediately for global transactions. This bypasses the traditional wait times associated with bank transfers. It’s a highly efficient solution for individual traders who want to spend their XAU/USD gains or manage international lifestyle expenses without the friction of legacy banking delays.

    What are the tax implications of crypto-to-fiat settlement in 2026?

    Converting digital assets into fiat currency is generally a taxable event in most jurisdictions. In 2026, regulations like the GENIUS Act in the U.S. emphasize the need for transparent record-keeping and reserve reporting. Since every settlement constitutes a realization of profit or loss, you should maintain a detailed audit trail of your conversion history. Consult with a qualified tax professional to understand how these settlements impact your specific financial obligations and regulatory filings.

    Can I settle high volumes of USDT from Forex trading without slippage?

    High-volume liquidations require deep liquidity pools to prevent slippage from eroding your margins. Professional settlement processors utilize institutional-grade infrastructure and physical OTC desks to handle large USDT conversions without impacting market prices. This is critical when exiting leveraged gold positions where even a small price movement can result in significant losses. Using a dedicated settlement partner ensures that your execution price remains stable, regardless of the transaction size.

    Are crypto settlement providers regulated like traditional banks?

    While they aren’t banks, top-tier providers are regulated as Money Service Businesses (MSB) in major jurisdictions like the USA and Canada. This status requires them to adhere to strict AML and KYC standards, providing a level of security that unregulated exchanges lack. This regulatory framework ensures that your instant crypto to fiat settlement is handled with institutional reliability. It provides the necessary bridge for traditional financial institutions to accept your incoming funds without compliance concerns.

    What is the difference between a crypto wallet and a settlement processor?

    A crypto wallet is designed for the storage and basic transfer of digital assets, whereas a settlement processor is a functional bridge to the traditional economy. Processors handle the complex background mechanics of liquidity sourcing, currency conversion, and bank-grade reporting. While a wallet keeps your assets in the digital space, a processor actively moves that value into the fiat system. This distinction is vital for traders who need professional infrastructure to manage high-volume CFD gains.

    How do spreads affect the final amount I receive in my bank account?

    The spread is the difference between the buy and sell price of an asset, and it acts as a direct cost during conversion. In a crypto-to-fiat transaction, a wider spread means you receive less traditional currency for your digital assets. Professional providers offer tighter spreads by tapping into institutional liquidity, ensuring more of your Forex profit reaches your account. Minimizing this gap is essential for maintaining the profitability of your overall trading strategy.

    Disclaimer

    The information provided on this website and blog is for general informational and educational purposes only and does not constitute financial, investment, legal, tax, or other professional advice.
    Cryptocurrency and digital asset services may be subject to regulatory restrictions in certain jurisdictions. Users are solely responsible for ensuring compliance with applicable local laws and regulations before using any products or services mentioned on this website.
    PallaPay does not guarantee the accuracy, completeness, or timeliness of any information published and accepts no liability for any loss or damages arising from reliance on the content. Any opinions expressed are those of the respective authors and may change without notice.
    Certain services, features, or products referenced may be provided through third-party partners, licensed entities, or affiliated service providers subject to separate terms and regulatory approvals. Availability of services may vary by country or region.
    This website may contain references to digital assets, virtual currencies, or blockchain-related services that are not available to residents of certain jurisdictions, including where prohibited by law. Nothing on this website constitutes an offer, solicitation, or recommendation to buy or sell any financial instrument or virtual asset.
  • How to Choose a Crypto Payment Processor: A 2026 Stakeholder Guide

    How to Choose a Crypto Payment Processor: A 2026 Stakeholder Guide

    With crypto transactions now accounting for up to 26% of total revenue at merchants that have adopted the technology, the decision to integrate digital assets is no longer a speculative experiment. It is a strategic necessity for global commerce. However, for most organizations, the primary hurdle isn’t interest; it’s the challenge of knowing how to choose a crypto payment processor that satisfies legal, financial, and technical stakeholders. You likely feel the pressure to innovate while facing internal resistance regarding price volatility and the evolving regulatory landscape of 2026.

    This guide empowers you to master a strategic framework for selecting a partner that offers institutional-grade security and seamless utility. We’ll provide a defensible business case to help you secure executive buy-in and a vetting checklist to ensure your chosen provider handles complex background processes with absolute reliability. By the end of this article, you’ll have a clear roadmap for launching a low-risk pilot program that bridges the gap between disruptive technology and established financial practices. We will move quickly from high-level value propositions to the functional evidence required for a successful transition.

    Key Takeaways

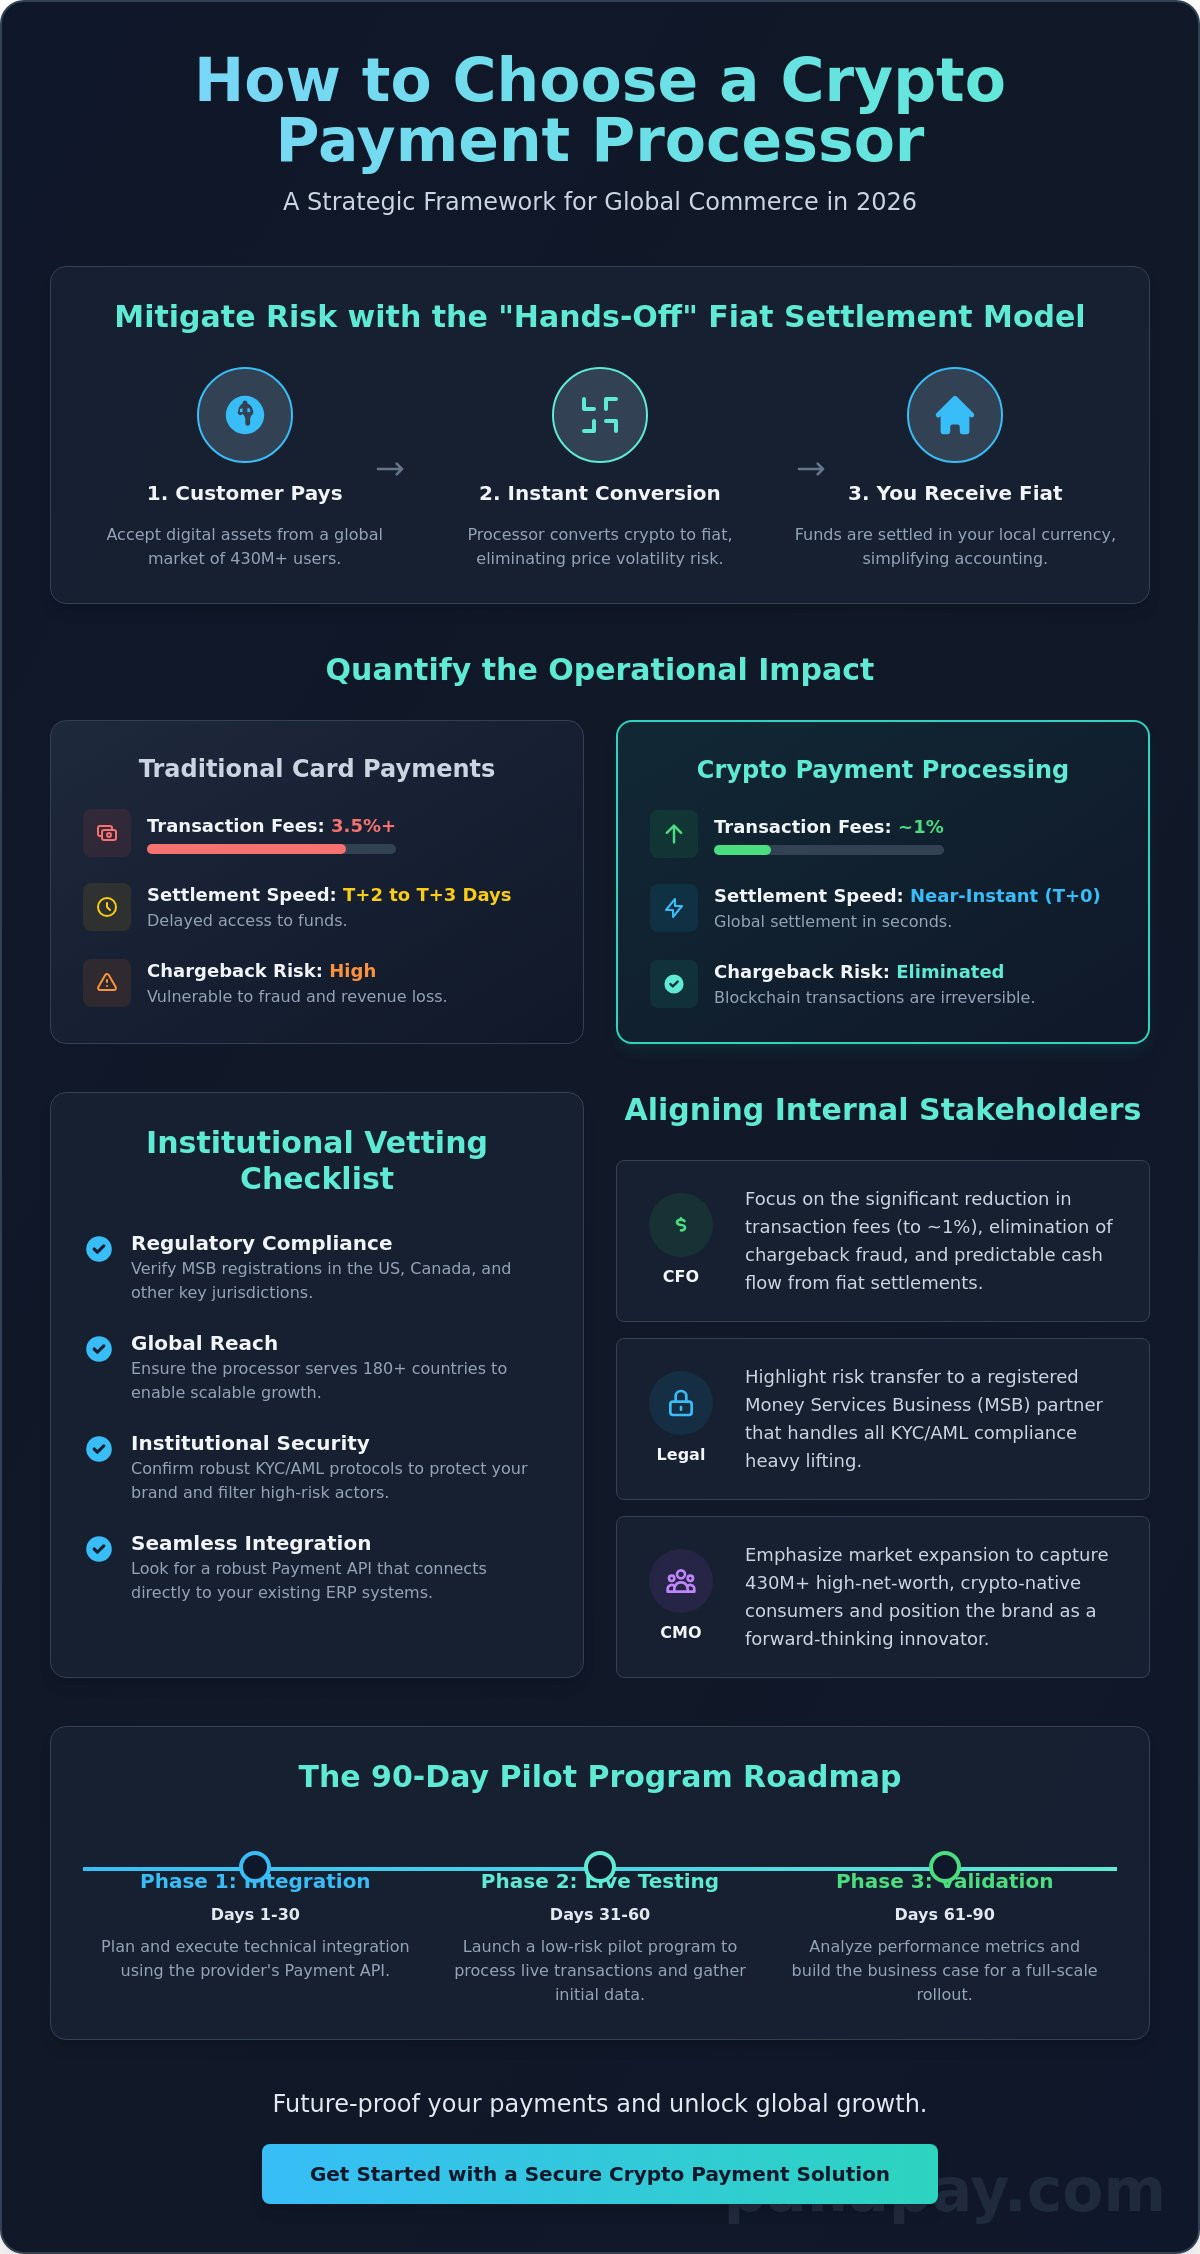
    • Identify how to align internal decision-makers by presenting the “hands-off” settlement model that eliminates price volatility risks for the organization.
    • Master the criteria for how to choose a crypto payment processor by verifying institutional-grade security and MSB registrations across major global jurisdictions.
    • Quantify the operational impact of switching to digital asset processing, including a significant reduction in transaction fees and achieving near-instant T+0 global settlement.
    • Streamline your technical transition using a robust Payment API that integrates directly with existing ERP systems for a frictionless operational flow.
    • Design a structured 90-day pilot program to validate performance metrics and transition from theoretical planning to live, low-risk commercial reality.

    Defining the Strategic Need: Stakeholder Mapping and the “Hands-Off” Model

    By 2026, digital assets have transitioned from speculative investments into a critical layer of the global financial infrastructure. For an enterprise, the decision to integrate these assets isn’t about joining a trend; it’s about optimizing the settlement layer of the business. Understanding how to choose a crypto payment processor requires a shift in perspective. You aren’t just looking for a technical plug-in. You’re selecting a strategic partner that functions as a modern payment service provider, bridging the gap between blockchain innovation and institutional requirements.

    The most successful implementations in 2026 utilize the “Hands-Off” model. This approach allows your business to capture the benefits of decentralized finance without the volatility risks. You accept digital assets from global customers, but your internal treasury never touches the tokens. Instead, the processor facilitates an immediate conversion, ensuring your books remain denominated in traditional currency. This eliminates the need for complex digital asset accounting while still accessing a global market of over 430 million crypto users. It’s a professional bridge that connects established practices with modern advancements.

    The Role of Fiat Settlement in Risk Mitigation

    Institutional stability relies on predictable cash flow. A robust fiat settlement system acts as the essential bridge between blockchain speed and banking stability. This approach simplifies tax reporting because every transaction has a clear fiat value at the moment of sale. It fits perfectly into standard accounting workflows, removing the hurdle of fluctuating balance sheets that often stalls executive approval. By receiving local currency directly, you maintain financial reliability while offering your customers the cutting-edge utility they expect.

    Tailoring the Message for Each Stakeholder

    Securing internal buy-in requires speaking the language of each department. The CFO needs to see how crypto reduces cross-border friction. Traditional international card fees often exceed 3.5%, but crypto processing typically sits near 1%. Additionally, the elimination of chargeback fraud provides a direct boost to the bottom line. Mastering how to choose a crypto payment processor means identifying a partner that satisfies these diverse departmental needs simultaneously.

    Your Legal team will focus on risk transfer. They want a partner that is a registered Money Services Business (MSB) to handle the heavy lifting of compliance. Meanwhile, the CMO will be interested in market expansion. Accepting crypto allows the brand to capture high-net-worth, crypto-native consumers who prioritize privacy and speed. By framing the choice as a multi-departmental win, you transform a technical request into a strategic business case that drives long-term growth.

    Vetting Compliance and Security: The Institutional Checklist

    Institutional trust is built on a foundation of rigorous regulatory adherence and technical resilience. When evaluating how to choose a crypto payment processor, the first point of verification must be the provider’s legal standing in key financial markets. A reputable partner should hold Money Services Business (MSB) registrations in major jurisdictions, specifically the United States and Canada. These registrations signify that the entity operates under the supervision of federal financial intelligence units, providing a necessary layer of accountability for your legal department.

    A global footprint is equally vital for modern commerce. A processor capable of serving 180+ countries ensures that your business can scale without encountering regional payment silos. This expansive reach must be paired with institutional-grade KYC (Know Your Customer) and AML (Anti-Money Laundering) protocols. These systems don’t just satisfy regulators; they protect your brand by filtering out high-risk actors before they interact with your ecosystem. Blockchain transparency actually enhances these efforts, as it allows for real-time tracking of asset provenance in ways traditional banking cannot match.

    Regulatory Compliance as a Corporate Shield

    Operating within a regulated framework transforms compliance from a hurdle into a competitive advantage. A processor that manages the complexities of global financial laws effectively offloads the regulatory burden from your internal teams. By partnering with a registered MSB, you ensure that every transaction adheres to the latest global standards. Blockchain transparency facilitates a new era of accountability where immutable ledgers provide definitive proof of funds and transaction history for auditing purposes.

    Institutional Security Standards

    Technical resilience is the second pillar of the vetting process. You should look for providers that prioritize advanced crypto security measures such as multi-signature authorization and cold storage for asset protection. Unlike traditional payment systems that rely on vulnerable centralized databases, blockchain utilizes cryptographic immutability to secure transaction data. Implementing a reliable Crypto Payment Gateway allows you to automate these security checks seamlessly. To assess a provider’s technical strength, use this essential checklist:

    • Proven Longevity: Does the provider have a documented history in the fintech sector dating back to at least 2018?
    • Infrastructure: Are assets kept in air-gapped cold storage rather than hot wallets?
    • Redundancy: Does the system feature multi-signature protocols to prevent single points of failure?
    • Global Reach: Can the provider facilitate transactions and settlements across 180+ countries?

    Choosing a partner with a long-standing reputation in the industry ensures that your transition to digital payments is secure and sustainable. Assessing these factors carefully is the definitive way to understand how to choose a crypto payment processor that will serve as a reliable strategic facilitator for your organization’s growth.

    Quantifying the Value Proposition: Fees, Speed, and Global Reach

    Selecting a partner isn’t just a technical hurdle; it’s a fiscal optimization strategy. When you evaluate how to choose a crypto payment processor, the most immediate metric is the impact on your bottom line. Traditional international credit card transactions often carry fees exceeding 3.5% once cross-border surcharges and currency conversion costs are tallied. In contrast, crypto processing fees typically hover around 1%. For high-ticket ecommerce operations, this 2.5% delta translates directly into preserved margins and increased competitive agility.

    The total cost of ownership (TCO) extends beyond the transaction fee. A sophisticated partner eliminates the hidden costs of traditional finance, such as setup delays and recurring maintenance charges for legacy hardware. By adopting an integrated digital infrastructure, you replace fragmented payment silos with a unified flow. This efficiency is a core component of the “Hands-Off” model discussed earlier, where the complexity of the background process is handled entirely by the provider, leaving you with clean, predictable fiat results.

    The Financial Impact of Instant Settlement

    Institutional liquidity depends on the velocity of capital. While traditional systems rely on the multi-day SWIFT cycle, crypto enables a “T+0” reality. This means funds are available for operational use almost immediately after a transaction is confirmed. Immediate fund availability provides a significant working capital advantage, allowing businesses to reinvest capital faster than ever before. To protect against market fluctuations, a professional processor facilitates instant conversion to stable currencies like USD or EUR, ensuring that the value captured at the point of sale is the exact value that hits your account.

    Payment Method Settlement Cycle Standard Fees
    International Credit Cards 2 to 7 Business Days 3.5% or higher
    Bank Wires (SWIFT) 1 to 5 Business Days Variable + Flat Fees
    Crypto Payment Processor Instant (T+0) Approximately 1%

    Unlocking New Global Markets

    Global commerce is shifting toward regions where digital assets are a primary payment method. For retail stores, accepting crypto is a powerful tool to attract international travelers who prefer the security and ease of digital wallets over carrying physical currency. This reduction in friction is equally transformative for cross-border B2B transactions. Knowing how to choose a crypto payment processor that prioritizes speed and global reach allows your business to bypass the bottlenecks of traditional banking, positioning you as a forward-thinking strategic partner in the inevitable global evolution of finance.

    How to Choose a Crypto Payment Processor: A 2026 Stakeholder Guide

    The Implementation Roadmap: Integration and Operational Flow

    Transitioning from a strategic framework to operational reality requires a structured, multi-phase approach. Knowing how to choose a crypto payment processor isn’t just about the initial sign-up; it’s about evaluating how the technology will live within your current ecosystem. A successful rollout prioritizes technical compatibility and internal readiness to ensure that digital asset acceptance becomes a standard, effortless business operation. By following a logical progression, you can mitigate technical risks while maximizing the efficiency of your new payment layer.

    • Step 1: Selection of a Technical Partner. Focus on providers offering a robust Payment API that supports high-volume throughput and secure endpoints.
    • Step 2: Technical Integration. Connect the processor to your existing ERP or shopping cart systems to automate the flow of transaction data.
    • Step 3: Internal Team Training. Educate finance and accounting departments on using the merchant dashboard for real-time reporting and reconciliation.
    • Step 4: Infrastructure Deployment. For brick-and-mortar locations, deploy a physical Crypto POS Machine to facilitate in-person digital asset payments.
    • Step 5: Pilot Launch. Initiate a controlled 90-day pilot program to gather performance data and refine operational workflows before a full-scale launch.

    Seamless API and POS Integration

    Modern crypto payment gateways are designed for plug-and-play efficiency, allowing for a “hands-off” implementation with minimal IT overhead. This streamlined architecture ensures that your technical team can focus on growth rather than troubleshooting complex background processes. When evaluating partners, prioritize those that offer comprehensive documentation and reliable technical support to maintain constant uptime for your global operations. A professional bridge between legacy systems and blockchain technology should feel frictionless and secure from the first transaction.

    Reporting and Reconciliation

    Institutional reliability is maintained through clear visibility into every transaction. A critical component of how to choose a crypto payment processor is assessing the reporting capabilities that bridge blockchain data with traditional ledgers. Advanced merchant dashboards simplify the tracking of digital asset sales by providing a unified view of your global revenue. These systems facilitate the automated generation of tax-ready reports, denominated in your preferred fiat currency, which aligns perfectly with standard accounting practices. This centralized interface allows management to oversee multiple store locations or ecommerce channels simultaneously, ensuring total operational control. To begin your integration, explore our API for crypto payments and see how it can accelerate your progress.

    Proposing the Pilot: Moving from Theory to Operational Reality

    The final stage in mastering how to choose a crypto payment processor involves transitioning from theoretical research to a controlled operational environment. A structured 90-day pilot program is the most effective way to minimize perceived organizational risk while gathering primary data. This timeframe allows your finance team to complete three full monthly reconciliation cycles, providing a clear window into the efficiency of the “Hands-Off” settlement model. By limiting the initial scope to a specific ecommerce channel or a select group of retail locations, you can validate the technology without overextending internal resources.

    A pilot program is more than a technical test; it is a strategic R&D investment in the future of your global financial infrastructure. It provides the empirical evidence needed to satisfy the last remaining concerns of your stakeholders. If the results align with your projections, you have a documented roadmap for a full-scale rollout. If adjustments are required, the modular nature of modern APIs allows you to refine the integration or revert to legacy systems without disrupting your core business operations. This reversibility is a key component of institutional-grade risk management.

    Setting Realistic KPIs for Stakeholders

    Success in the early stages should be measured through operational efficiency and error reduction rather than just raw transaction volume. You should track the exact fee savings achieved by bypassing traditional card networks, alongside the reduction in chargeback-related administrative costs. Quantitative metrics are vital, but qualitative feedback is equally important. Gathering insights from your first crypto-native customers can reveal a significant “first-mover” brand advantage in your sector. This data demonstrates to the CMO and CFO that the business is successfully capturing a high-growth, high-net-worth demographic that prioritizes speed and security.

    The Final Pitch: Why 2026 is the Inflection Point

    The global payments market is no longer waiting for crypto to mature; the infrastructure is already institutional-grade. In 2026, the greatest risk is no longer the volatility of the asset, but the competitive risk of being the last to adopt a more efficient settlement layer. Businesses that fail to integrate digital assets face higher overhead and slower capital velocity than their forward-thinking peers. The bridge approach we have outlined is sophisticated, regulated, and specifically designed to mitigate traditional risks. It is the definitive path for connecting established practices with the inevitable global evolution of commerce.

    The most successful implementations are those built on a foundation of expert guidance and reliable technology. You don’t have to build this business case alone. To ensure your pilot program is optimized for both security and growth, consult with a Pallapay specialist to build your custom business case and take the first step toward a more efficient financial future.

    Securing Your Position in the Future of Global Commerce

    The decision to integrate digital assets marks a transition from traditional limitations to global scalability. By aligning your stakeholders through a risk-mitigated “Hands-Off” model and vetting partners against strict institutional standards, you ensure that innovation serves your bottom line. The roadmap we’ve established moves beyond technical integration to focus on long-term financial stability and market expansion. Mastering how to choose a crypto payment processor is the definitive step in transforming your payment infrastructure into a competitive advantage for 2026 and beyond.

    As an institutional partner since 2018, we provide the stability and reach required for enterprise-level growth. Our ecosystem is MSB registered in the USA and Canada, supporting a global presence across 180+ countries. You’re now ready to move forward with the confidence that your background processes are handled by a proven industry leader. Explore Institutional Fiat Settlement Solutions to begin your transition today. Your organization is well-positioned to lead the next evolution of commerce.

    Frequently Asked Questions

    How do I explain crypto price volatility to my CFO?

    Explain that price volatility is entirely avoided by using a processor that facilitates instant conversion to fiat. The merchant receives the exact local currency value of the sale at the moment of the transaction. This ensures that your internal treasury never interacts with fluctuating asset prices. It’s a strategic utility that provides the speed of blockchain with the stability of the traditional banking system.

    Is it legal for a regulated business to accept cryptocurrency payments?

    Accepting digital assets is entirely legal for regulated businesses that partner with licensed Money Services Businesses. These processors manage the complex regulatory requirements, including KYC and AML protocols, on your behalf. You should verify that your provider holds valid registrations in jurisdictions like the United States or Canada. This partnership ensures your operations remain compliant with global financial standards while expanding your reach.

    Do we need to hold cryptocurrency on our company balance sheet?

    You don’t need to hold any cryptocurrency on your balance sheet if you opt for a fiat-settlement model. The processor handles the digital asset on the backend and settles the transaction in your preferred currency, such as USD or EUR. This keeps your accounting processes standard and familiar, allowing for seamless use alongside specialized tools like AIA G702 G703 software for construction billing. It’s an efficient way to capture new revenue without changing your fundamental corporate treasury policies.

    How long does the technical integration of a crypto gateway typically take?

    Most technical integrations for crypto gateways are completed within a few business days using modern, plug-and-play APIs. The process is designed to be efficient, requiring minimal intervention from your IT department. Learning how to choose a crypto payment processor with comprehensive documentation is the best way to ensure a fast rollout. This allows your business to move quickly from a strategic decision to live operations.

    What are the main security risks for corporate stakeholders to consider?

    The most critical risks involve the security of the gateway and the reliability of the settlement partner. Stakeholders should prioritize providers that utilize multi-signature authorization and air-gapped cold storage for all assets. Because blockchain transactions are final and immutable, they eliminate the risk of chargeback fraud that plagues traditional credit cards. A vetted partner with a long history in fintech provides the necessary institutional-grade protection.

    How do crypto processing fees compare to traditional credit card merchant fees?

    Crypto processing fees are substantially lower than traditional merchant fees, typically sitting at approximately 1%. In contrast, international credit card transactions often cost 3.5% or more when factoring in cross-border surcharges. This significant delta is a core part of the value proposition for businesses researching how to choose a crypto payment processor. Lowering these overheads directly improves your operational margins and capital efficiency.

    Can we receive settlements in our local fiat currency immediately?

    You can receive settlements in your local fiat currency almost immediately through a T+0 settlement cycle. This is a major improvement over the standard multi-day SWIFT cycle found in traditional banking. Funds are converted and settled into your account, providing a clear advantage for working capital management. It ensures that your liquidity is never trapped in the settlement process, allowing for faster reinvestment and global growth.

    What happens if a stakeholder is fundamentally opposed to digital assets?

    Position the integration as a strategic tool for cost reduction and global market expansion rather than a speculative investment. Emphasize that the “Hands-Off” model ensures the company never touches the digital assets directly. By focusing on the data from a low-risk pilot program, you can demonstrate tangible improvements in transaction speed and fee savings. This shifts the focus from the asset’s reputation to the technology’s institutional utility.

    Disclaimer

    The information provided on this website and blog is for general informational and educational purposes only and does not constitute financial, investment, legal, tax, or other professional advice.
    Cryptocurrency and digital asset services may be subject to regulatory restrictions in certain jurisdictions. Users are solely responsible for ensuring compliance with applicable local laws and regulations before using any products or services mentioned on this website.
    PallaPay does not guarantee the accuracy, completeness, or timeliness of any information published and accepts no liability for any loss or damages arising from reliance on the content. Any opinions expressed are those of the respective authors and may change without notice.
    Certain services, features, or products referenced may be provided through third-party partners, licensed entities, or affiliated service providers subject to separate terms and regulatory approvals. Availability of services may vary by country or region.
    This website may contain references to digital assets, virtual currencies, or blockchain-related services that are not available to residents of certain jurisdictions, including where prohibited by law. Nothing on this website constitutes an offer, solicitation, or recommendation to buy or sell any financial instrument or virtual asset.
  • Institutional Crypto to Fiat Settlement in the UAE: The 2026 Merchant Guide

    Institutional Crypto to Fiat Settlement in the UAE: The 2026 Merchant Guide

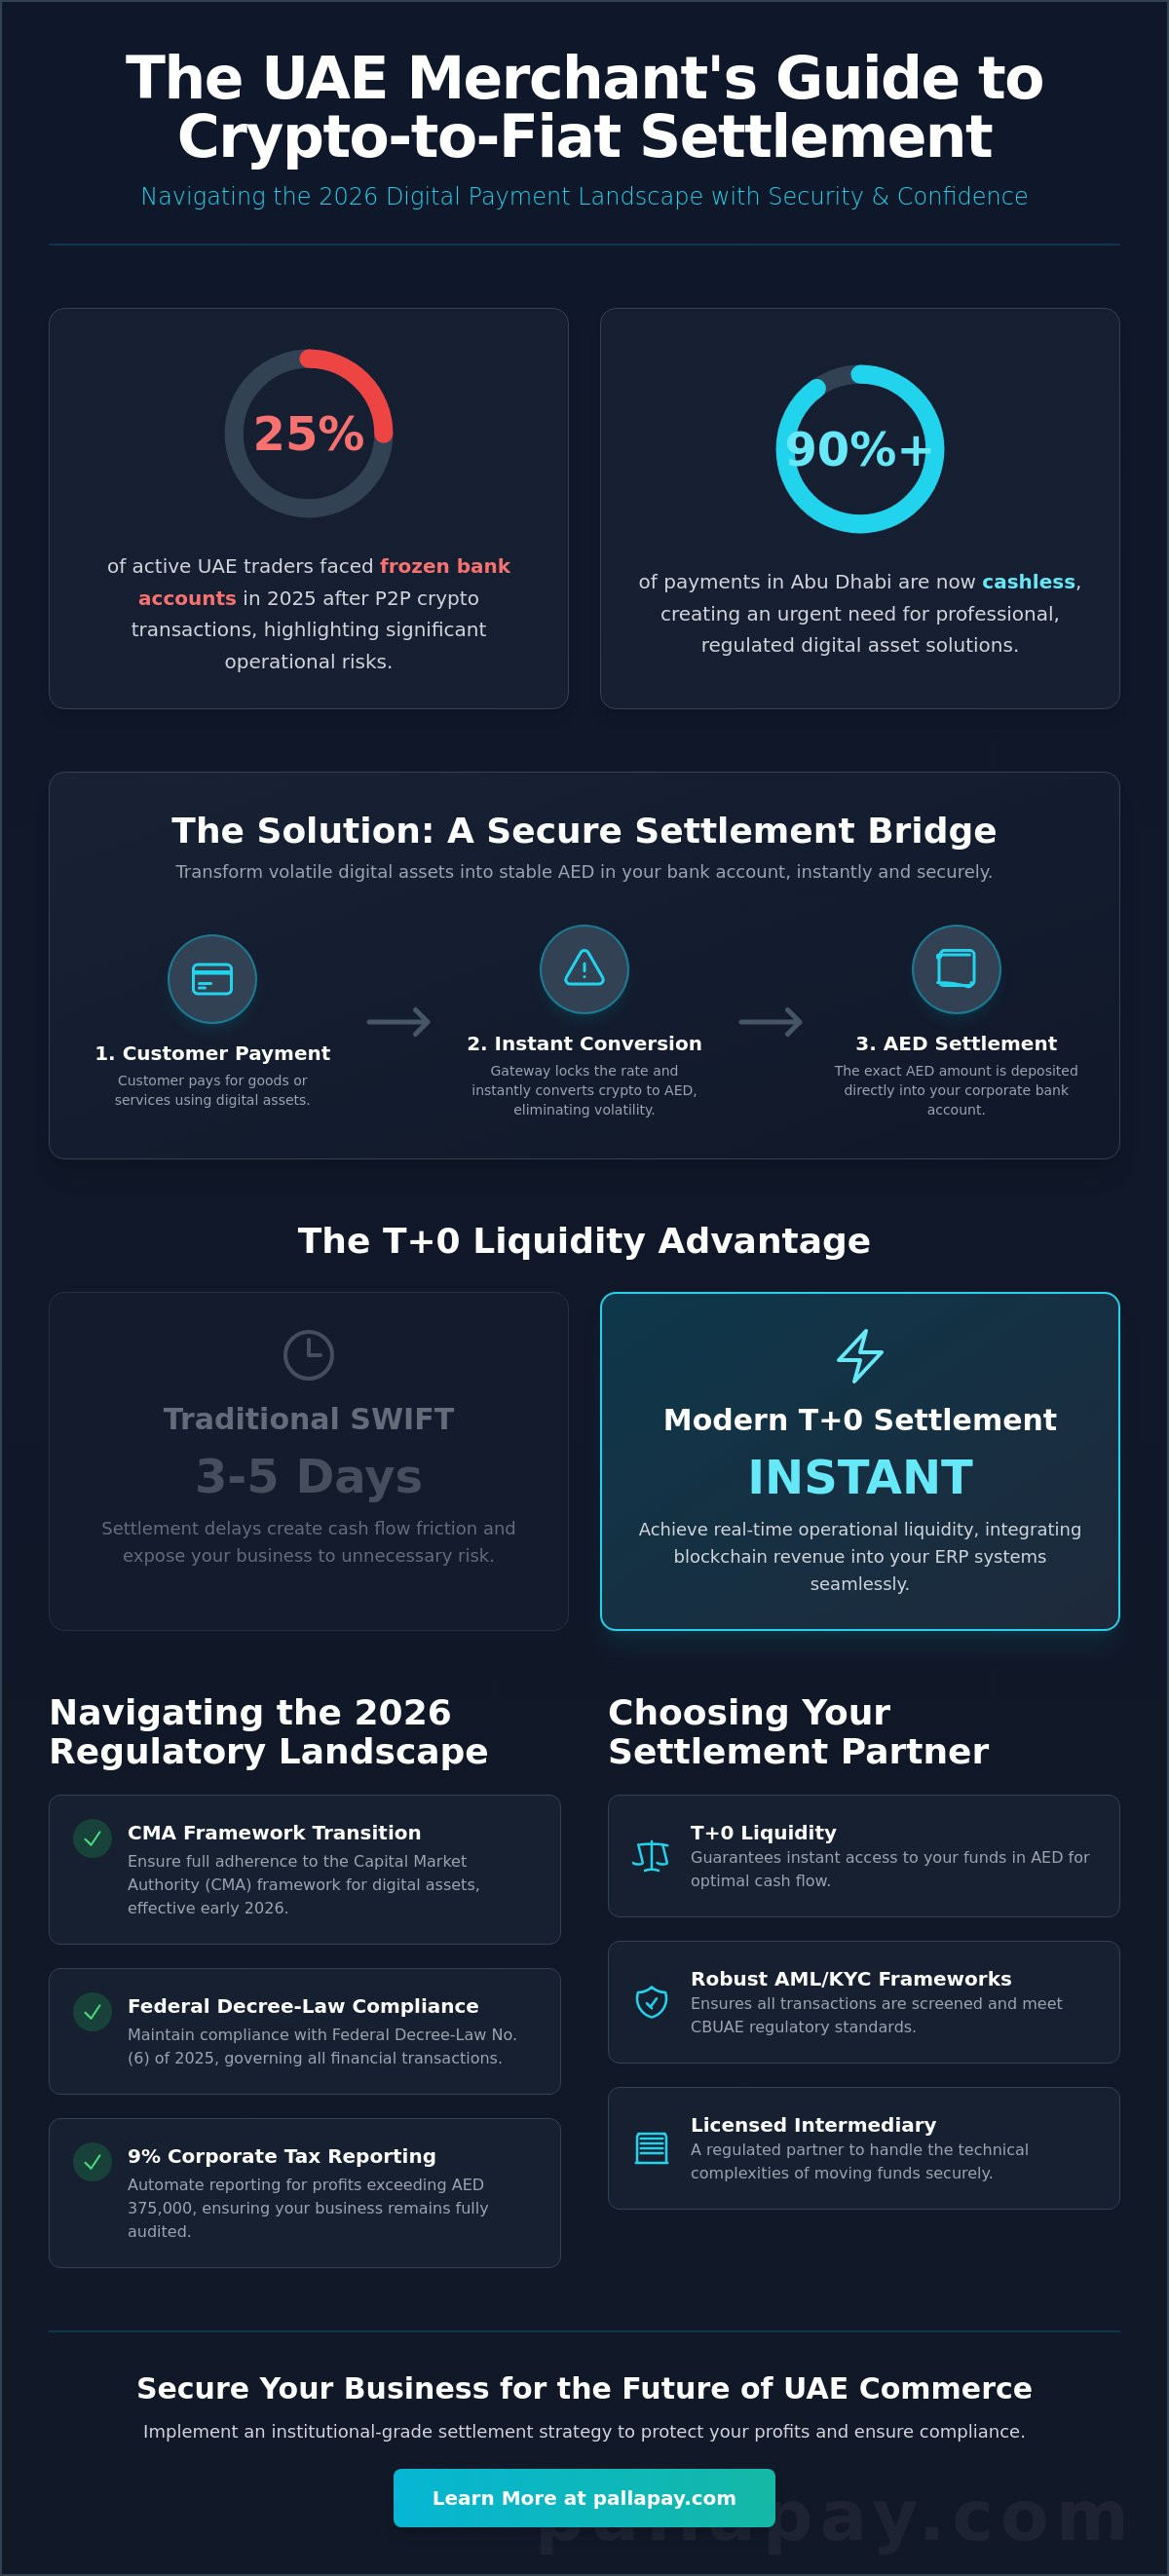
    In 2025, 25% of active UAE traders faced the sudden disruption of frozen bank accounts following P2P transactions. This statistic underscores the urgent need for professional, regulated channels in an economy where over 90% of payments in Abu Dhabi are now cashless. If you’re a merchant, you likely recognize that digital assets represent the future of payments, yet the volatility of the settlement window and the transition to the Capital Market Authority (CMA) framework in early 2026 create valid concerns about stability. Achieving a reliable crypto to fiat settlement uae strategy is no longer a luxury; it’s a fundamental requirement for institutional financial reliability.

    This guide provides the technical clarity you need to convert digital asset payments into AED bank deposits with absolute security. You’ll discover how the New Payment System 2026 enables instant T+0 settlement and automated daily transfers while maintaining full compliance with Federal Decree-Law No. (6) of 2025. We’ll explore the integration of the Digital Dirham and provide a roadmap to navigate the 9% corporate tax requirements, ensuring your business remains both agile and fully audited as you bridge the gap between blockchain innovation and traditional commerce.

    Key Takeaways

    • Secure your profit margins by leveraging instant conversion technologies that eliminate digital asset price volatility during the settlement window.
    • Master the 2026 regulatory requirements for crypto to fiat settlement uae to ensure your business remains compliant with the latest CMA and CBUAE mandates.
    • Streamline your institutional accounting with automated daily bank transfers that bridge the gap between decentralized assets and AED deposits.
    • Evaluate settlement providers based on their ability to offer T+0 liquidity and robust AML/KYC frameworks for seamless financial reporting.
    • Discover how a professional gateway acts as a licensed intermediary to handle the technical complexities of moving funds from customer wallets to your bank account.

    The Strategic Importance of Crypto-to-Fiat Settlement for UAE Merchants

    The UAE’s transition to a digital-first economy reached a critical milestone in February 2026 with the enactment of CMA Decision No. 4/R.M/2026. For local merchants, accepting digital assets is no longer a niche experiment but a strategic necessity to capture global capital. However, the true value of these transactions lies in the efficiency of the crypto to fiat settlement uae process. Without a reliable bridge to AED, businesses face the dual risks of market volatility and regulatory misalignment. Professional settlement ensures that the innovation of blockchain doesn’t compromise the stability of your balance sheet. It transforms a volatile digital entry into a liquid asset that supports your daily operations.

    Bridging the Volatility Gap

    Market fluctuations can erode retail profit margins in minutes. While many are still learning What is Cryptocurrency?, institutional leaders view it as a high-speed payment rail rather than a speculative asset. To maintain financial health, you must eliminate the settlement window where price drops could turn a profitable sale into a loss. Settlement is the conversion of digital assets into sovereign currency to finalize a commercial transaction. By utilizing instant conversion protocols, you lock in the exact AED value at the point of sale. This approach removes the unpredictability that once hindered enterprise adoption, allowing you to treat digital payments with the same confidence as a credit card swipe.

    Operational Liquidity in the Emirates

    Despite the rise of digital assets, AED remains the bedrock of operational reality. You need fiat to cover local overhead, pay staff salaries, and meet the 9% corporate tax obligations on profits exceeding AED 375,000. Effective fiat settlement allows you to integrate blockchain revenue into standard ERP systems without the friction of manual reconciliation. In 2026, the use of fiat-referenced tokens has become the standard for these transfers, providing a stable medium that mirrors the value of the Dirham while retaining the speed of the blockchain. This system bypasses the traditional SWIFT network, which often imposes 3 to 5 day delays, replacing it with a mechanism that mirrors the real-time nature of modern commerce. By 2026, over 90% of payments in Abu Dhabi are cashless, making it vital to have a settlement partner that can move funds at the speed of your customers’ expectations.

    How Crypto-to-Fiat Settlement Works: A Technical Breakdown

    The technical journey of a digital asset transaction begins long before funds reach your corporate balance sheet. It starts with the verification of transaction finality on the blockchain, which ensures that the transfer is immutable and verified by the network. A licensed gateway acts as the professional intermediary in this process, shielding your business from the complexities of managing private keys or wallet security. By automating the transition from a decentralized asset to a stable AED deposit, the infrastructure facilitates a crypto to fiat settlement uae workflow that mirrors the reliability of traditional merchant services.

    Institutional pricing is maintained through direct connections to global liquidity providers and Over-the-Counter (OTC) desks. These connections allow gateways to aggregate high-volume buy and sell orders, ensuring that exchange rates remain competitive even during periods of market stress. This depth of liquidity is essential for preventing price distortions that could otherwise impact your bottom line. By leveraging these professional rails, businesses can process significant transaction volumes while maintaining the narrow spreads required for healthy profit margins. A successful UAE institutional settlement pilot for public services proved that these technical frameworks are now a reliable reality for large-scale operations.

    The Automated Conversion Mechanism

    Efficiency in settlement relies on the seamless execution of sell orders. As soon as a payment is confirmed, a high-performance payment-api triggers an immediate conversion to fiat currency. This automation is the primary defense against slippage, ensuring that the AED value captured at the point of sale is the exact amount deposited into your account. By synchronizing real-time market data with your transaction history, the system provides a clear, benefit-driven answer to the problem of digital asset volatility.

    From Digital Assets to Local Banking Rails

    The final stage of the journey involves moving funds through the New Payment System 2026. This federal infrastructure allows for the direct interface between licensed gateways and UAE commercial banks, enabling T+0 settlement cycles that were previously impossible. You can configure your treasury to receive daily transfers, ensuring that your operational cash flow remains uninterrupted. Every settlement is backed by a transparent audit trail, providing bank compliance officers with the necessary data to verify the provenance of funds. If you’re ready to enhance your liquidity, adopting a professional fiat settlement solution is the logical next step for your enterprise.

    Key Criteria for Choosing a Settlement Provider in the Emirates

    Selecting a settlement partner is a strategic decision that dictates your enterprise’s financial agility and long-term stability. In 2026, the landscape has shifted from basic connectivity to institutional-grade optimization. You shouldn’t settle for a provider that merely processes transactions; you need a partner that enhances your capital efficiency. Institutional crypto to fiat settlement uae hinges on three core pillars: regulatory legitimacy, speed of liquidity, and cost transparency. A failure in any of these areas can lead to operational bottlenecks or, worse, compliance failures that jeopardize your commercial license.

    The UAE’s regulatory framework for digital assets now requires providers to hold specific licenses from the Capital Market Authority (CMA) or the Central Bank. Beyond simple licensing, you must evaluate the settlement speed. While traditional banking might accept T+3 delays, the 2026 standard for digital assets is T+0. This instant liquidity allows you to reinvest capital immediately. Additionally, analyze the fee structure. While gateway fees typically range from 0.4% to 1.0%, you must also account for OTC spreads, which generally sit between 0.5% and 1.2% for major pairs like BTC/AED. This level of detail is essential for high-volume sectors, from luxury hotels to expansive retail stores.

    Security and Compliance Standards

    Institutional safety requires more than just basic encryption. In 2026, MSB registration is a non-negotiable requirement for any provider handling crypto to fiat settlement uae. You should verify that your provider implements biometric authentication for all transactions exceeding 5,000 AED, as mandated by current security protocols. Robust AML/KYC frameworks don’t just protect the provider; they shield your business from being associated with illicit funds, ensuring your bank remains comfortable accepting crypto-derived fiat. A secure fiat settlement process is the foundation of your corporate integrity.

    Technical Reliability and Integration

    Your settlement infrastructure must be as reliable as your electricity. Look for providers offering 99.9% uptime guarantees and comprehensive API documentation that allows for rapid deployment. Integration shouldn’t be a struggle; it should be a seamless addition to your existing e-commerce platforms or physical POS systems. The ability to handle multi-currency support beyond BTC and USDT is also vital. As the Digital Dirham becomes more prevalent, your provider must demonstrate the technical capacity to bridge these various digital formats into your local AED account without manual intervention.

    Institutional Crypto to Fiat Settlement in the UAE: The 2026 Merchant Guide

    The federal oversight of virtual assets reached a new level of maturity with the implementation of CMA Decision No. 4/R.M/2026. This decision establishes a comprehensive federal framework for Transfer & Settlement Services, ensuring that every crypto to fiat settlement uae operation adheres to the highest standards of financial integrity. By centralizing the licensing regime under the Capital Market Authority, the UAE has created a predictable environment for institutional growth. Merchants must also align their operations with the Central Bank of the UAE (CBUAE) guidelines as per Federal Decree-Law No. (6) of 2025. This alignment is critical for maintaining a friction-free relationship with the national banking sector.

    Compliance with the Travel Rule is now a standard requirement for large-scale settlements. This protocol mandates the transmission of specific identifying information for both the sender and the receiver to prevent illicit financial activities. For merchants, this means that every transaction must be documented with precision to satisfy future audits. It’s also necessary to account for the 9% corporate tax on profits exceeding AED 375,000, which applies to gains derived from digital asset settlement. Utilizing a professional gateway simplifies this reporting by providing automated, tax-compliant data exports that integrate directly into your accounting workflows. 2026 regulations require strict provenance of funds to ensure the legitimacy of every dirham entering the local economy.

    Federal and Specialized Jurisdictions

    While the CMA provides the federal foundation, specialized jurisdictions like the Abu Dhabi Global Market (ADGM) offer additional layers of institutional security. The Financial Services Regulatory Authority (FSRA) within the ADGM provides a dedicated environment for sophisticated financial operations, focusing on institutional-grade custody and liquidity. The 2026 deployment of the Digital Dirham serves as the ultimate bridge between these jurisdictions. It provides a government-backed digital currency that can be settled instantly, reducing the complexity of cross-border trade and ensuring that your treasury remains anchored in sovereign stability.

    The Importance of Licensed Intermediaries

    Choosing an unlicensed settlement path creates a systemic risk that can jeopardize your entire commercial operation. In 2025, 25% of active traders faced the sudden freezing of their bank accounts due to unregulated P2P interactions. In 2026, the regulatory scrutiny has only increased. A licensed intermediary handles the heavy lifting of AML and KYC compliance, ensuring that your crypto to fiat settlement uae process is recognized as legitimate by your commercial bank. To protect your business from operational downtime and maintain your access to local banking rails, you should consult with a licensed settlement partner today.

    Pallapay’s Institutional-Grade Settlement Infrastructure

    Pallapay serves as the professional bridge between blockchain innovation and institutional financial reliability. As the UAE’s digital economy matures in 2026, businesses need more than just a gateway; they require a visionary partner that handles the technical complexities of liquidity and compliance. Our platform provides a definitive crypto to fiat settlement uae solution that eliminates the friction of traditional banking cycles. We transform the complex world of digital asset conversion into a standard, effortless business operation, ensuring your capital is always where you need it most.

    Our infrastructure is built for speed. While the industry standard has moved toward T+0, Pallapay ensures that instant crypto-to-AED conversion is the anchor of your payment strategy. We facilitate secure fiat settlement directly to UAE bank accounts, removing the 24-hour wait that once plagued early adopters. This system provides institutional liquidity for high-volume OTC and merchant trades, ensuring that even large-scale settlements are processed without slippage or delay. By anchoring our services in full compliance with local financial standards, we instill a sense of absolute trust in every transaction.

    The Pallapay Advantage for UAE Businesses

    Efficiency is the core of our ecosystem. We offer seamless integration with crypto payment gateways, allowing you to accept various assets and receive settlement in AED with total clarity. Our transparent fee structure removes the hidden costs often found in the broader cryptocurrency space, providing a benefit-driven model for retail and hospitality leaders. Dedicated local support teams assist with merchant onboarding, making the transition to digital payments both fast-paced and secure. This seamless crypto to fiat settlement uae experience ensures that your business stays ahead of the curve in a rapidly evolving financial landscape.

    Scaling Your Business with Global Off-Ramps

    Growth requires versatile financial tools. Our crypto off-ramp services allow your corporate treasury to manage digital wealth with the same ease as traditional fiat. You can also extend the utility of your assets through the Pallapay Mastercard, bridging the gap between corporate accounts and everyday spending. This is the future of payments in the Emirates. Don’t let your business be slowed by outdated financial rails. Schedule a consultation for your settlement infrastructure today and accelerate your growth with a partner that understands the 2026 landscape.

    Secure Your Position in the Future of Payments

    The evolution of the UAE’s financial landscape in 2026 demands more than just technical adoption; it requires an institutional-grade infrastructure that prioritizes stability and compliance. By aligning with the CMA’s federal framework and utilizing T+0 liquidity, your business can confidently eliminate the risks of price volatility. Establishing a robust crypto to fiat settlement uae strategy ensures your digital revenue is instantly accessible in AED, allowing you to focus on growth rather than technical hurdles.

    Pallapay stands as your visionary partner in this transition. We are MSB Registered in the USA and Canada, providing a secure bridge for merchants in over 180 countries. Our platform delivers the deep institutional liquidity required for large-scale OTC trades, ensuring every transaction is backed by global reliability and local expertise. It’s time to modernize your treasury and embrace a system built for the speed of modern commerce.

    Optimize your business with Pallapay’s Instant Fiat Settlement.

    The path to a more efficient, digital-first economy is now open, and your business is perfectly positioned to lead this transformation with absolute confidence.

    Frequently Asked Questions

    Is crypto-to-fiat settlement legal for businesses in the UAE?

    Yes, it’s fully legal under the federal framework established by CMA Decision No. 4/R.M/2026. This regulation categorizes “Transfer & Settlement Services” as a licensed activity, providing a secure path for merchants to operate. By following these guidelines, your business remains compliant with the national financial strategy and avoids the risks associated with unregulated shadow markets.

    How long does it take for crypto payments to reach my bank account?

    Instant T+0 settlement is the operational standard in 2026. While traditional banking once required 3 to 5 days, modern gateways utilize the New Payment System 2026 to facilitate immediate AED transfers. This speed ensures your capital remains liquid and ready for reinvestment without the typical waiting periods associated with legacy finance.

    Which cryptocurrencies can be settled into AED?

    You can settle major assets such as Bitcoin, Ethereum, and fiat-referenced stablecoins like USDT. However, privacy tokens such as Monero and Zcash are prohibited under current CMA regulations effective February 2026. Most institutional providers focus on high-liquidity assets to ensure that your crypto to fiat settlement uae process remains fast and cost-effective.

    Do I need a special bank account to receive fiat settlements?

    No, a standard UAE commercial bank account is sufficient when you use a licensed settlement provider. The provider acts as the regulated intermediary, ensuring that the funds arriving in your account are recognized as legitimate fiat revenue. This transparency prevents the account freezes that affected 25% of active traders using unregulated P2P methods in 2025.

    What are the tax implications of settling crypto to fiat in the UAE?

    Gains from virtual asset trading are subject to a 9% corporate tax on profits exceeding AED 375,000. While the transfer of assets is generally exempt from VAT, any advisory or custody services you receive will incur a 5% VAT. Maintaining precise digital records is essential for satisfying Federal Tax Authority audits in the 2026 fiscal year.

    Can I settle crypto into currencies other than AED, such as USD or EUR?

    Yes, professional settlement infrastructures support multiple sovereign currencies including USD, EUR, and GBP. This flexibility is vital for businesses engaged in international trade that need to manage global overhead. You can choose your preferred settlement currency within your gateway settings to match your specific corporate treasury requirements and liquidity needs.

    What happens if the price of crypto drops during the settlement process?

    Instant conversion protocols lock in the exchange rate at the exact moment the transaction is confirmed on the blockchain. This automation eliminates the risk of price volatility during the settlement window. By using a crypto to fiat settlement uae provider that utilizes real-time liquidity, you ensure that the AED amount you receive matches the price displayed at the point of sale.

    How does the “Travel Rule” affect my daily business settlements?

    The Travel Rule requires the exchange of identifying information for both the sender and the receiver during large-scale transactions. This protocol ensures full AML compliance and is integrated into the backend of licensed settlement providers. It automates the verification process, allowing your business to meet federal reporting obligations without slowing down your daily operations or compromising user experience.

    Disclaimer

    The information provided on this website and blog is for general informational and educational purposes only and does not constitute financial, investment, legal, tax, or other professional advice.
    Cryptocurrency and digital asset services may be subject to regulatory restrictions in certain jurisdictions. Users are solely responsible for ensuring compliance with applicable local laws and regulations before using any products or services mentioned on this website.
    PallaPay does not guarantee the accuracy, completeness, or timeliness of any information published and accepts no liability for any loss or damages arising from reliance on the content. Any opinions expressed are those of the respective authors and may change without notice.
    Certain services, features, or products referenced may be provided through third-party partners, licensed entities, or affiliated service providers subject to separate terms and regulatory approvals. Availability of services may vary by country or region.
    This website may contain references to digital assets, virtual currencies, or blockchain-related services that are not available to residents of certain jurisdictions, including where prohibited by law. Nothing on this website constitutes an offer, solicitation, or recommendation to buy or sell any financial instrument or virtual asset.