By the start of 2026, over 90% of all digital asset transactions will flow through platforms that enforce strict, institutional-grade identity protocols. You’ve likely felt the frustration of a 48-hour onboarding delay or the anxiety of sending sensitive documents into a digital void. It’s a friction point that many traders face as the industry matures into a global financial standard. Mastering kyc in crypto isn’t just about following rules; it’s about ensuring your capital remains liquid and your access to the market stays uninterrupted. We’re here to bridge the gap between complex regulation and the seamless execution you deserve.
This guide provides the definitive roadmap to meeting the evolving requirements in major hubs like Dubai and the USA. You’ll learn how to achieve instant verification and confirm that your chosen gateway is a legitimately regulated entity. We’ll show you how to protect your data while embracing the security that modern compliance offers. By the end of this article, you’ll understand why robust verification is the foundation for the future of payments. It’s time to move toward a more secure and efficient way to manage your digital wealth.
Key Takeaways
- Understand how the 2026 regulatory shift, including MiCA and the FATF Travel Rule, creates a standardized global environment for secure transactions.
- Identify the core pillars of a robust compliance program to ensure your digital asset activities remain uninterrupted and fully verified.
- Discover why kyc in crypto acts as the professional bridge between decentralized innovation and reliable institutional-grade financial services.
- Master the steps for instant identity verification, from document preparation to biometric liveness checks, for a frictionless onboarding experience.
- Learn how Pallapay’s global MSB registrations and all-in-one ecosystem empower you to lead the future of payments with absolute trust.
What is KYC in Crypto and Why is it Mandatory in 2026?
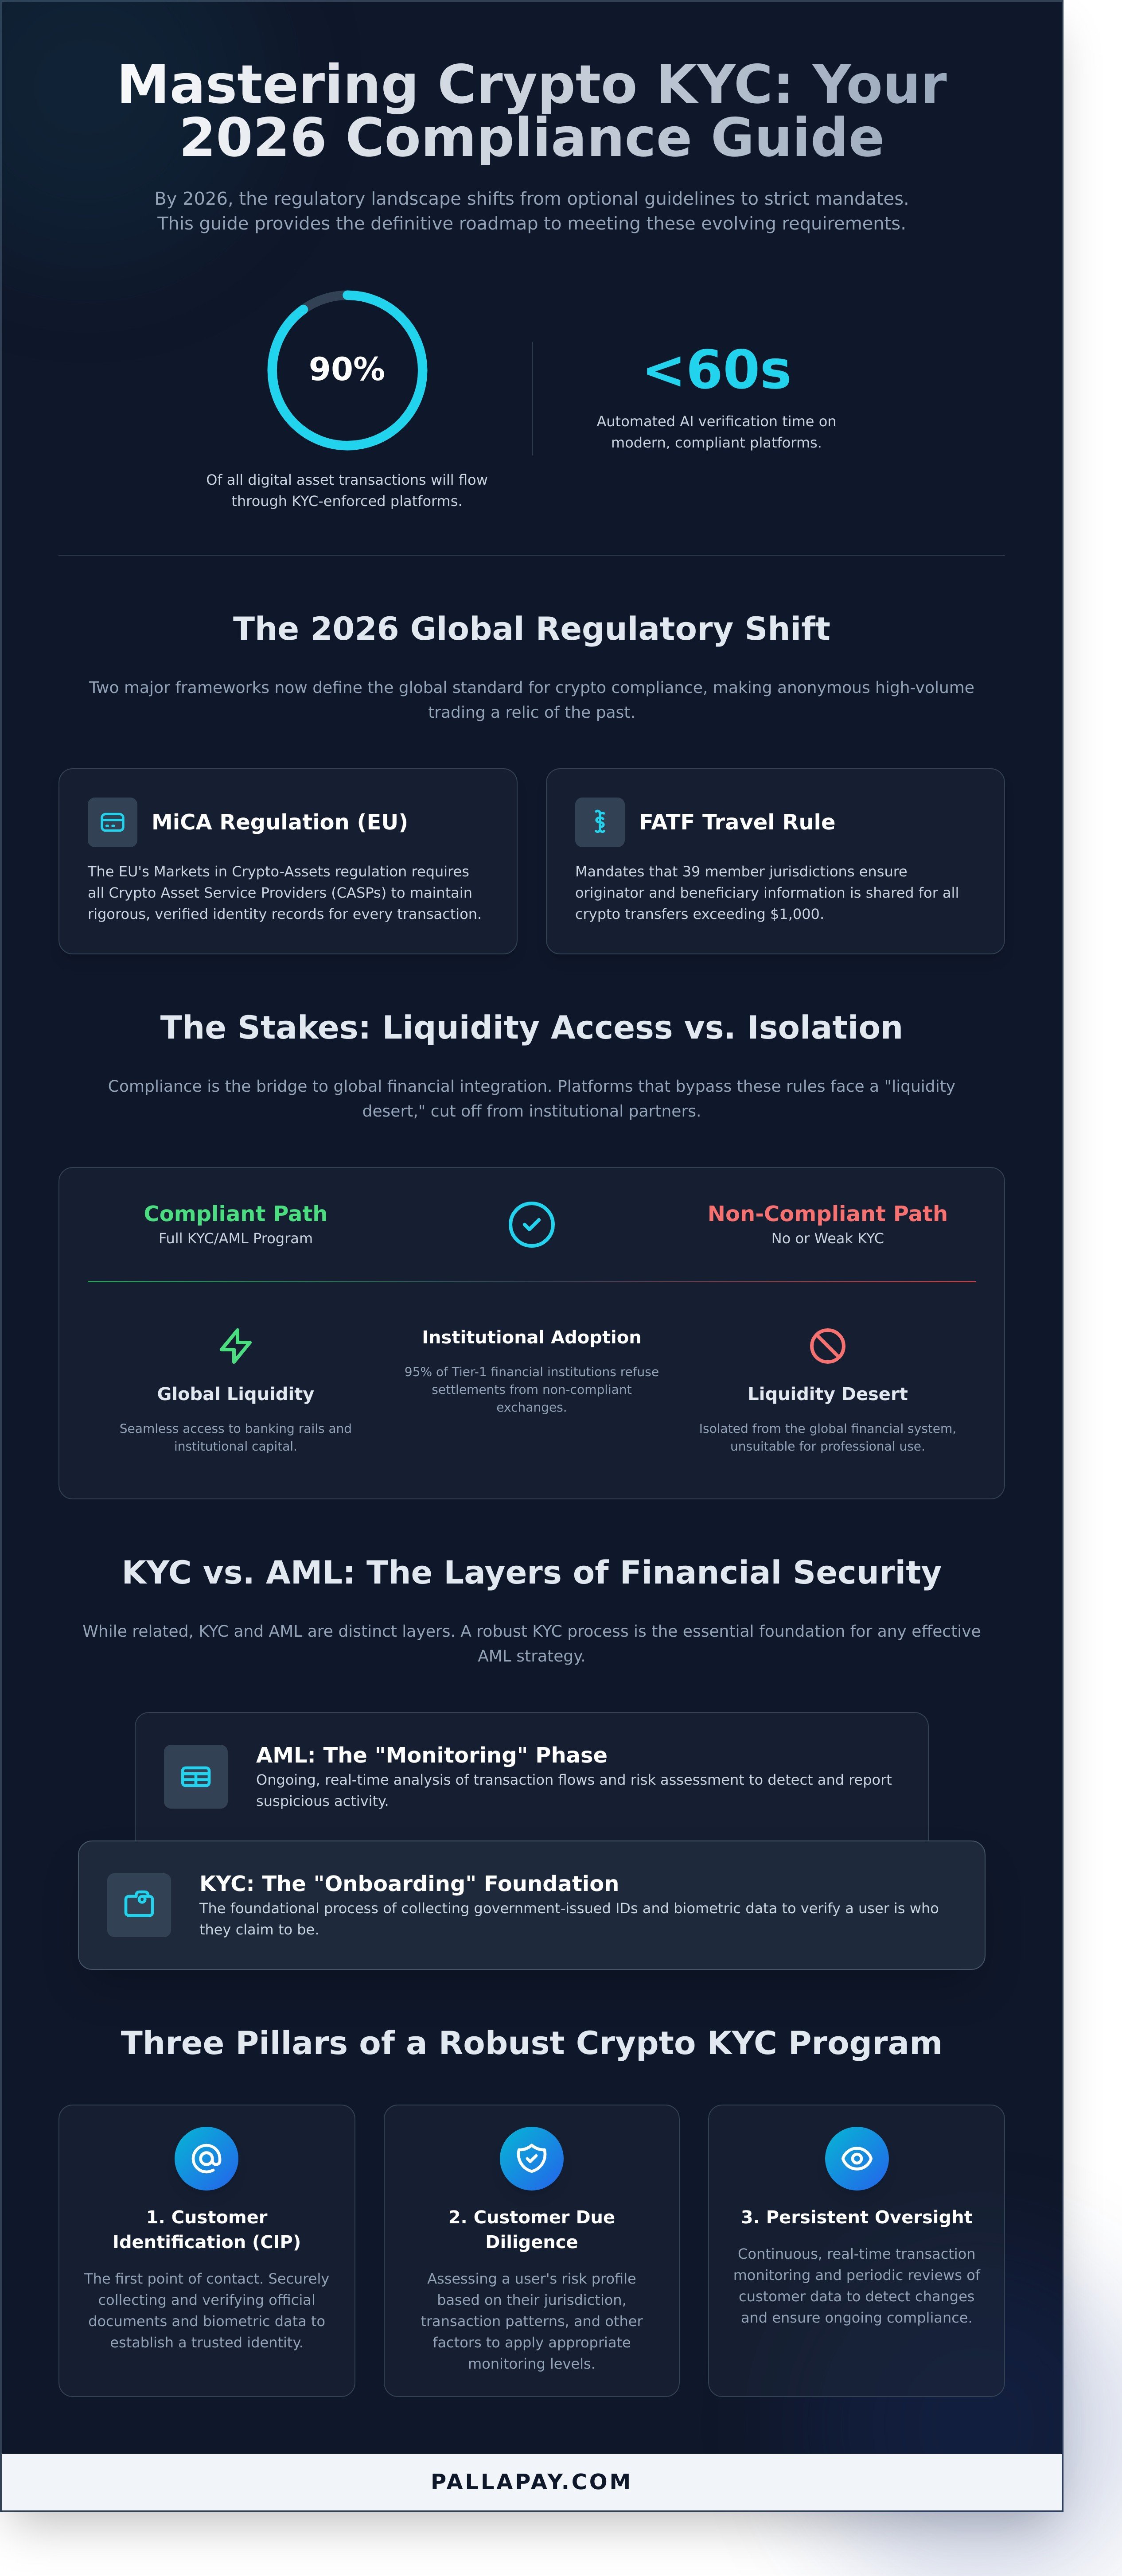
Know Your Customer (KYC) is the mandatory process of identifying and verifying a user’s identity before they can access financial services. It’s the primary tool used by digital asset platforms to prevent identity theft, financial fraud, and the illicit flow of funds. To understand What is KYC in its broadest sense, one must look at how traditional banking protocols have been integrated into the blockchain space to ensure institutional-grade security. By 2026, the global regulatory environment has shifted from optional guidelines to strict, enforceable mandates. Implementing kyc in crypto is no longer a choice for platforms that want to maintain access to global liquidity and banking rails.
The 2026 regulatory landscape is defined by two major frameworks: the European Union’s Markets in Crypto-Assets (MiCA) regulation and the Financial Action Task Force (FATF) Travel Rule. MiCA, which reached full implementation stages by late 2024, requires all Crypto Asset Service Providers (CASPs) to maintain rigorous identity records for every transaction. Simultaneously, the FATF Travel Rule mandates that 39 member jurisdictions ensure exchanges share originator and beneficiary information for all transfers exceeding $1,000. These standards have effectively standardized global requirements, making anonymous high-volume trading a relic of the past.
Platforms that attempt to bypass these rules are increasingly marginalized. In 2026, 95% of Tier-1 financial institutions refuse to process fiat settlements originating from non-compliant exchanges. This lack of connectivity creates a liquidity desert for “No-KYC” entities, rendering them unsuitable for professional merchants or institutional investors who require instant and secure settlement. Compliance is the bridge that allows digital assets to function as a legitimate component of a global business’s balance sheet.
The Evolution of Crypto Compliance
The transition from the 2009 era of pseudonymous transactions to the 2026 institutional standard was driven by the need for stability. High-profile failures, such as the $8 billion collapse of FTX in November 2022, accelerated the global demand for transparency. Today, trust is established through Money Services Business (MSB) registrations. These licenses, managed by bodies like FinCEN in the United States or the VARA in Dubai, provide the legal framework for 100% of legitimate crypto-fiat gateways. Founders and operators who want to understand the full strategic implications of these requirements should consult a comprehensive msb license crypto regulatory guide to ensure their business structure meets the 2026 standard. Professional platforms now use automated AI verification to confirm identities in under 60 seconds, proving that security doesn’t have to sacrifice speed.
KYC vs. AML: Understanding the Difference
While often used interchangeably, these terms represent different layers of a security strategy. KYC is the initial onboarding phase where a platform collects a government-issued ID and biometric data to ensure a user is who they claim to be. Anti-Money Laundering (AML) is the broader, ongoing strategy that includes transaction monitoring and risk assessment to detect suspicious patterns. You can’t have an effective AML program without a robust kyc in crypto foundation because it’s impossible to monitor risk if the identity of the participant is unknown. KYC serves as the foundational layer of digital financial trust.
- KYC: The “Onboarding” phase involving identity collection and document verification.
- AML: The “Monitoring” phase involving real-time analysis of transaction flow and origin of funds.
- Compliance: The total adherence to regional laws like MiCA or the US Bank Secrecy Act.
By 2026, the integration of these processes has become seamless. Modern fintech leaders use these protocols not as hurdles, but as value-added features that protect the user’s capital. When a platform verifies your identity, it isn’t just satisfying a regulator; it’s ensuring that your account is shielded from unauthorized access and that your business can scale without the threat of sudden legal intervention.
The Three Pillars of a Robust Crypto KYC Program
Building a secure crypto ecosystem requires more than just a basic login. It demands a structured framework that mitigates risk while facilitating institutional growth. By Q1 2026, AI-driven automation has transformed kyc in crypto from a manual hurdle into a seamless, real-time verification process. This evolution relies on three foundational pillars: identification, risk assessment, and persistent oversight. These components work in unison to protect the integrity of every transaction.
Customer Identification (CIP) Essentials
The Customer Identification Program serves as the first point of contact between a user and a financial platform. It ensures that a participant is exactly who they claim to be. Standard data points like full names, dates of birth, and physical addresses remain the bedrock of this process. However, the industry has transitioned toward digital-first identification to meet modern demands. Today, 88% of global exchanges utilize e-IDs and biometric liveness checks to eliminate identity fraud. This technology captures high-resolution data that legacy systems often miss.
Verification now extends beyond simple document collection. Modern gateways cross-reference user data against global PEP and sanctions lists in milliseconds. This rigorous vetting is not just a regulatory burden; it is a vital security feature. When discussing Privacy vs. Compliance: Addressing the Anonymity Debate, regulators like FinCEN emphasize that identifying participants is the only viable way to prevent illicit actors from exploiting digital assets. By verifying users at the entry point, platforms provide the stability that institutional investors require.
Advanced Due Diligence and Monitoring
Once a user’s identity is confirmed, the system must determine the specific risk they pose to the network. This is where Customer Due Diligence (CDD) becomes vital. Most retail users undergo Simplified Due Diligence, which is a fast-tracked process for low-risk profiles. For high-volume traders or corporate entities, Enhanced Due Diligence (EDD) is mandatory. EDD involves deeper investigations into the source of funds and the nature of the business. It is a necessary step to maintain the high-level liquidity and trust found in professional crypto environments.
Continuous monitoring completes the framework by providing persistent oversight. It doesn’t stop after the initial onboarding. Modern systems use machine learning to identify “smurfing,” which is a technique where large sums are broken into small, frequent transactions to avoid detection. In 2026, real-time alerts catch these patterns instantly. This level of oversight ensures that kyc in crypto remains a dynamic shield rather than a static gate. It allows for the rapid detection of anomalies without disrupting the user experience for legitimate participants.
Implementing these three pillars allows businesses to scale without fear of regulatory backlash or financial crime. If you’re looking to integrate a solution that handles the heavy lifting of compliance, consider how an all-in-one crypto payment gateway can streamline your operations. By automating these processes, you ensure your business remains at the forefront of the future of payments while maintaining total security. This approach transforms a complex regulatory requirement into a standard, effortless business operation.
Privacy vs. Compliance: Addressing the Anonymity Debate
The debate over anonymity often misses the practical reality of global finance. Many enthusiasts believe that kyc in crypto undermines the core value of blockchain technology, yet the opposite is true. Regulation provides the essential framework for fiat-to-crypto gateways, allowing digital assets to interact with the $100 trillion traditional banking system. Without these standards, the industry would remain an isolated sandbox. According to data from the 2021 FATF updated guidance, clear identity protocols are the primary reason institutional adoption increased by 400% between 2022 and 2025. This transition isn’t about surveillance; it’s about building a professional bridge that connects disruptive innovation with global reliability.
By 2026, the implementation of Zero-Knowledge Proofs (ZKP) will redefine this landscape entirely. This technology allows users to verify their eligibility for a service without exposing their actual Personally Identifiable Information (PII). For example, a user can prove they are a resident of a specific jurisdiction or over the age of 21 without ever sharing their birthdate or home address. This shift transforms kyc in crypto from a data-heavy burden into a streamlined, privacy-preserving process. It’s the ultimate solution for a secure, all-in-one financial ecosystem that respects individual privacy while satisfying the rigorous requirements of the European Banking Authority (EBA).
The misconception that blockchain requires total anonymity ignores the need for utility. If you want to pay for a luxury property or settle a cross-border invoice, you need a gateway that banks trust. Instant settlement is only possible when the underlying entities are verified. This creates a “clean” ecosystem where merchants can accept digital payments without the fear of interacting with sanctioned addresses or high-risk funds. Pallapay acts as this global enabler, ensuring that your transition from digital assets to fiat currency is seamless and legally sound.
Why Institutional Liquidity Requires Identity
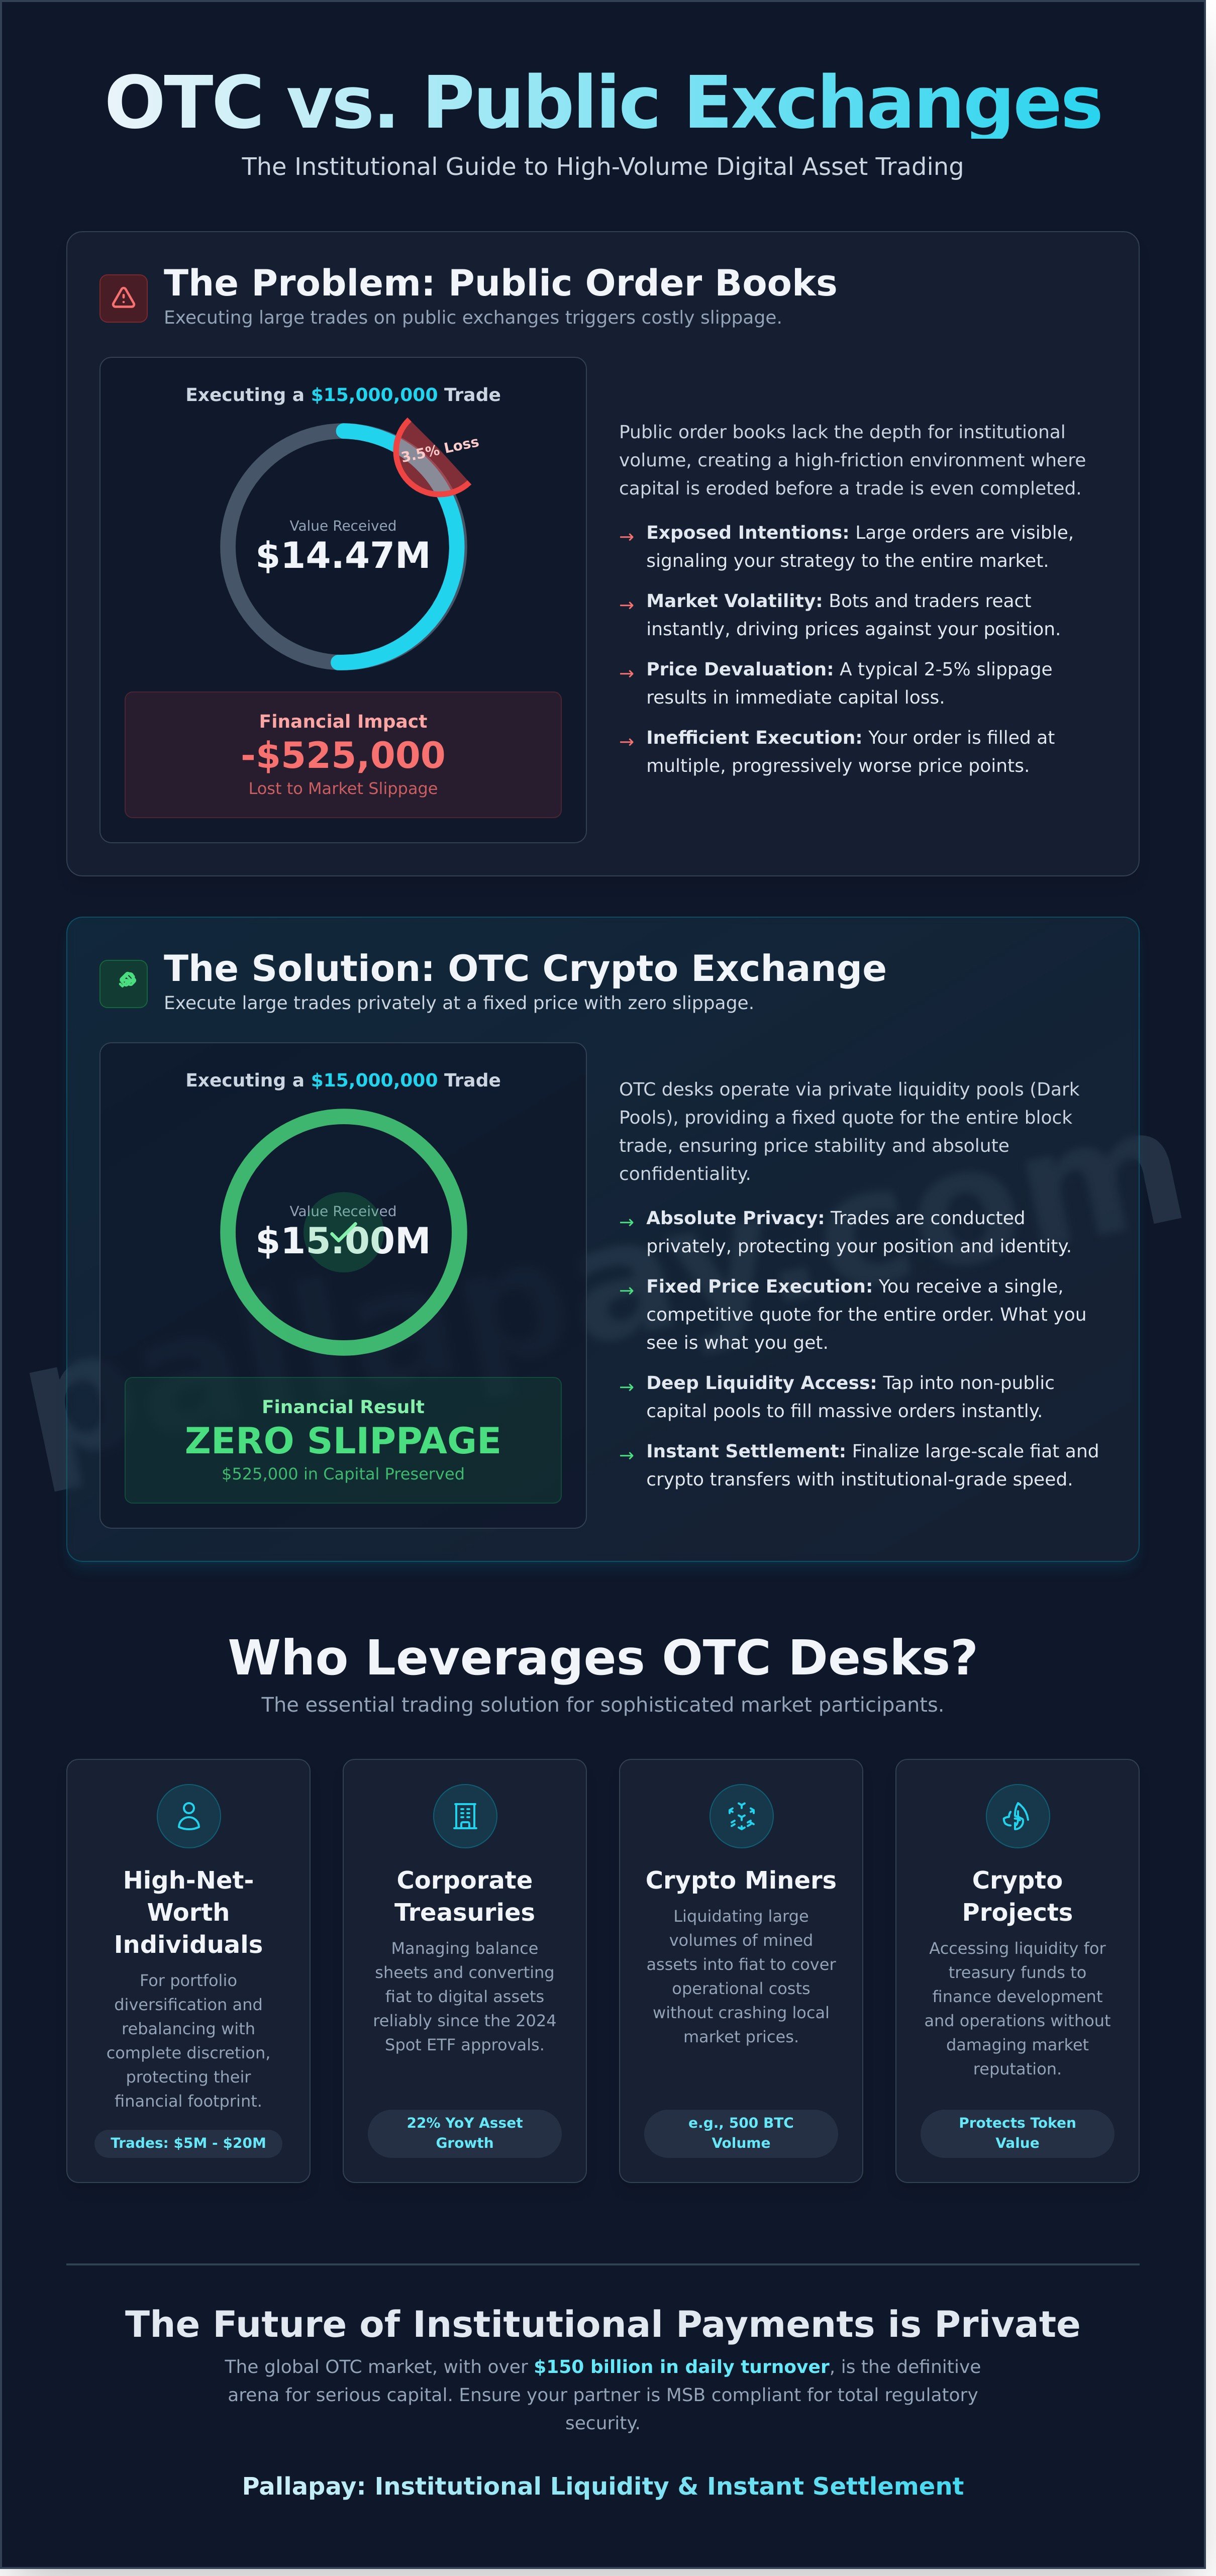
Large-scale investors and OTC desks can’t operate in a vacuum. They require a verified environment to satisfy their own internal audits and legal mandates. Compliant platforms offer significantly better pricing; for instance, regulated exchanges typically show transaction spreads as low as 0.05%, while lawless platforms often exceed 2.5% due to liquidity fragmentation. Merchants use these professional gateways to ensure their settlements are instant and free from the risk of clawbacks or asset freezes. Institutional liquidity is the fuel for the future of payments, and identity is the key that unlocks it.
Data Protection Standards in 2026
Regulated firms treat your PII with the same gravity as a Tier-1 bank. Under the 2024 MiCA framework and global GDPR equivalents, your data is protected by AES-256 encryption and stored in isolated, hardware-security-module (HSM) environments. There’s a sharp distinction between a privacy-focused platform and a lawless one. Security is a byproduct of compliance, not an alternative to it. By adhering to these global standards, we provide a stable environment where your data is used only for its intended purpose: to facilitate your growth in the global economy.
The evolution of the crypto space toward a more transparent model doesn’t signal the end of blockchain’s value. Instead, it marks the beginning of its maturity. When every participant is verified, the risk of fraud drops by over 70%, as seen in the 2025 Fintech Security Report. This stability attracts more merchants, more liquidity, and more innovation. It’s a logical, step-by-step progression toward a world where digital and traditional finance are one and the same.
How to Navigate the Crypto KYC Process Instantly
Modern digital finance demands speed without compromising on security. Completing kyc in crypto used to be a multi-day ordeal involving manual reviews and grainy webcam shots. By 2026, the industry has shifted toward automated, AI-driven verification that processes data in under 60 seconds. This evolution ensures that your transition from traditional fiat to digital assets remains fluid. Success depends on your initial preparation; having the correct documentation ready prevents the system from flagging your application for manual intervention.
Your identity document serves as the foundation of this process. Most global platforms require a valid passport, a government-issued local ID, or a high-security driving license. Ensure your document is physically intact. Statistics show that 15% of verification failures stem from expired documents or physical damage that obscures the machine-readable zone (MRZ). If your ID expires within the next three months, many automated systems will reject it to prevent future compliance gaps.
The 2026 standard for proof of residence has moved away from physical paper. While utility bills remain acceptable, digital bank statements in PDF format are now preferred for their verifiable metadata. These documents must be less than 90 days old and clearly display your full name and residential address. Avoid using mobile phone bills; most institutional-grade gateways don’t accept them because they lack the permanent residency verification provided by a mortgage statement or a municipal tax bill.
Step-by-Step Verification Guide
- Upload high-resolution, uncropped images: Use a minimum of 300 DPI for all scans. Ensure all four corners of the document are visible within the frame to prove the document hasn’t been digitally altered.
- Optimize the biometric “liveness” scan: Position yourself in neutral, natural lighting. Avoid overhead lights that create shadows on your face, as biometric sensors require clear visibility of your bone structure to confirm your identity.
- Sync your credentials: Your registered name on the crypto platform must match your bank account name exactly. Even minor discrepancies, like a missing middle name, can block fiat transfers and trigger a secondary manual review.
Troubleshooting Common Issues
Technological friction often arises from environmental factors rather than internal system errors. If the system doesn’t recognize your ID, check for holographic glare. Tilted camera angles often reflect light off the plastic coating of an ID, blinding the OCR (Optical Character Recognition) software. Additionally, ensure you aren’t using a VPN during the process. Global compliance protocols flag IP addresses that don’t match the geographic location of the submitted ID, which often results in an immediate, automated account freeze.
Pallapay simplifies this entire architecture through its “Instant” verification technology. By integrating directly with global identity databases, Pallapay reduces onboarding friction, allowing users to move from registration to their first transaction in record time. This system handles the heavy lifting of compliance behind the scenes, ensuring that your journey into The Future of Payments is both secure and immediate. If you’re ready to experience a seamless financial ecosystem, you can start your instant verification with Pallapay today.
Efficiency in kyc in crypto is no longer a luxury; it’s a requirement for modern commerce. By following these technical guidelines and utilizing sophisticated platforms, you eliminate the delays that once hindered the digital economy. Every step you take toward proper documentation is a step toward institutional-grade security and global financial mobility. To further strengthen your defenses, understanding the full scope of crypto security protocols required in 2026 ensures your verified accounts and digital assets remain protected against the sophisticated threat landscape facing modern merchants.
Pallapay: Your Partner for Secure and Compliant Crypto Services
Pallapay operates as a sophisticated bridge between decentralized innovation and institutional financial reliability. We provide the infrastructure that transforms digital assets into usable capital, ensuring that every transaction meets the highest regulatory benchmarks. Our commitment to global standards is evidenced by our active Money Services Business (MSB) registrations with FinCEN in the United States and FINTRAC in Canada. These registrations require us to maintain rigorous Anti-Money Laundering (AML) protocols and independent audits, providing a secure environment for both retail users and institutional partners. For businesses seeking to understand the full scope of what a robust msb license crypto strategy entails — from FinCEN registration to state-level licensing — a dedicated regulatory guide provides the complete 2026 roadmap. Since 2015, we’ve focused on building a platform where security isn’t an afterthought but the primary product.
The Pallapay ecosystem is an all-in-one solution designed for the modern economy. We integrate high-volume Over-the-Counter (OTC) trading, advanced Point of Sale (POS) terminals, and global Mastercard issuance into a single, cohesive gateway. For high-volume investors, this means deep liquidity and tight spreads; for merchants, it means the ability to accept digital payments without price volatility. Our compliance-first approach protects your assets by filtering out illicit activity before it enters the ecosystem. By prioritizing kyc in crypto, we ensure that every participant is verified, which significantly reduces the risk of frozen funds or regulatory interventions that often plague less regulated platforms.
- Global MSB Registrations: Full compliance with North American financial authorities ensures your funds are handled by a regulated entity.
- Institutional Liquidity: Access professional-grade OTC desks for large-scale conversions with minimal slippage.
- All-in-One Utility: Manage trading, spending, and merchant settlements through a single, secure dashboard.
Global Presence, Local Compliance
Our strategic presence in Dubai, Singapore, and Istanbul allows us to navigate the complex regulatory landscapes of the Middle East, Asia, and Europe simultaneously. In Dubai, we align with the evolving Virtual Assets Regulatory Authority (VARA) frameworks to provide localized support for the region’s growing fintech sector. Each regional hub operates with a deep understanding of local tax laws and reporting requirements, ensuring that your business remains compliant regardless of where you operate. This localized expertise is why 98% of our corporate clients report higher confidence in their cross-border settlements. Learn more about our MSB registration and security protocols to see how we maintain these global standards.
Enabling Business with Compliant Gateways
Modern commerce demands speed. Our KYC-backed infrastructure allows for instant crypto-to-fiat settlements, moving funds to your bank account in less than 24 hours. Traditional banking often delays these processes for 3 to 5 business days; Pallapay eliminates this friction. By implementing robust kyc in crypto at the point of onboarding, we clear the path for seamless, high-velocity commerce. Retailers using our regulated POS terminals can accept Bitcoin, Ethereum, and Tether, receiving the exact fiat value at the moment of sale. This protects your margins from market swings while opening your doors to a global audience of over 420 million crypto users. Experience the future of secure payments with Pallapay and scale your business with a partner that understands the value of compliance.
The Future of Payments is not just about the technology of the blockchain; it’s about the trust that enables its use. Pallapay provides that trust by handling the heavy lifting of regulatory compliance and technical integration behind the scenes. We’re not just a service provider; we’re a visionary partner helping you navigate the transition to a digital-first financial world. Whether you’re an individual looking for a secure Mastercard or a multinational corporation needing a robust payment gateway, our ecosystem delivers the stability you require.
Master the Future of Digital Asset Compliance
The transition toward mandatory compliance is the essential bridge to global financial stability. By 2026, robust verification frameworks have become the standard for any entity seeking long-term viability in the digital asset space. You’ve seen how the three pillars of identity, monitoring, and risk management protect your assets from evolving threats. Mastering kyc in crypto ensures your operations remain seamless while meeting the strict demands of international regulators. It’s about turning a regulatory requirement into a strategic competitive advantage.
Pallapay simplifies this transition by providing an all-in-one ecosystem designed for high-stakes commerce. We maintain official MSB registrations in the USA and Canada; this ensures every transaction meets institutional standards. As an award-winning crypto payment gateway in Dubai serving clients in over 180 countries, we prioritize your need for instant settlement and absolute security. You don’t have to choose between speed and compliance when you partner with a global leader. Take the next step toward secure growth with confidence.
Join 50, 000+ users and businesses on the world’s most secure crypto ecosystem
Frequently Asked Questions
Is KYC in crypto safe for my personal data?
Leading platforms protect your data using AES-256 encryption and follow ISO/IEC 27001 standards to ensure institutional-grade security. These protocols prevent unauthorized access while maintaining the integrity of your digital identity. By choosing a regulated gateway, you ensure your personal information remains isolated from public ledgers. We prioritize these security layers to provide a seamless and secure environment for every transaction.
Can I buy Bitcoin or USDT without KYC in 2026?
Buying Bitcoin or USDT without verification is virtually impossible in 2026 due to the full implementation of the EU MiCA regulations and FATF Recommendation 16. These global standards require 100% of centralized exchanges to verify user identities to prevent illicit activity. Non-compliant platforms face immediate license revocation under these 2024 frameworks. This shift ensures the future of payments is both transparent and globally accessible for professional users.
How long does the crypto KYC process usually take?
The kyc in crypto process typically takes between 2 minutes and 24 hours depending on the platform’s automation. Modern fintech leaders use AI-driven verification to provide instant results for 95% of standard applications. If manual review is necessary, compliance teams usually finalize the settlement within 1 business day. This speed ensures you can bridge the gap between fiat and digital assets without unnecessary delays.
What happens if I fail the KYC verification process?
You’ll receive a specific notification detailing why the verification failed, such as an expired ID or a blurred 4K image. Most platforms grant a 30-day window to resubmit the correct documentation before restricting account access. If the failure stems from a high-risk match in the 2023 OFAC database, the institution must freeze the account immediately. Professional support teams assist in resolving these technical friction points to restore your access.
Why do I need to provide a “liveness check” for crypto?
Liveness checks prevent identity theft by ensuring a real person is present rather than a static 2D photograph or a deepfake video. This biometric scan maps 50 distinct facial points to create a unique digital signature for your profile. It’s a critical security layer that facilitates instant account recovery and prevents unauthorized liquidations. By implementing this tech, we build the professional bridge needed for secure, global commerce.
Does KYC apply to hardware wallets or just exchanges?
KYC requirements apply to Virtual Asset Service Providers (VASPs) like exchanges and OTC desks, not to the hardware wallets themselves. You don’t need to provide ID to use a Ledger or Trezor for self-custody. However, the moment you connect that wallet to a regulated gateway to convert crypto to fiat, the kyc in crypto rules trigger. This distinction preserves the utility of private storage while maintaining institutional compliance for all financial settlements.
How does the Travel Rule affect my crypto transfers?
The Travel Rule requires exchanges to share the name and account number of the sender and recipient for all transfers exceeding $1,000. This regulation, updated by the FATF in 2023, mirrors traditional SWIFT banking protocols to ensure transparency in cross-border movements. It streamlines the movement of assets between regulated entities by providing a clear audit trail. This integration makes digital asset transfers as reliable as standard institutional wire transfers.
Is KYC required for merchants accepting crypto payments?
Merchants must undergo Know Your Business (KYB) verification to comply with the EU’s 5AMLD and 6AMLD directives. This process validates the legal status of the company and the identity of its ultimate beneficial owners holding over 25% equity. Once verified, businesses gain access to instant settlement and global liquidity pools. This professional vetting process is the foundation for any merchant aiming to lead the future of payments.
Disclaimer
The information provided on this website and blog is for general informational and educational purposes only and does not constitute financial, investment, legal, tax, or other professional advice.
Cryptocurrency and digital asset services may be subject to regulatory restrictions in certain jurisdictions. Users are solely responsible for ensuring compliance with applicable local laws and regulations before using any products or services mentioned on this website.
PallaPay does not guarantee the accuracy, completeness, or timeliness of any information published and accepts no liability for any loss or damages arising from reliance on the content. Any opinions expressed are those of the respective authors and may change without notice.
Certain services, features, or products referenced may be provided through third-party partners, licensed entities, or affiliated service providers subject to separate terms and regulatory approvals. Availability of services may vary by country or region.
This website may contain references to digital assets, virtual currencies, or blockchain-related services that are not available to residents of certain jurisdictions, including where prohibited by law. Nothing on this website constitutes an offer, solicitation, or recommendation to buy or sell any financial instrument or virtual asset.