Tag: Crypto Utility

  • How to Spend Crypto: 2026 Guide to Utility and Trading

    How to Spend Crypto: 2026 Guide to Utility and Trading

    What if your digital wallet wasn’t just a vault for waiting, but a high-speed engine for global market entry? For years, the conversation around digital assets focused on holding for future gains, yet the real power lies in immediate utility. Understanding how to spend cryptocurrency in 2026 has shifted from buying retail goods to accessing institutional-grade financial instruments. You’ve likely felt the frustration of limited merchant acceptance or the sting of high conversion fees when trying to move assets into traditional systems. It’s a common barrier that keeps many professionals from realizing the full potential of their holdings.

    This guide moves beyond simple retail purchases to show you how to leverage your crypto for financial transformation. You’ll learn how to bridge the gap between digital assets and high-potential markets like Gold (XAU/USD) and Forex CFDs with absolute precision. We’ll examine the mechanics of using crypto as a professional bridge to traditional finance; providing a clear roadmap to trade major currency pairs and commodities without the typical friction of legacy banking. By the end, you’ll see how modern utility turns static balances into active, growth-oriented capital.

    Key Takeaways

    • Transition from passive holding to active utility by redefining your digital assets as a tool for immediate market participation.
    • Discover how to spend cryptocurrency to enter lucrative financial sectors, specifically focusing on XAU/USD (Gold) and USD-based Forex CFDs.
    • Streamline your daily operations using integrated solutions such as the Pallapay Mastercard and retail POS terminals for instant fiat conversion.
    • Unlock the transformative potential of CFD trading to reshape your financial future through disciplined and strategic market engagement.
    • Bridge the gap between disruptive technology and institutional stability by utilizing a regulated, global ecosystem for all your crypto-to-fiat needs.

    What Does It Mean to Spend Cryptocurrency in 2026?

    To understand the modern financial landscape, you must look beyond simple digital ownership. By 2026, the global economy has matured to view digital assets as a liquid medium of exchange rather than just a volatile store of value. Spending now encompasses the direct exchange of assets for tangible goods, essential services, or sophisticated financial instruments. While foundational knowledge of what cryptocurrency is often focuses on decentralization, the current priority for users is institutional integration and immediate utility.

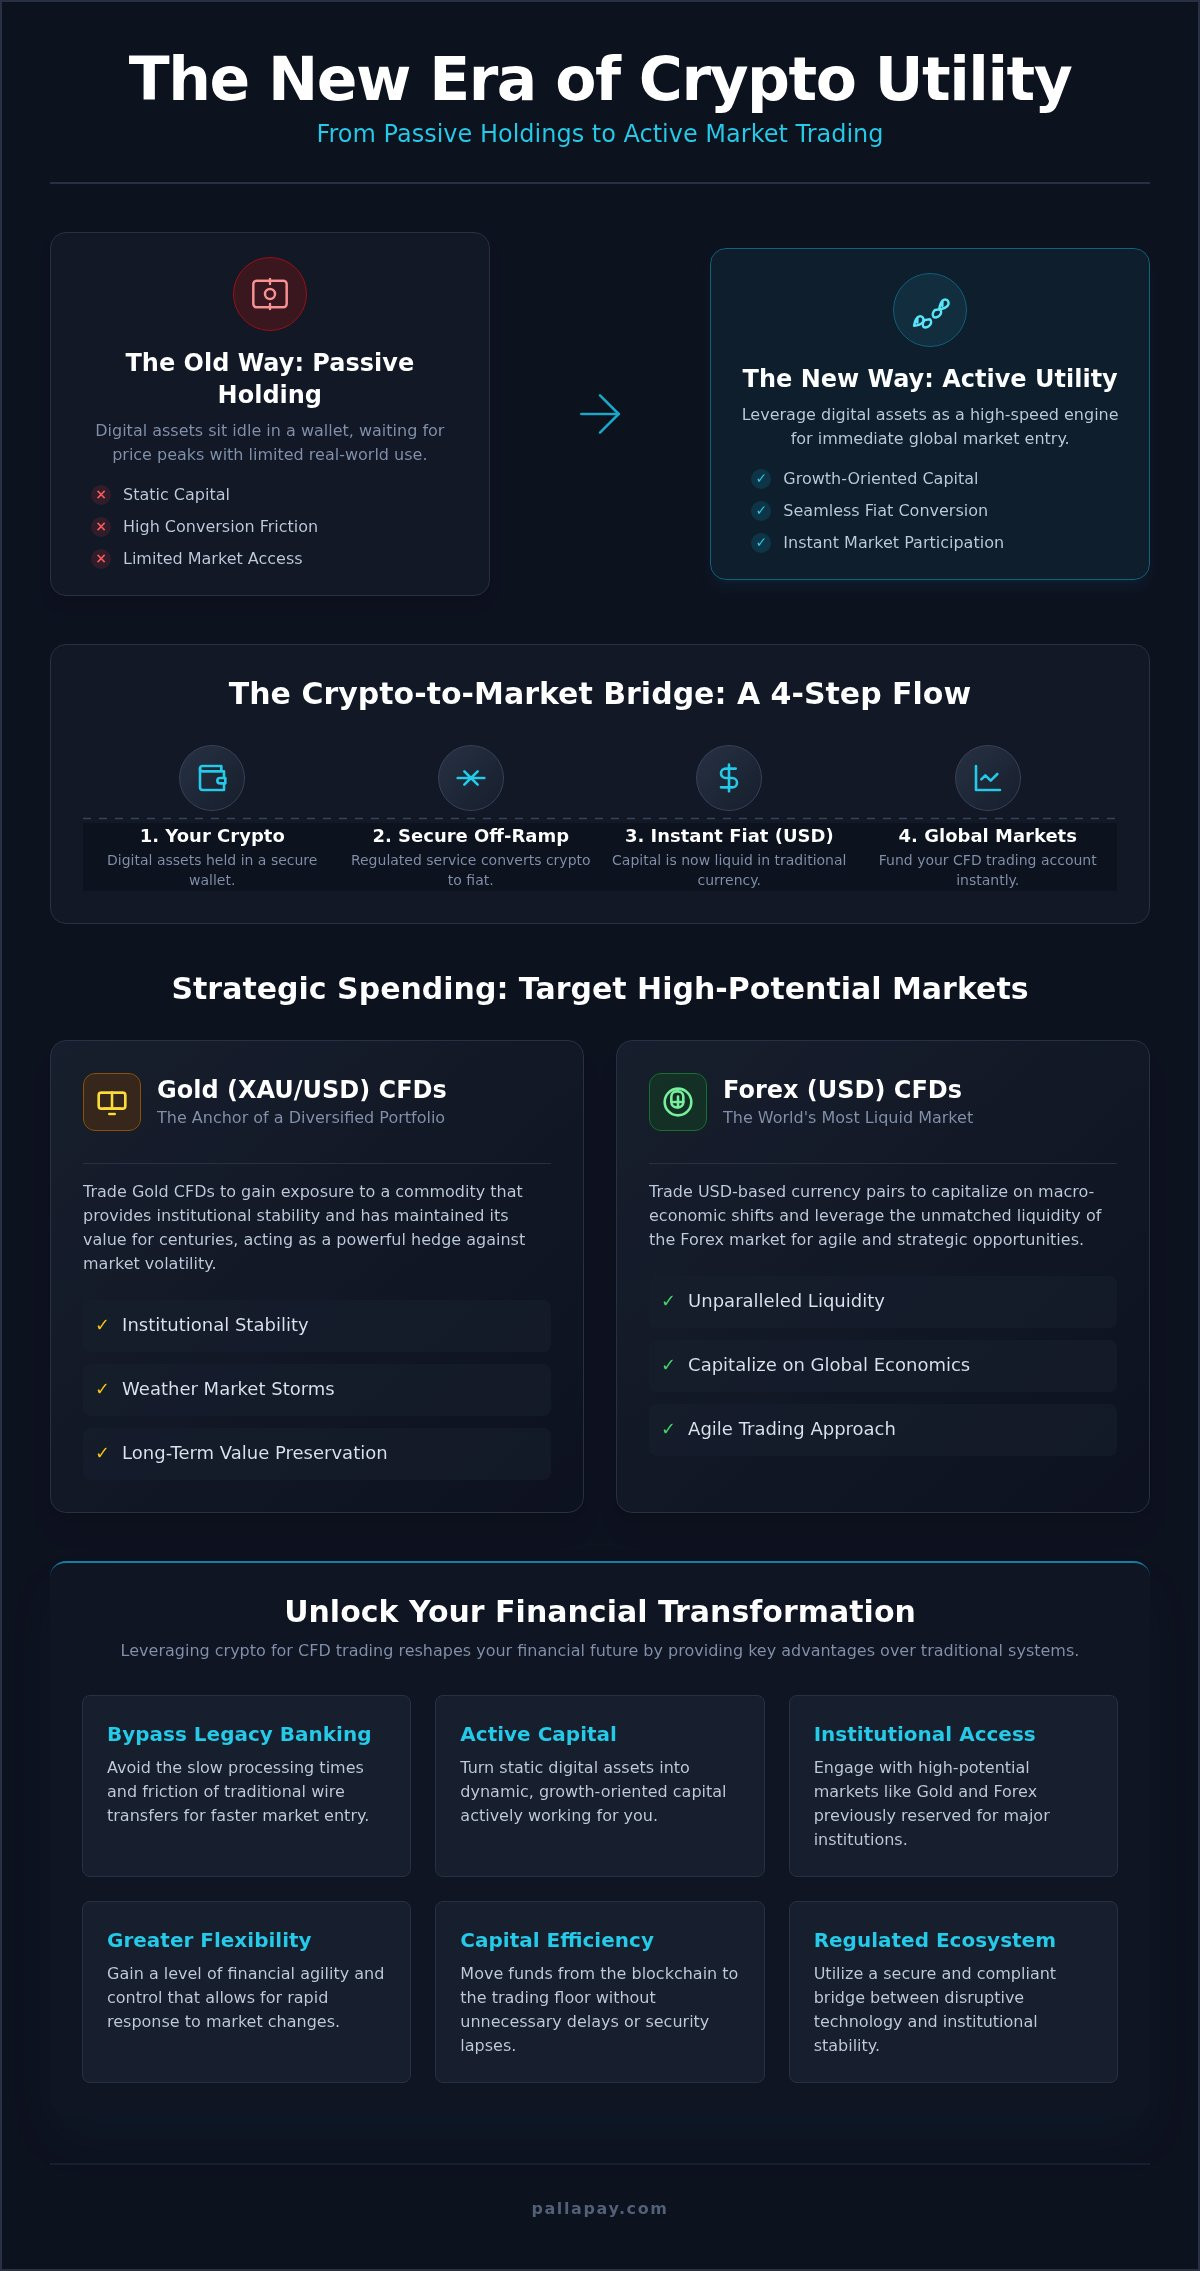
    The era of speculative holding has transitioned into an era of active utility. You don’t have to wait for price peaks to realize value; you can use your holdings to navigate daily life and expand your wealth. This movement is built on three main pillars: retail payments for consumer goods, direct bill settlement for operational costs—such as sourcing custom apparel and stationery from The CEO Creative—and strategic asset reallocation. This third pillar, strategic spending, represents the most significant shift. It allows you to move capital from the digital space into high-potential global markets like Gold and Forex without the friction of traditional banking delays. Learning how to spend cryptocurrency effectively requires recognizing these diverse pathways to liquidity.

    As retail acceptance grows, merchants are also looking for ways to increase consumer purchasing power; click here to see how Zip-Loan provides retailers and contractors with flexible financing and payment plan solutions.

    The Rise of the Crypto-Fiat Bridge

    The technical barrier between digital wallets and traditional bank accounts has finally dissolved. Regulated payment gateways now facilitate instant conversion at the point of sale, ensuring that volatility doesn’t impact your purchasing power. Stablecoins like USDT play a critical role here, acting as a reliable unit of account that preserves value during the transition from a digital wallet to a merchant’s ledger. A Crypto Off-Ramp is a regulated service that converts digital assets into bank-ready fiat, providing the essential liquidity needed for modern commerce.

    Retail vs. Strategic Spending

    Distinguishing between retail and strategic spending is vital for financial growth. Retail spending involves using assets for daily consumption, such as groceries or travel, typically through hardware POS terminals or integrated Mastercards. Strategic spending, however, focuses on long-term wealth transformation. By 2026, it’s standard practice to use cryptocurrency as a primary funding source for CFDs (Contracts for Difference). This allows you to spend your digital capital to gain exposure to XAU/USD (Gold) and major Forex pairs. This method bypasses the slow processing times of legacy systems, enabling a more agile approach to market opportunities and potential financial life changes.

    Spending Crypto on Financial Markets: Gold and USD CFDs

    Digital assets are no longer confined to the fringes of finance. By 2026, the most sophisticated investors recognize that how to spend cryptocurrency isn’t just a question of merchant acceptance; it’s a question of capital efficiency. By spending your digital holdings to fund live trading accounts, you bypass the sluggishness of traditional wire transfers. This transition requires a highly secure wallet and a regulated off-ramp to ensure that your capital moves from the blockchain to the trading floor without unnecessary delays or security lapses. Accessing global markets through digital assets represents a paradigm shift in how individual wealth is managed and deployed.

    Why XAU/USD and Forex are the 2026 Targets

    Gold (XAU/USD) serves as the primary anchor in a diversified portfolio. While digital assets offer high growth potential, gold provides the institutional stability required to weather market storms. By trading gold CFDs, you’re using your crypto to access a commodity that has maintained value for centuries. Simultaneously, the Forex market offers unparalleled liquidity. Trading USD-based pairs allows you to capitalize on the macro-economic shifts that define the global economy. This evolution requires you to move beyond the mindset of a casual holder. It demands the discipline of a professional trader who uses every available tool to protect and grow their capital. While you should always be aware of the risks of spending crypto, the integration of these markets offers a level of financial flexibility previously reserved for major institutions.

    Leveraging Your Crypto for Market Entry

    Contracts for Difference (CFDs) represent a transformative tool for the modern investor. They allow you to speculate on the price movements of gold and currency pairs without the logistical complexity of physical ownership. This makes market entry faster and more cost-effective. The process begins with your digital wallet, where your assets are held before being converted into fiat for trading. Speed is the decisive factor here. Capturing a sudden shift in the XAU/USD pair requires an infrastructure that can settle transactions instantly. You can learn how Pallapay facilitates fiat settlement to understand the mechanics of this high-speed transition. By bridging these two worlds, you turn your digital assets into a dynamic funding source that can react to global events in real-time. This isn’t just utility; it’s a strategic advantage that can fundamentally change your financial trajectory. If you’re ready to advance your strategy, using a professional crypto off-ramp can streamline your path to the global markets.

    Practical Ways to Spend Your Crypto Daily

  • Step 1: Deploy a Crypto Mastercard for global ATM withdrawals and merchant access.
  • Step 2: Utilize hardware POS terminals that accept direct digital asset transfers in physical locations.
  • Step 3: Purchase gift cards to access major platforms that haven’t yet integrated direct blockchain payments.
  • Step 4: Settle international bills using crypto-to-bank transfer services that deposit fiat directly into a recipient’s account.

The Convenience of Crypto Mastercards

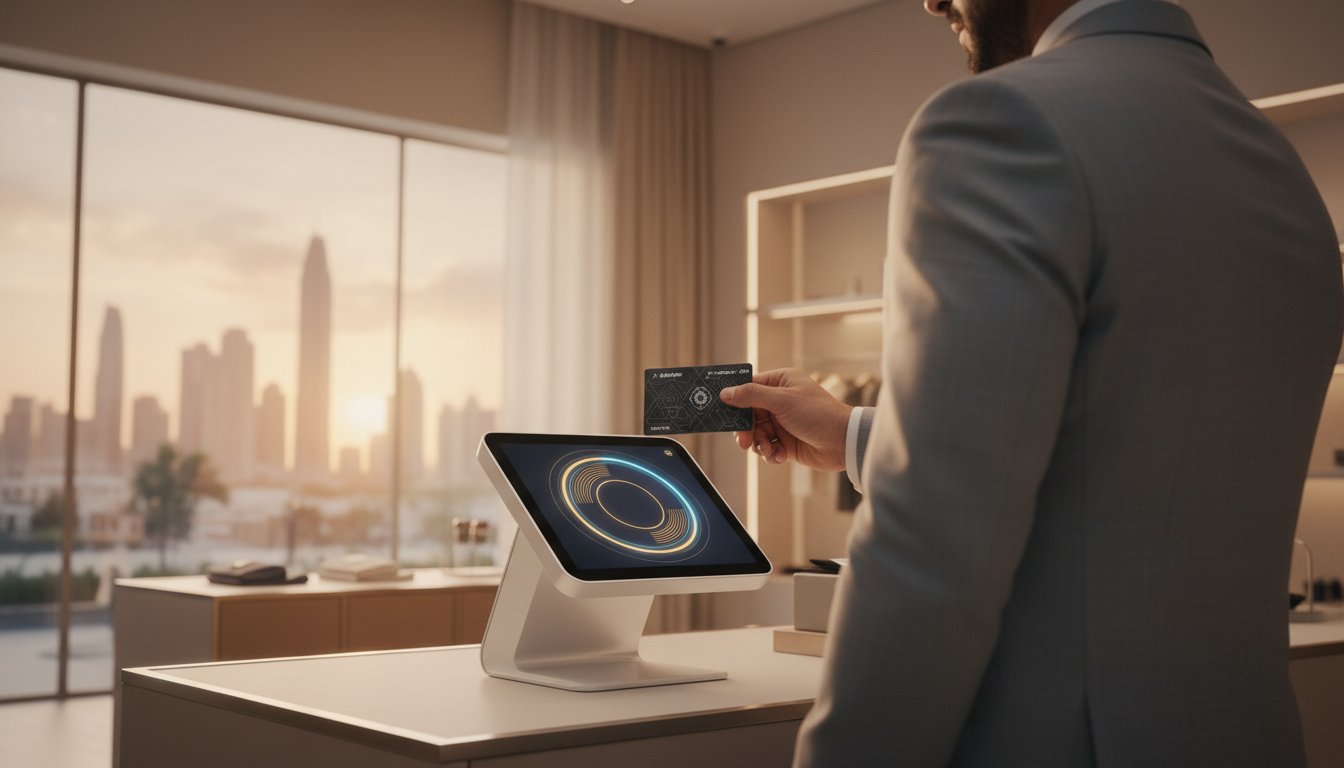
Physical and virtual cards serve as the definitive bridge between your digital wallet and the traditional retail sector. These cards facilitate real-time conversion at the moment of transaction. You hold your assets in your digital account; however, the merchant receives the exact amount in their local currency. This process eliminates the need for manual exchanges and protects your liquidity from unnecessary conversion delays. You can explore the utility of the Pallapay Wallet to see how integrated card management streamlines this workflow. It’s a professional solution for maintaining a global lifestyle without relying on traditional banking services.

In-Store Spending via POS Terminals

The hardware infrastructure for digital payments has evolved rapidly. Modern POS terminals now utilize NFC and QR code technology to facilitate instant, in-person transfers. This shift is particularly visible in high-end service sectors where speed and security are paramount. Many hotels and luxury retailers now prioritize crypto POS machines to accommodate international clients. These systems provide blockchain-verified transactions and instant receipts, offering a level of security that traditional networks often struggle to match. By using these terminals, you ensure that your spending remains secure and efficient. This seamless integration reinforces the role of digital assets as a standard component of modern commerce, allowing you to move through the world with the confidence of a global industry leader.
How to Spend Crypto: 2026 Guide to Utility and Trading

The Transformative Power of Gold and Forex Trading

Static holding is a strategy of patience, but professional trading is a strategy of precision. By 2026, the most successful market participants have moved beyond the “HODL” mentality to embrace active growth. This shift involves using realized digital gains to fund diversified, regulated trading accounts. Learning how to spend cryptocurrency to access these markets allows you to transition from a passive observer to an active architect of your financial future. It’s about moving capital from highly volatile digital tokens into established global benchmarks like Gold and the US Dollar. This proactive approach turns your digital wallet into a launchpad for broader economic engagement.

Changing Your Financial Trajectory

The transformation from a crypto enthusiast to a professional trader often begins with a shift in perspective. Many individuals who started with simple crypto savings now generate consistent income by leveraging Forex signals and deep market analysis. They don’t just wait for the next bull run; they capitalize on daily fluctuations in the currency markets. Gold (XAU/USD) remains the ultimate hedge in this environment. For crypto-native investors, gold provides a non-correlated asset class that balances the inherent risks of the blockchain space. This strategic reallocation ensures that your wealth isn’t tied to a single technology, but is instead grounded in the fundamental pillars of global commerce. It’s a calculated move that replaces hope with a structured trading plan.

Risk Management in CFD Trading

CFD trading involves high risk and requires a sophisticated understanding of leverage. To spend crypto responsibly, you should only allocate a portion of your total portfolio to these high-potential trading environments. Risk management is the cornerstone of institutional financial reliability. It requires the use of regulated platforms and MSB-registered providers to ensure your capital is handled with the highest level of security. By using a secure bridge to convert your digital assets into fiat-settled trading capital, you maintain control over your exposure. You can effectively manage your market entry and exit points while keeping your primary digital holdings secure. This disciplined approach is what separates long-term success from short-term speculation. If you’re ready to begin your transition into professional markets, you can convert crypto to fiat instantly to fund your trading journey.

Pallapay serves as the definitive destination for users seeking a professional bridge between digital assets and traditional finance. By maintaining MSB registrations in the USA and Canada, the platform provides the institutional stability required for serious market participation. Understanding how to spend cryptocurrency in 2026 means prioritizing providers that offer both security and global reach. With a presence in over 180 countries, the ecosystem is designed to handle complex background processes so you can focus on your broader financial strategy. This reliability ensures that your transition from a digital wallet to a fiat-settled environment is both secure and compliant.

Temporal efficiency is the hallmark of the modern financial era. Market windows for XAU/USD or major Forex pairs can open and close within minutes. Using the Off-Ramp allows you to convert digital assets into bank-ready fiat with the speed necessary to capture these opportunities. It’s not just about spending; it’s about the velocity of your capital. When you can move assets instantly, you gain a competitive edge that static holders simply don’t possess.

From Wallet to Market: The Pallapay Advantage

For those managing high-frequency operations, the Payment API facilitates automated financial flows, reducing manual intervention and potential errors. This technical integration allows for a seamless connection between your digital holdings and live trading environments. Serious traders often require higher liquidity than standard retail exchanges provide. This is where OTC desks become essential, handling large-scale conversions with the discretion and efficiency that institutional-grade trading demands. This infrastructure bridges the gap between disruptive innovation and the reliability of established financial practices, ensuring that large moves don’t disrupt your momentum.

Getting Started with Your 2026 Financial Strategy

Setting up your account is a straightforward progression toward financial transformation. First, verify your identity to align with global regulatory standards. Second, integrate your digital wallet to enable seamless asset transfers. Finally, choose your primary utility path, whether it’s funding a Forex account or managing global e-commerce expenses. By adopting these tools, you’re not just holding a currency; you’re operating a sophisticated financial engine. The lack of friction in these services allows you to scale your operations without being overwhelmed by technical mechanics. Start spending strategically today to accelerate your progress toward a transformed financial future.

Mastering Your Digital Capital for Global Markets

The evolution of digital finance has transformed the static wallet into a dynamic gateway for wealth creation. You’ve seen that the choice of how to spend cryptocurrency in 2026 is no longer limited to basic retail transactions; it’s about the strategic reallocation of assets into high-potential markets. By utilizing professional tools to fund Gold and Forex CFD trading, you move beyond passive holding to actively drive your financial life toward a new trajectory. This transition requires a partner that prioritizes institutional reliability and global reach. It’s about turning digital innovation into stable, long-term growth.

Pallapay provides this essential bridge through a regulated ecosystem with MSB registrations in the USA and Canada. With an infrastructure serving over 180 countries and advanced Mastercard and POS solutions, the platform ensures your capital moves with the speed and safety necessary for modern commerce. It’s time to stop waiting for market shifts and start creating them by leveraging the full utility of your assets. Your journey toward financial transformation begins with a single, decisive move.

Fund your future and start spending strategically with Pallapay.

Frequently Asked Questions

How can I spend cryptocurrency for daily purchases in 2026?

You spend it via integrated hardware POS terminals and branded Mastercards. These tools allow for real-time conversion at the point of sale. You can use your digital assets at millions of locations worldwide that accept standard card payments. This method removes the need to manually exchange funds before shopping. It’s a seamless way to integrate digital assets into your everyday routine without relying on traditional bank accounts.

Is it possible to use cryptocurrency to trade Gold and Forex?

Yes, you can use digital capital to fund accounts for Gold and Forex trading. By utilizing a professional off-ramp, you convert your crypto into fiat-settled balances ready for the CFD market. This allows you to speculate on the price of XAU/USD or major currency pairs. It’s a strategic move that provides exposure to institutional-grade financial instruments while maintaining the liquidity of your digital portfolio.

What are the benefits of spending crypto via a Mastercard?

The primary benefit is global accessibility and instant liquidity. A Pallapay Mastercard allows you to access ATMs and merchants in over 180 countries without the friction of legacy banking. The card facilitates an automatic conversion from your crypto balance to local fiat currency at the moment of transaction. This ensures you always have spending power, regardless of whether the merchant directly accepts digital tokens. It’s an efficient tool for managing a global lifestyle.

How do I convert my crypto to fiat for CFD trading?

You convert your assets by using a dedicated crypto off-ramp or an OTC desk for larger volumes. This process settles your digital holdings into traditional currency like USD, which is then used to fund your CFD trading account. Understanding how to spend cryptocurrency for market entry is vital for capturing real-time fluctuations in gold or forex. Using a regulated provider ensures that your funds are transferred quickly and securely to your live trading environment.

Are crypto-to-fiat payments secure and regulated?

Security is maintained through institutional-grade encryption and adherence to global regulatory frameworks. Pallapay operates as a regulated entity with MSB registrations in the United States and Canada. These certifications ensure that all transactions meet strict compliance standards. By choosing a regulated gateway, you protect your capital from the risks often associated with unverified platforms. It provides a stable environment for both individual users and large-scale business operations.

Can I pay my bills directly with cryptocurrency?

You can settle international bills through crypto-to-bank transfer services. This feature allows you to send digital assets from your wallet, which are then deposited as fiat directly into the recipient’s bank account. It’s an ideal solution for managing recurring expenses or professional services across borders. This method bypasses the high fees and slow processing times typical of traditional wire transfers, making it a faster alternative for global bill settlement.

What is the difference between retail spending and strategic spending?

Retail spending involves everyday consumer purchases like groceries, travel, or hardware through POS terminals. Strategic spending focuses on the reallocation of digital gains into high-potential financial markets. This includes funding accounts for Gold and Forex CFD trading to achieve long-term financial transformation. While retail spending manages your lifestyle, strategic spending is designed to grow your capital. Both are essential components of a modern strategy for how to spend cryptocurrency effectively.

How do I find merchants that accept crypto in 2026?

Most merchants accept crypto indirectly through advanced POS infrastructure and Mastercard networks. You don’t need to look for a specific sign if you use a card that converts assets in real-time. Additionally, many high-end sectors like luxury hotels and e-commerce platforms now use dedicated payment gateways. These systems allow for direct blockchain-verified payments. It’s now standard for modern businesses to accommodate digital assets as a primary form of payment.

Disclaimer

The information provided on this website and blog is for general informational and educational purposes only and does not constitute financial, investment, legal, tax, or other professional advice.
Cryptocurrency and digital asset services may be subject to regulatory restrictions in certain jurisdictions. Users are solely responsible for ensuring compliance with applicable local laws and regulations before using any products or services mentioned on this website.
PallaPay does not guarantee the accuracy, completeness, or timeliness of any information published and accepts no liability for any loss or damages arising from reliance on the content. Any opinions expressed are those of the respective authors and may change without notice.
Certain services, features, or products referenced may be provided through third-party partners, licensed entities, or affiliated service providers subject to separate terms and regulatory approvals. Availability of services may vary by country or region.
This website may contain references to digital assets, virtual currencies, or blockchain-related services that are not available to residents of certain jurisdictions, including where prohibited by law. Nothing on this website constitutes an offer, solicitation, or recommendation to buy or sell any financial instrument or virtual asset.
  • How to Spend Cryptocurrency: The Complete 2026 Utility Guide

    How to Spend Cryptocurrency: The Complete 2026 Utility Guide

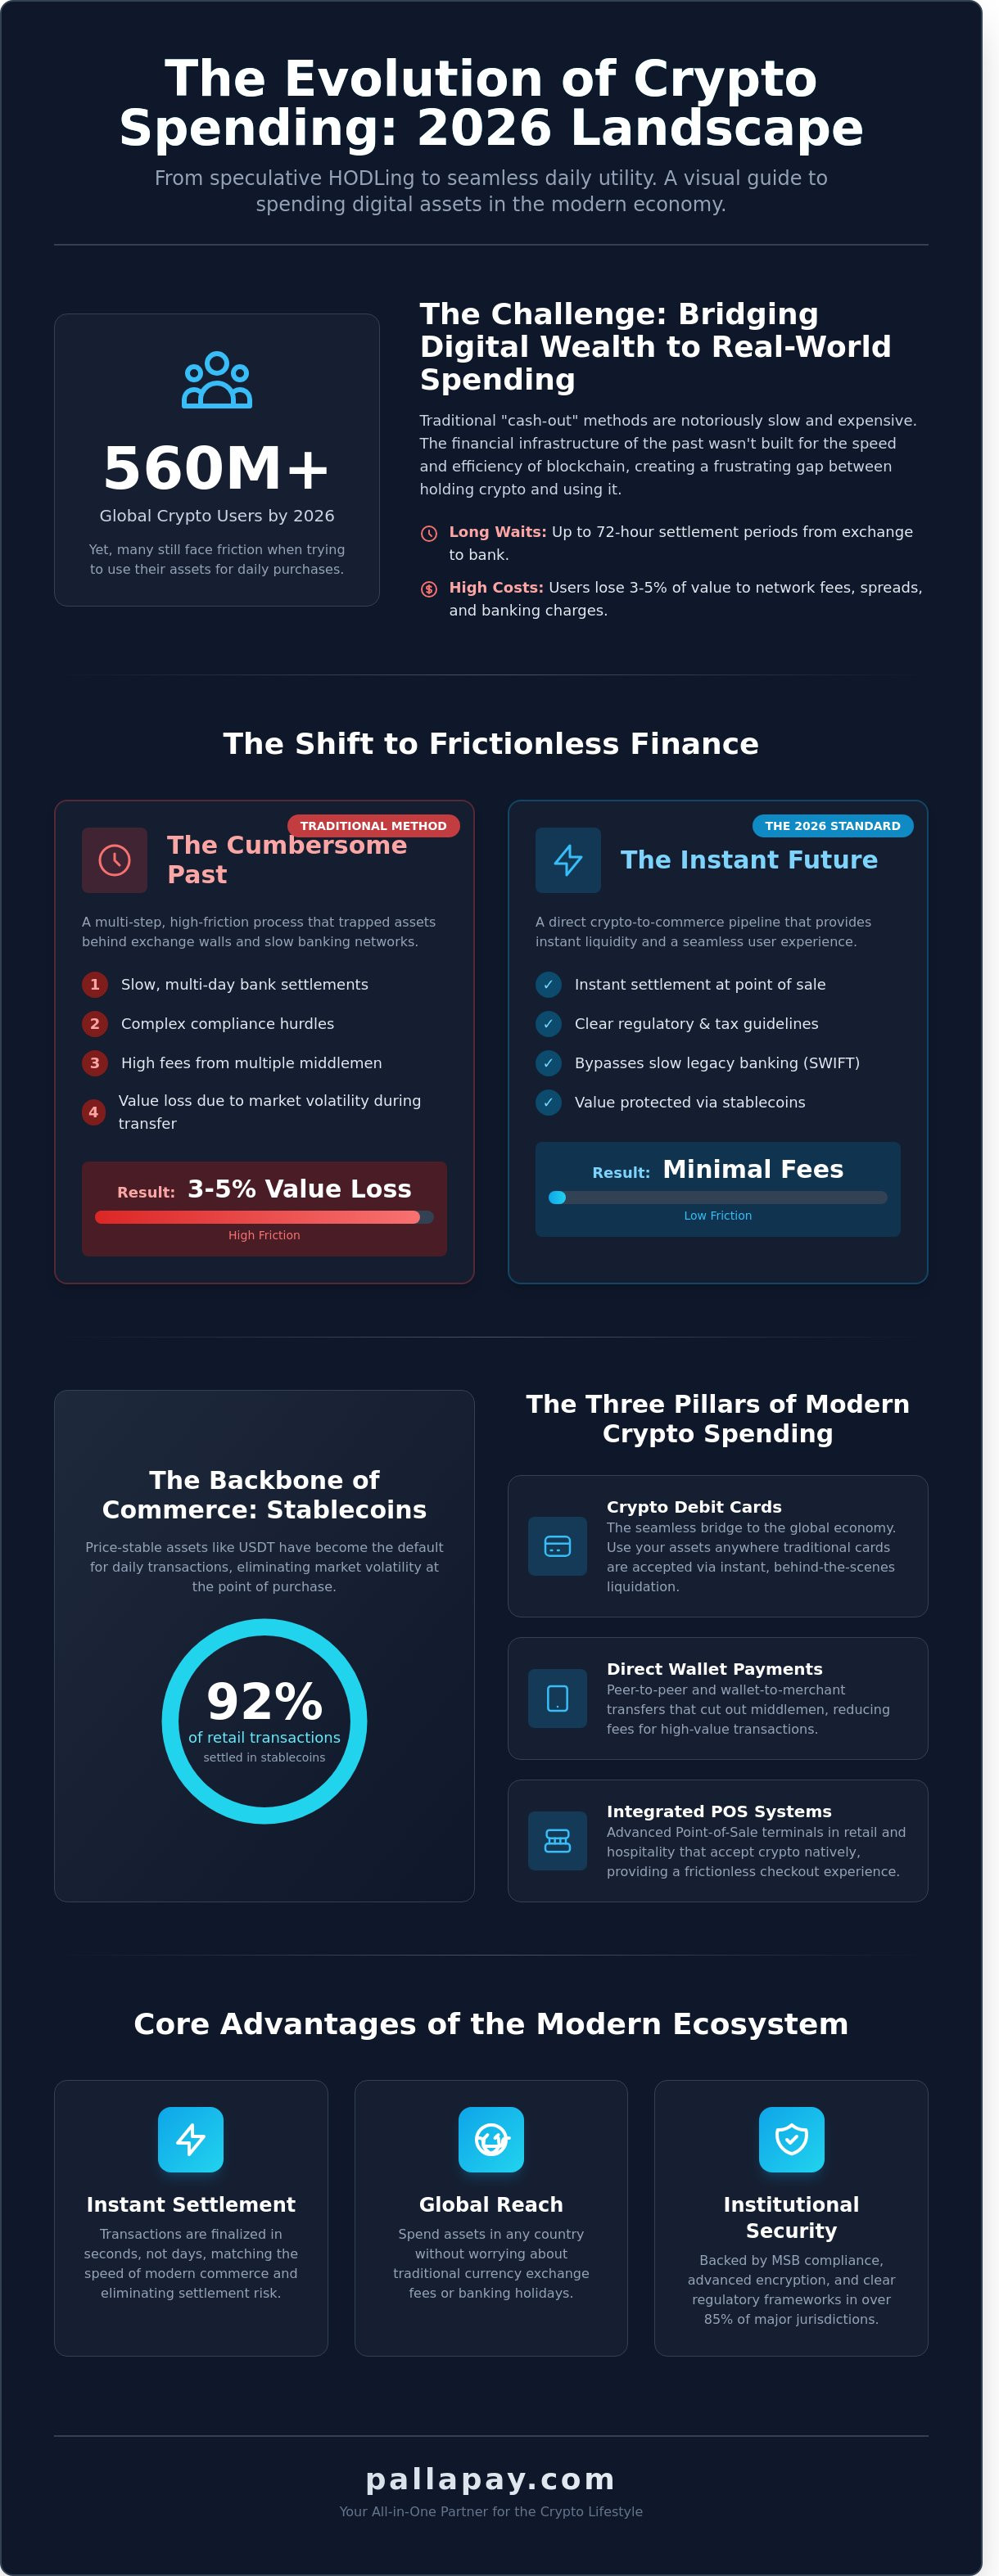
    By the start of 2026, the number of global crypto users surpassed 560 million, yet a significant portion of these holders still struggle with the practical logistics of daily utility. You’ve likely experienced the frustration of high network fees on small retail purchases or the cumbersome multi-step process required to convert digital assets into spendable fiat. Learning how to spend cryptocurrency shouldn’t feel like a technical chore; it should be as seamless as a standard contactless payment. We agree that you deserve to maintain the security of your long-term holdings while accessing the instant liquidity required for modern commerce.

    This guide provides the definitive roadmap to achieving that balance. You’ll discover the most efficient ways to use your assets for real-world purchases through professional-grade debit cards and direct merchant integrations that eliminate unnecessary middleman fees. We’ll preview the latest 2026 infrastructure, including instant settlement gateways and OTC liquidity pools, ensuring you’re equipped for the future of payments. By the end of this article, you’ll have a clear strategy for moving your capital with absolute confidence and zero friction.

    Key Takeaways

    • Transition from speculative holding to active utility by leveraging the regulatory clarity and security standards of the modern digital economy.
    • Master how to spend cryptocurrency through instant liquidation tools that provide a seamless transaction experience at any global merchant.
    • Discover how direct payment gateways and advanced POS systems are integrating digital assets into the luxury retail and hospitality sectors.
    • Optimize your financial strategy by navigating complex fee structures and utilizing stablecoins to secure value against market volatility.
    • Identify the critical advantages of an all-in-one ecosystem that bridges the gap between blockchain innovation and institutional financial reliability.

    The Evolution of Crypto Utility: Why Spending is the New HODLing

    The 2026 economy has fundamentally redefined the relationship between users and digital assets. While the early 2020s were dominated by price speculation, the current era prioritizes functional liquidity. Understanding What is cryptocurrency? is no longer a question of technical whitepapers; it’s about recognizing it as a superior medium of exchange. This shift occurred because global regulatory frameworks, including the widespread adoption of MSB registrations by late 2024, provided the institutional safety net retail users required. People have transitioned from a “number go up” mentality to a utility-first mindset where crypto is viewed as a global, borderless bank account.

    Security and clarity have replaced the uncertainty of the past. By 2025, over 85% of major jurisdictions established clear tax and compliance guidelines for digital payments, making the process of how to spend cryptocurrency as routine as swiping a plastic card. This psychological transition is backed by three main spending pillars: crypto-linked debit cards, direct wallet-to-wallet transfers, and integrated Point of Sale (POS) systems. Each pillar serves a specific need, from daily coffee purchases to high-value real estate transactions, ensuring that digital wealth is never trapped behind an exchange wall.

    The Problem with Traditional Cash-Out Methods

    Traditional banking systems haven’t kept pace with the speed of blockchain. Withdrawing funds from an exchange to a legacy bank account often involves a 72 hour waiting period and multiple compliance hurdles. The hidden costs are equally frustrating. Users frequently lose between 3% and 5% of their value through a combination of spread markups, network gas fees, and bank processing charges. Modern fintech providers have solved this by creating a direct crypto-to-cash pipeline. These platforms bypass the slow settlement times of the SWIFT network, offering instant conversion at the moment of purchase. This eliminates the friction that once made crypto spending a logistical nightmare for the average person. Understanding the fundamental differences in crypto vs traditional banking reveals why instant settlement has become the new standard for modern commerce.

    Defining the 2026 Spending Landscape

    Stablecoins, specifically USDT, have become the backbone of daily commerce due to their price stability and high liquidity. In 2026, 92% of retail crypto transactions are settled in stablecoins to avoid the volatility of legacy assets. Instant liquidity providers have replaced the old model of slow-settlement exchanges, allowing for real-time conversion at the merchant level. The key to managing this effectively is using a secure crypto wallet that supports multi-chain assets and offers direct integration with payment gateways. This all-in-one approach is the Future of Payments, where your wallet acts as both a savings account and a high-speed checking account. Learning how to spend cryptocurrency efficiently requires a platform that prioritizes instant settlement and global accessibility. This evolution ensures that your digital assets are always ready for real-world use, providing a level of financial freedom that traditional fiat systems cannot match.

    • Instant Settlement: Transactions are finalized in seconds, not days.
    • Global Reach: Spend your assets in any country without currency exchange fees.
    • Security: Advanced encryption and MSB compliance protect every transaction.

    Crypto Debit Cards: The Most Seamless Way to Spend

    A crypto debit card acts as the definitive bridge between your digital portfolio and the global economy. It functions by allowing you to utilize your assets at any merchant terminal that accepts traditional payment networks. While understanding how cryptocurrency works is fundamental for any investor, these cards remove the technical burden from the point of sale. You don’t need to worry about wallet addresses or network confirmations at the checkout counter. The card handles the heavy lifting of finance behind a familiar plastic or digital interface.

    The backend mechanics rely on instant liquidation. When you swipe your card or tap your phone, the provider initiates a real-time settlement process. They instantly sell the necessary portion of your cryptocurrency for the exact amount of fiat currency required by the merchant. This process happens in milliseconds, ensuring that the seller receives local currency while you successfully execute how to spend cryptocurrency without manual exchange steps. By 2026, these systems have evolved to offer near-zero latency, making the experience indistinguishable from using a standard bank card.

    Users typically choose between two primary formats: virtual and physical. Virtual cards are optimized for the digital-first economy, providing a secure way to handle e-commerce transactions and subscription services. Physical cards remain essential for retail environments and global travel where tactile hardware is required. Additionally, two distinct funding models exist. Some cards require a pre-paid balance where you manually move funds to a fiat wallet. Others offer direct wallet linking, which maintains your liquidity in crypto until the very second a transaction occurs. This second model is often preferred by those who want to maximize their exposure to market movements while maintaining spending power.

    Key Features of a High-Performance Crypto Card

    Top-tier cards prioritize transparency in conversion rates. High-performance providers offer tight spreads, often below 0.5%, to ensure you retain the maximum value of your assets. Security is equally paramount. Modern cards integrate 2FA, biometric authentication, and the ability to instantly freeze the card via a mobile app if it’s misplaced. For global travelers, ATM withdrawal capabilities are a non-negotiable feature, allowing for the conversion of crypto into physical cash at thousands of international hubs.

    The Pallapay Mastercard Advantage

    The Pallapay Mastercard represents the pinnacle of this financial evolution by integrating directly into a comprehensive payment ecosystem. It offers unparalleled global acceptance, allowing users to spend their assets in over 180 countries without the friction of traditional currency exchange fees. Because the card is backed by a regulated MSB provider, users benefit from an institutional level of trust and stability that smaller, unregulated startups cannot match. This card isn’t just a tool; it’s a gateway to the future of payments.

    Choosing the right card is the most effective strategy for anyone looking for how to spend cryptocurrency efficiently in a retail or digital environment. If you’re ready to transition from a passive holder to an active participant in the new economy, you can apply for a card that fits your lifestyle. This shift toward instant, secure, and global liquidity is what defines the modern financial landscape.

    Direct Merchant Payments and Crypto POS Systems

    By 2026, the question of how to spend cryptocurrency has moved from a technical hurdle to a standard checkout option. Global e-commerce platforms now integrate “Pay with Crypto” buttons as a primary payment method alongside traditional credit cards. This shift eliminates the friction of converting assets to fiat before making a purchase. While understanding how cryptocurrency works is still valuable for security, the user experience is now as simple as any digital wallet transaction. Pallapay serves as the professional bridge in this evolution, providing the infrastructure that makes these transactions secure and reliable.

    Physical retail environments have seen a 42% increase in Crypto POS installations since 2024. Merchants utilize fiat settlement to protect their margins. This technology allows a customer to pay in Bitcoin or Ethereum while the merchant receives USD or EUR instantly. It removes the risk of market volatility for the business. This is the Future of Payments, where the complexity of blockchain is hidden behind a sophisticated, user-friendly interface.

    Direct merchant payments represent a significant shift in financial autonomy. By utilizing a direct gateway, you bypass the 1.5% to 2% “convenience” fees typically charged by crypto-backed debit cards. This peer-to-merchant model is the purest form of digital commerce. It utilizes the underlying blockchain to settle value without requiring a third-party processor to act as a custodian of your funds during the transaction. These terminals are not merely payment processors; they are sophisticated liquidity management tools that empower both the spender and the seller.

    How to Use a Crypto POS Terminal In-Store

    Modern retail interactions are built for speed and efficiency. When you’re ready to pay, the merchant enters the transaction amount into their terminal. You simply scan the generated QR code with your mobile wallet app. In 2026, Layer 2 scaling solutions ensure an Instant confirmation, meaning you won’t stand at the counter waiting for block confirmations. Many high-end terminals now support NFC technology. This allows for a “Tap to Pay” experience that feels identical to using a traditional debit card. It’s a seamless process that connects your digital wealth to the physical world without intermediate card providers or unnecessary delays.

    Industry-Specific Adoption

    The hotel industry has led the way in global crypto integration. Large chains use these systems to bypass the 3.5% fees often associated with international credit card processing. This simplifies international bookings and reduces costs for the traveler. In luxury retail stores, high-ticket items like watches or designer apparel are increasingly purchased via crypto. This method avoids the restrictive daily spending limits of traditional banking institutions. Shoppers save an average of 2.1% by avoiding foreign exchange markups during cross-border travel. This all-in-one approach to global finance makes how to spend cryptocurrency a question of convenience rather than capability. The system handles the heavy lifting of technology behind the scenes, ensuring every transaction is a standard, effortless business operation.

    How to Spend Cryptocurrency: The Complete 2026 Utility Guide

    Optimizing Your Spending: Fees, Security, and Strategy

    By 2026, mastering how to spend cryptocurrency requires more than just a digital wallet; it demands a sophisticated understanding of the underlying financial architecture. Efficiency is the new benchmark for the modern crypto user. You aren’t merely transferring tokens. You’re navigating a multi-layered fee stack that can erode your purchasing power if left unmanaged. This stack typically includes network gas fees, provider commissions that average 0.8% to 1.5%, and FX spreads that vary by liquidity provider. The structural advantages of crypto vs traditional banking become clear when you consider that legacy wire transfers often carry hidden fees exceeding 6% for cross-border transactions.

    Strategic timing is your most effective tool against market volatility. While the 2026 market has matured, price swings of 5% within a single day remain common. Smart spenders use stablecoins like USDT or USDC to lock in value when their volatile assets hit specific price targets. This approach ensures that your budget remains predictable, regardless of the broader market’s movement. It’s a professional method for maintaining liquidity without exiting the blockchain ecosystem entirely.

    Security protocols must evolve alongside your spending habits. You should never initiate a payment directly from your primary cold storage or long-term savings address. Instead, adopt a “spend-and-replace” or “pre-funded” model. Maintain a separate hot wallet for daily expenses, holding only 3% to 7% of your total portfolio at any given time. This firewall strategy limits your exposure to malicious merchant scripts or phishing attempts that target active spenders. For a comprehensive approach to safeguarding your holdings, reviewing the latest crypto security protocols for protecting digital assets in 2026 will help you build a multi-layered defense against sophisticated threats.

    Regulatory compliance is another pillar of the 2026 landscape. With over 45 countries now implementing real-time tax reporting frameworks, keeping meticulous records is vital. Every transaction is a taxable event in many jurisdictions. Using platforms that offer automated cost-basis tracking and instant tax exports will save you dozens of hours during the annual filing season. Clean data is the foundation of financial freedom.

    Minimizing Transaction Friction

    Choosing the correct network is the fastest way to reduce overhead. By Q1 2026, the cost difference between networks is stark. An ERC20 transfer might cost $12 during peak congestion, while a TRC20 transaction remains stable at approximately $1. Layer 2 solutions like Arbitrum or the Lightning Network have pushed micro-payment costs below $0.05, making small coffee purchases finally viable. Always look for “zero-fee” environments where internal transfers between users of the same ecosystem are settled instantly without touching the mainnet.

    Protecting Your Digital Assets While Traveling

    Travelers face unique risks, from unsecured Wi-Fi to physical theft. Virtual cards provide an essential layer of anonymity and security for online bookings and recurring subscriptions. For those requiring significant liquidity, such as purchasing luxury goods or real estate abroad, high-volume OTC desks are the standard. These desks bypass retail slippage and provide fixed rates for amounts exceeding $10,000. In global financial hubs, selling USDT in Dubai for physical cash remains a premier strategy for travelers who need immediate, reliable local currency without the delays of traditional banking transfers.

    Effective crypto management is about removing the barriers between your digital wealth and its real-world utility. By focusing on network efficiency and robust security, you transform a complex technical process into a seamless financial routine. This is the hallmark of a visionary partner in the fintech space.

    Ready to elevate your financial strategy? Explore the Pallapay ecosystem for instant settlements and global payment solutions.

    Choosing the Right Partner for Your Crypto Lifestyle

    Selecting a financial partner in 2026 requires more than looking at transaction fees. Security and institutional-grade compliance serve as the bedrock of any sustainable strategy for how to spend cryptocurrency. You must prioritize platforms with Money Service Business (MSB) registrations. These licenses ensure the provider adheres to strict Anti-Money Laundering (AML) and Know Your Customer (KYC) protocols, protecting your assets from the volatility of unregulated shadow-banking. A regulated partner offers a legal bridge between digital assets and the legacy banking system; it provides you with the same protections you expect from a traditional bank.

    Efficiency thrives within an all-in-one ecosystem. Managing separate wallets, exchanges, and payment cards creates unnecessary complexity and increases the risk of manual errors. A unified platform provides instant liquidity. It allows you to convert assets and settle payments in milliseconds. This vertical integration means your exchange, debit card, and merchant services work as a single machine. By late 2025, data showed that users on integrated platforms saved an average of 3.2% on hidden conversion spreads compared to those using fragmented services across different providers.

    Your journey from digital wallet to retail checkout follows a precise four-step process. First, complete your identity verification to unlock full account limits. Second, fund your account via a bank transfer or direct crypto deposit. Third, issue a virtual or physical card within the app. Finally, use your balance at any contactless terminal globally. It’s that simple. To maintain a secure and efficient experience, follow this final checklist:

    • Enable biometric or hardware-based Two-Factor Authentication (2FA) for all withdrawals.
    • Monitor transaction history via real-time push notifications to detect unauthorized activity.
    • Only use platforms that offer segregated accounts for user funds to ensure solvency.
    • Verify the merchant uses a secure gateway to prevent data skimming during the checkout process.

    The Pallapay Difference: Security and Compliance

    We maintain a rigorous standard of operational integrity across the US, Canada, and the UAE. Our 2024 expansion solidified our role as a global leader in cross-border settlements. We don’t just serve individuals; our Payment API enables thousands of merchants to accept digital assets with instant fiat conversion. This infrastructure ensures that when you’re wondering how to spend cryptocurrency at your favorite store, the backend technology is stable and reliable. Our 24/7 global support team provides expert guidance for every transaction, ensuring you’re never left alone in the new financial frontier.

    Future-Proofing Your Finances

    By late 2026, industry analysts predict that 92% of global retailers will accept at least one form of digital payment. Building a transaction history with a regulated provider today aids your future financial mobility. It helps when applying for credit or mortgages that recognize crypto-wealth as a legitimate asset class. The Future of Payments isn’t a distant concept; it’s a functional reality we’ve already built. Start your journey with the Pallapay ecosystem today and experience the speed of instant, global finance.

    Master the Future of Global Payments

    The transition from passive holding to active utility marks the next phase of the digital economy. You’ve explored how integrated debit cards and merchant POS systems bridge the gap between blockchain assets and daily commerce. Success requires a strategy focused on low-friction settlements and robust security protocols. As global adoption scales, understanding how to spend cryptocurrency efficiently becomes your competitive advantage in a borderless market.

    Pallapay has led this evolution since 2018, providing instant crypto-to-fiat settlements that eliminate volatility risks. We’ve secured official MSB registration in both the USA and Canada to ensure your transactions meet the highest institutional standards. Today, thousands of merchants globally rely on our infrastructure to power their financial operations. You don’t need to navigate the complexities of liquidity alone when you have a visionary partner handling the heavy lifting behind the scenes.

    Experience the future of payments with the Pallapay Mastercard and join a global network built on trust and speed. It’s time to unlock the full potential of your digital wealth with confidence.

    Frequently Asked Questions

    Is it legal to spend cryptocurrency at retail stores?

    Yes, spending cryptocurrency is legal in over 130 jurisdictions globally as of 2026. In the United Arab Emirates, the Virtual Assets Regulatory Authority (VARA) provides a clear framework for retail transactions. You can use your digital assets at thousands of registered merchants who utilize secure payment gateways. This regulatory clarity ensures every transaction follows local financial laws while maintaining the speed of blockchain technology.

    How much are the fees when I spend crypto using a debit card?

    Transaction fees typically range between 0% and 2.5% depending on your card tier and the specific liquidity provider. Pallapay offers competitive rates that often eliminate the high 3% foreign exchange fees associated with traditional banking. These costs are calculated instantly at the point of sale. You’ll see the exact conversion rate before you confirm the payment, ensuring total transparency during your daily purchases.

    Do I need to pay taxes on every crypto purchase I make?

    Most tax authorities, including the IRS in the United States and HMRC in the UK, treat every crypto transaction as a taxable event. If your asset’s value increased since you acquired it, you’ll owe capital gains tax on that difference. In 2026, automated reporting tools integrated into your wallet can track these 15% to 20% tax liabilities. It’s essential to maintain digital records of your cost basis to ensure accurate annual filings.

    Which cryptocurrency is the best for daily spending in 2026?

    Stablecoins like USDT and USDC are the most efficient options for daily spending due to their 1:1 peg with the US Dollar. These assets eliminate the 10% daily volatility often seen in Bitcoin or Ethereum. When you learn how to spend cryptocurrency for routine items, using stablecoins ensures the price you see on the tag is the price you pay. They provide a reliable bridge between digital innovation and price stability.

    Can I use my crypto to pay for a hotel or luxury car directly?

    You can pay for high-value assets like luxury cars or five-star hotel stays directly through specialized merchant gateways. In 2026, over 45% of luxury retailers in Dubai and Singapore accept direct crypto transfers for invoices exceeding $50,000. These transactions often bypass traditional wire transfer delays that can take 3 to 5 business days. Instead, your payment settles in minutes, allowing for instant ownership transfer of your luxury goods.

    What happens if a transaction fails at a Crypto POS machine?

    If a transaction fails at a point-of-sale terminal, your funds typically remain in your wallet or are automatically reversed within 120 seconds. This usually occurs due to network congestion or insufficient liquidity for the specific pair. Our system provides instant notifications to your mobile device explaining the exact reason for the 404 or timeout error. You can then retry the payment or select a different asset to complete your purchase without delay.

    How do I convert my crypto back to cash instantly if I need it?

    You can convert your digital assets to fiat currency instantly using an OTC (Over-the-Counter) desk or a physical crypto ATM. Pallapay operates 4 physical branches where you can exchange assets for cash in under 15 minutes. This service is vital for users who need immediate liquidity for physical cash requirements. Understanding how to spend cryptocurrency also involves knowing how to exit the market quickly when cash is the only accepted medium.

    Is it safer to use a virtual crypto card or a physical one?

    Virtual cards offer superior security for online transactions because they can be frozen or regenerated instantly after a single use. This reduces the risk of data breaches by 85% compared to static card numbers. Physical cards remain necessary for 2026’s brick-and-mortar stores that use NFC or chip readers. Both options utilize AES-256 encryption, but virtual cards provide an extra layer of protection against physical theft or skimming devices. For a comprehensive understanding of how these payment methods revolutionize spending, explore our detailed guide on crypto debit cards unlocking the future of payments in 2026.

    Disclaimer

    The information provided on this website and blog is for general informational and educational purposes only and does not constitute financial, investment, legal, tax, or other professional advice.
    Cryptocurrency and digital asset services may be subject to regulatory restrictions in certain jurisdictions. Users are solely responsible for ensuring compliance with applicable local laws and regulations before using any products or services mentioned on this website.
    PallaPay does not guarantee the accuracy, completeness, or timeliness of any information published and accepts no liability for any loss or damages arising from reliance on the content. Any opinions expressed are those of the respective authors and may change without notice.
    Certain services, features, or products referenced may be provided through third-party partners, licensed entities, or affiliated service providers subject to separate terms and regulatory approvals. Availability of services may vary by country or region.
    This website may contain references to digital assets, virtual currencies, or blockchain-related services that are not available to residents of certain jurisdictions, including where prohibited by law. Nothing on this website constitutes an offer, solicitation, or recommendation to buy or sell any financial instrument or virtual asset.