The fastest crypto card may not be a credit card at all. An instant virtual crypto card can provide a usable card number within 5 minutes of KYC approval. “Virtual” describes the card’s digital format, not whether it’s debit, prepaid, or credit.
When you need to pay online without waiting for a physical card, speed matters. So does the card type: a debit card spends from an available balance, a prepaid card uses funds loaded in advance, and a credit card provides a credit line backed by collateral.
This guide explains how an instant virtual crypto card works, what affects setup time, and how to compare fees and supported cryptocurrencies. It also clarifies the roles of Visa and Mastercard and the differences between debit, prepaid, and credit cards. Use these points to decide whether a virtual card suits your spending needs and what to check before applying.
Key Takeaways
- Learn how a virtual card turns supported crypto into a payment that merchants can process in fiat.
- Identify the different fee points to review, from card setup and top-ups to purchases and ongoing account costs.
- Understand why online purchases, recurring subscriptions, and advertising payments may have different payment requirements.
- Compare supported cryptocurrencies and networks before transferring funds, since compatibility can affect whether a payment works.
- Choose between debit, prepaid, and credit structures by understanding where the spending balance comes from and how it is used.
What Is an Instant Virtual Crypto Card?
An instant virtual crypto card is a digital payment card linked to a crypto account. It can let you pay online without waiting for a physical card, which typically takes 5 to 14 days to arrive. For eligible digital purchases, a virtual card can also be used for gift card purchases.
Crypto and Traditional Virtual Cards
A traditional virtual card draws from a bank account, debit balance, or credit line. A crypto card links spending to cryptocurrency held in an account. The merchant generally receives fiat through its card processor. Before using a card, identify the funding asset, when conversion happens, and which network it uses. Visa or Mastercard acceptance depends on the merchant and its payment arrangements.
Virtual and Physical Card Differences
A virtual card keeps its details in an account or digital wallet. It suits online payments where the merchant accepts its network. A physical crypto card provides another way to pay in person. Compare the options by payment setting, device compatibility, and issuer controls. Virtual issuance avoids delivery, while a physical card typically takes 5 to 14 days to arrive.
Crypto-to-fiat card payments follow several steps. The card checks the available balance and authorizes the purchase. The issuer or its processing system converts the required crypto into fiat, and the payment network routes the authorization to the merchant’s processor. The merchant receives payment in its settlement currency, while the account records the crypto used. Conversion rates and timing depend on the card’s process. Review the transaction record to confirm the final amount and asset deduction.
In the United States, spending cryptocurrency may have tax consequences. The transaction’s treatment depends on the asset’s value and the owner’s circumstances. Keep records of the asset, its acquisition cost, and the spending transaction for tax reporting.
Security involves account access, card details, and available funds. Enable two-factor authentication and use a unique password. If card information is exposed, freeze the card through account controls and report unfamiliar activity. Low-verification accounts may have monthly spending limits of $50 to $500 until full verification. The U.S. Government Publishing Office testimony says that no such protections exist for purchases made with cryptocurrency.
Card creation, transaction, top-up, and monthly fees
Card costs can include issuance, purchases, funding, currency conversion, and ongoing account charges. Spending limits depend on verification status, account rules, and supported assets.
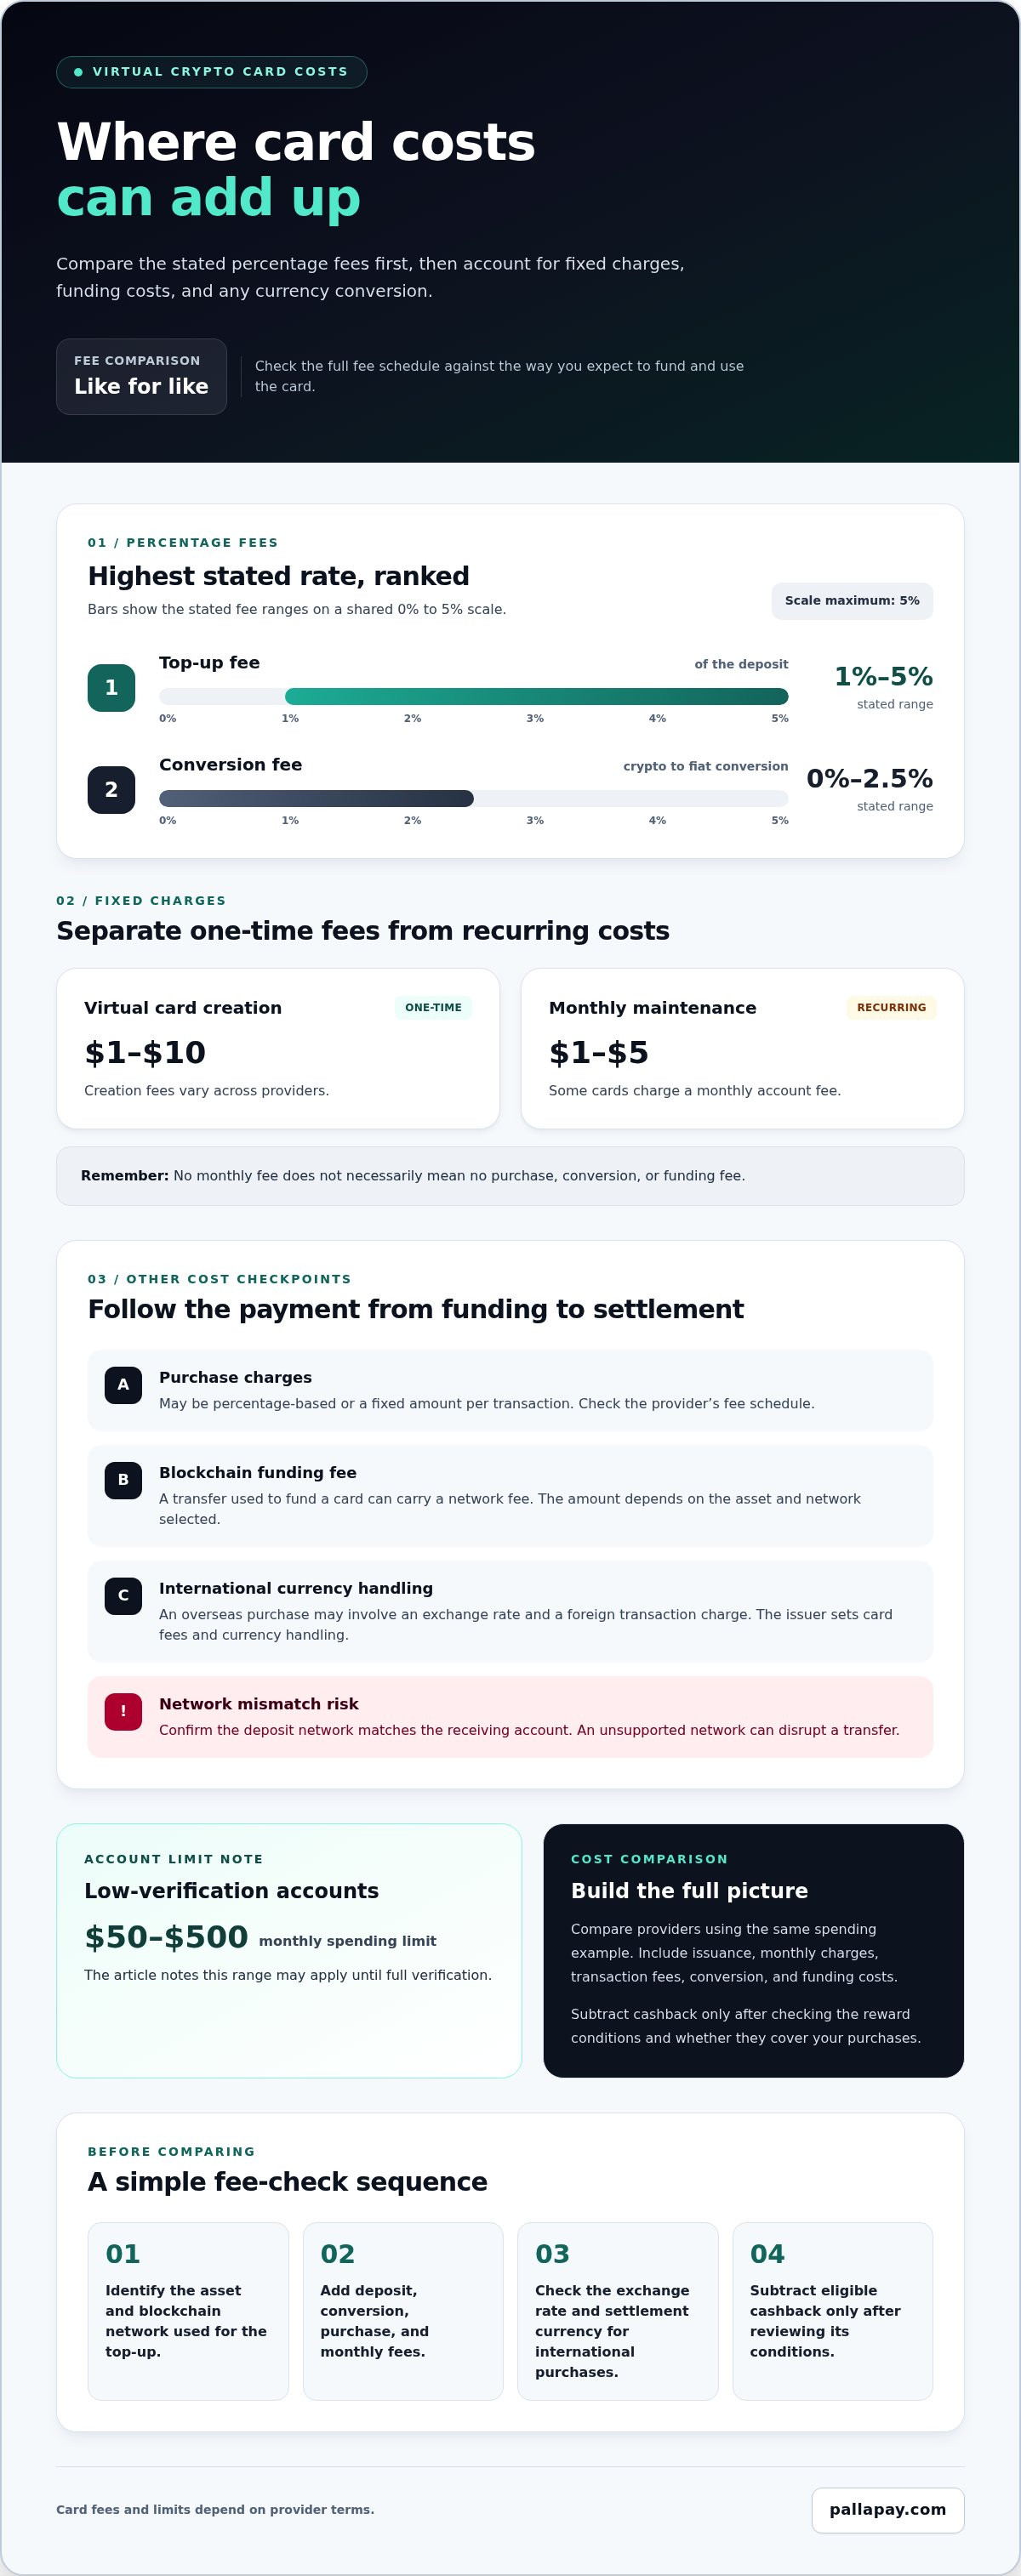
Across providers, creation fees range from $1 to $10, while conversion fees range from 0% to 2.5%. Low-verification accounts may have monthly spending limits of $50 to $500 until full verification.
Card Creation and Monthly Costs
Separate the one-time card creation fee from monthly maintenance charges. Virtual card creation fees range from $1 to $10, and some cards charge $1 to $5 per month. A card with no monthly fee can still charge for purchases, conversion, or funding. Compare the full fee schedule against your expected transaction pattern.
Transaction and Top-Up Charges
Purchase charges may be percentage-based or fixed for each transaction. Top-up fees range from 1% to 5% of the deposit. Add the purchase and funding charges together to estimate the total cost of a payment.
Provider Fees and Cashback
Compare providers using the same spending example, such as an online purchase and an account top-up. Include issuance, monthly charges, transaction fees, conversion rates, and cashback rewards. Cashback offsets costs only when its terms cover your purchases. Check eligible assets and reward conditions as well as the advertised rate, rather than comparing headline rewards alone.
International Transaction Costs
For an overseas purchase, the merchant’s currency may differ from the card’s settlement currency. Depending on the card terms, conversion may involve an exchange rate and a foreign transaction charge. Visa and Mastercard are payment networks; the issuer sets card fees and currency handling. Before paying, check the transaction currency and settlement details.
Network fees are separate from card purchase charges. A blockchain transfer used to fund a card can carry a network fee, and the amount depends on the asset and network selected. For example, USDT on TRC20 is a transfer option that usually offers cheap transfers. Confirm that the deposit network matches the receiving account, since sending funds through an unsupported network can disrupt a transfer.
To compare costs consistently, follow the payment from funding to settlement:
- Identify the asset and blockchain network used for the top-up.
- Add any deposit, conversion, purchase, and monthly fees.
- Check the exchange rate and settlement currency for international purchases.
- Subtract eligible cashback only after reviewing its conditions.
This breakdown helps distinguish a low advertised fee from a lower total cost. A Mastercard label identifies the payment network; it does not guarantee fee-free purchases or identical acceptance everywhere.
Online shopping, subscriptions, and advertising payments
An instant virtual crypto card can support online purchases wherever its payment network is accepted. Before checkout, confirm that the merchant accepts the network and billing country. Having a card number does not guarantee approval: the available balance must also cover the purchase and any authorization amount.
For an online purchase, enter the card number, expiration date, security code, and billing details. Make sure the billing address matches the card account. A mismatch can trigger a decline even when funds are available. For example, check the billing country before ordering from an international retailer.
Recurring subscriptions need extra attention. A streaming service may validate a card before its first charge, then bill it automatically again. Keep enough balance for the renewal date, and update the merchant if your card number changes. A replacement card can interrupt a subscription until you refresh the payment details.
Advertising platforms may also use recurring or threshold-based billing. If your business buys ads, make sure the card allows online transactions and can cover the platform’s next charge. A failed payment may pause billing or prompt the platform to request another payment method. Monitor both the card balance and the advertising account’s payment status.
To start online spending, follow these steps:
- Complete account verification and activate the virtual card.
- Review the card number, billing address, and spending controls.
- Fund the account with a supported asset and matching network.
- Enter the card details at checkout, then review the final currency.
- Check the transaction record after the merchant processes payment.
Digital wallets can simplify checkout, but the card and wallet must be compatible. Add the card through the wallet’s official app and follow its verification prompts. Adding a card successfully does not guarantee every merchant will accept that payment method. Keep your card details available for online stores that require manual entry.
Stablecoins can help make spending amounts easier to estimate. USDC and USDT are pegged 1:1 to the US dollar, though the card’s conversion and settlement process still affects the final charge. Check which stablecoin and blockchain network the account accepts before transferring funds. A network mismatch can prevent the intended balance from arriving.
Travel payments involve additional checks. A hotel may authorize a temporary amount before completing the bill, while a booking site may charge in another currency. Keep enough available balance for the authorization and check the transaction currency. In-person spending also requires a physical card or supported digital wallet, unlike online purchases made with card details.
If your account allows multiple virtual cards, use separate cards for distinct purposes. For example, assigning one to subscriptions and another to advertising can make transactions easier to review. Set a spending limit for each use, then check payment alerts and statements regularly. This can help you spot an unexpected renewal or unfamiliar merchant charge quickly.
Supported cryptocurrencies
Crypto card support depends on the asset, blockchain, account verification, and country. In the United States, a usable virtual card number may arrive within 5 minutes of KYC approval.
Instant virtual cards are available to U.S. residents after account approval. No-KYC options face more restrictions for U.S. users than for European users.
Supported Cryptocurrencies and Stablecoins
Start with the card’s supported-asset list, not the wallet balance. Bitcoin, Ethereum, USDT, and USDC are examples to look for, but support varies by card. USDC and USDT are pegged 1:1 to the U.S. dollar. That peg can make them easier to budget with than volatile assets, though the card’s conversion process still affects the final currency amount.
Before topping up, match the asset name and ticker exactly. A card may accept USDT but not every token with a similar label. Check whether the account converts the asset when funds arrive or when you make a purchase. That timing determines when the exchange rate applies.
Supported Tokens and Blockchain Networks
A supported token does not mean every network is supported. USDT on TRC20, for example, uses a specific blockchain route. TRC20 is commonly used as a low-cost transfer option, but the receiving account must accept that exact network. Confirm both the token and network before sending funds. A mismatch can prevent the deposit from reaching the intended balance.
Use this sequence before a top-up:
- Choose the card account’s supported cryptocurrency.
- Match the sending wallet’s network to the receiving network.
- Review the destination details before authorizing the transfer.
- Wait for the transfer to appear before spending.
Verification affects access as well as limits. Low-verification accounts may have monthly spending limits of $50 to $500 until full verification is completed. Automated KYC typically takes 2 to 10 minutes when documents are clear. Manual review can take 24 to 72 hours. These steps mean “instant” issuance generally refers to card availability after approval, not necessarily the entire signup process.
Country eligibility is another important filter. Card networks may operate internationally, but issuers set their own supported-country rules. Confirm that the provider serves your country before registering. For a U.S. account, review verification requirements, supported assets, spending limits, and virtual-card access together.
Digital wallet compatibility is separate from crypto support. A card that accepts USDT does not automatically work with Google Pay. Confirm that the issuer supports the wallet, then follow its card-adding and verification steps. Check three things separately: whether the asset is accepted, whether the card network is suitable, and whether the wallet can use the card.
Crypto debit, prepaid, and virtual credit card types
“Virtual” describes a card’s format, not how it’s funded. A crypto debit, prepaid, or credit card can each have virtual details, while a physical card offers another way to pay in person. Choose by checking where spending funds come from, how payments are authorized, and whether you need online or everyday access.
A crypto debit card draws from an available account balance. When a purchase is authorized, the card may convert supported crypto into the payment currency. This can suit everyday spending if you want to use existing funds rather than borrow. Before relying on a card for recurring bills, check which assets can fund purchases and how conversion works.
A crypto prepaid card uses funds loaded onto the card or its linked balance before spending. This can help separate a planned shopping budget from other assets. For example, you might load a set amount before buying digital services. Review reload methods, supported tokens, and transaction controls to understand how the balance works.
A virtual crypto credit card may work differently from debit and prepaid cards, so check how its credit and repayment terms operate before using it. Check how collateral supports the credit line, how repayment works, and what happens if the collateral’s value changes. The word “credit” alone does not explain these terms, so compare the account’s actual credit mechanics.
Card format and funding type are separate decisions. A virtual debit card can handle online payments, while a physical card can support in-person use where its network is accepted. A physical card can also use a debit or prepaid structure. Visa and Mastercard identify payment networks, not whether a card is debit, prepaid, or credit.
Digital wallet access is another separate feature. Before adding a virtual card to Apple Pay, confirm that the card supports the wallet and follow its verification steps. Wallet compatibility does not change how the card is funded. Similarly, network acceptance around the world does not mean every issuer serves every country; eligibility depends on the provider’s rules.
Use these distinctions to match the card type to your needs:
- Choose debit for spending from an available crypto-linked balance.
- Choose prepaid when you want to load funds before purchases.
- Consider credit only after understanding collateral and repayment terms.
- Choose virtual, physical, or both based on online and in-person payments.
For a crypto debit card, review supported assets, payment access, and account controls together. Explore crypto wallet options as a next step for managing digital assets alongside card spending.
Best Crypto Debit Cards 2026: Visa & Mastercard Compared: crypto debit card
Best Crypto Debit Cards 2026: Visa & Mastercard Compared helps you connect this guide’s card distinctions with a practical crypto debit card choice. Compare the payment network and account terms against your intended use.
| Comparison point | Visa card | Mastercard |
|---|---|---|
| Merchant acceptance | Depends on merchant and location | Depends on merchant and location |
| Crypto funding | Depends on issuer and supported assets | Depends on issuer and supported assets |
| Fees and rewards | Review the card’s terms | Review the card’s terms |
Pallapay offers a crypto debit card and options to sell Bitcoin or USDT for cash. Visit Pallapay.com to explore the available services.
Put Your Crypto Spending Plan Into Action
Choose the payment option that fits your next task. An instant virtual crypto card can support digital spending, while a direct crypto-to-cash transaction may suit a different need. Be clear about whether you want to pay with a card or convert an asset.
Best Crypto Debit Cards 2026: Visa & Mastercard Compared offers a crypto debit card, along with options to sell Bitcoin for cash and sell USDT for cash. These offerings provide distinct routes for spending or converting crypto, so select the one that matches your goal.
If you’re ready to explore an instant virtual crypto card and related options, contact Best Crypto Debit Cards 2026: Visa & Mastercard Compared. Start with the service that aligns with your plans, then take your next step with a clear understanding of how you want to use your digital assets.
Frequently Asked Questions
Do virtual cards expire?
Yes, a virtual card can have an expiration date, just like a physical card. Find the month and year in the card details, then update recurring payments before that date. If your issuer changes the card number, replace the saved details with the renewed card information. The expiration applies to the card credentials, not necessarily to the underlying account or crypto balance.
What is an instant virtual crypto card and how does it work?
An instant virtual crypto card is a digital card issued for electronic payments without waiting for physical delivery. After account approval, it provides card details for eligible online purchases or supported digital wallets. The payment network routes the transaction, while the linked account supplies funds and handles any crypto-to-fiat conversion. For example, a checkout priced in dollars can be paid using a supported crypto balance.
What are the eligibility requirements and supported states for US crypto cards?
Eligibility for U.S. crypto cards depends on the issuer’s onboarding rules and state availability. Applicants may need identity verification, and some providers request proof of address, such as a recent utility bill or bank statement. Before applying, review the issuer’s state list and required documents. A Visa or Mastercard network does not, by itself, establish availability in every state.
How quickly can I get and activate a virtual crypto card?
After KYC approval, most virtual crypto card providers issue a usable card number within 5 minutes. Automated verification typically takes 2 to 10 minutes when documents are clear, while manual review can take 24 to 72 hours. Once issued, follow the account’s activation instructions and confirm online payments are enabled. The overall wait depends mainly on verification and any review needed.
Which cryptocurrencies and wallets can fund a virtual crypto card?
Supported assets depend on the card. Pallapay lists BTC, ETH, XRP, SOL, TRX, BNB, DOGE, ADA, LTC, SHIB, PEPE, PALLA, DAI, USDT, and USDC. USDT supports ERC-20, TRC-20, SOL, and BEP-20; USDC supports ERC-20, BEP-20, and SOL. A wallet can fund the card only when its asset and network match the card account’s supported deposit route.
How do crypto card rewards, cashback, and staking requirements compare?
Compare reward eligibility, redemption rules, and any staking condition before choosing a card. Cashback may depend on purchase category, card tier, or holding requirements, so assess the terms rather than relying on the headline reward. Check whether a subscription qualifies and whether cashback is paid in fiat or crypto. Review these rules alongside transaction charges to understand the net value.
Where can I use a virtual crypto card online or through Apple Pay and Google Pay?
Use a virtual card for online payments at merchants that accept its network. Pallapay supports Visa and Mastercard cards, as well as Apple Pay and Google Pay for eligible cards. Wallet support does not guarantee acceptance at every merchant, so confirm the card is added successfully and the merchant accepts the network. You can still enter card details at checkout if a digital wallet is unavailable.
How do I apply for, verify, fund, and use a virtual crypto card?
Create an account and complete the issuer’s identity checks. After approval, open the card details and follow the activation steps. Transfer a supported cryptocurrency using the matching blockchain network, then confirm the balance appears before paying. At checkout, enter the card details or use an eligible mobile wallet. Keep the transaction record and review your account controls after each payment.
Disclaimer
The information provided on this website and blog is for general informational and educational purposes only and does not constitute financial, investment, legal, tax, or other professional advice.
Cryptocurrency and digital asset services may be subject to regulatory restrictions in certain jurisdictions. Users are solely responsible for ensuring compliance with applicable local laws and regulations before using any products or services mentioned on this website.
PallaPay does not guarantee the accuracy, completeness, or timeliness of any information published and accepts no liability for any loss or damages arising from reliance on the content. Any opinions expressed are those of the respective authors and may change without notice.
Certain services, features, or products referenced may be provided through third-party partners, licensed entities, or affiliated service providers subject to separate terms and regulatory approvals. Availability of services may vary by country or region.
This website may contain references to digital assets, virtual currencies, or blockchain-related services that are not available to residents of certain jurisdictions, including where prohibited by law. Nothing on this website constitutes an offer, solicitation, or recommendation to buy or sell any financial instrument or virtual asset.